
gm, crypto twitter. ☕💀
Jensen Huang might be ready for a comeback, but NVIDIA's board still has the final say. Meanwhile, Trump is heading into a high-stakes meeting with China, the US is preparing new cloud-computing restrictions, and Fed officials are increasingly talking about rate hikes.
Wall Street is dealing with geopolitical uncertainty, sticky inflation and a VIX above 25.
The AI trade wants Jensen back. The Fed wants inflation down. And markets just want a quiet day. Good luck with that. 🍿
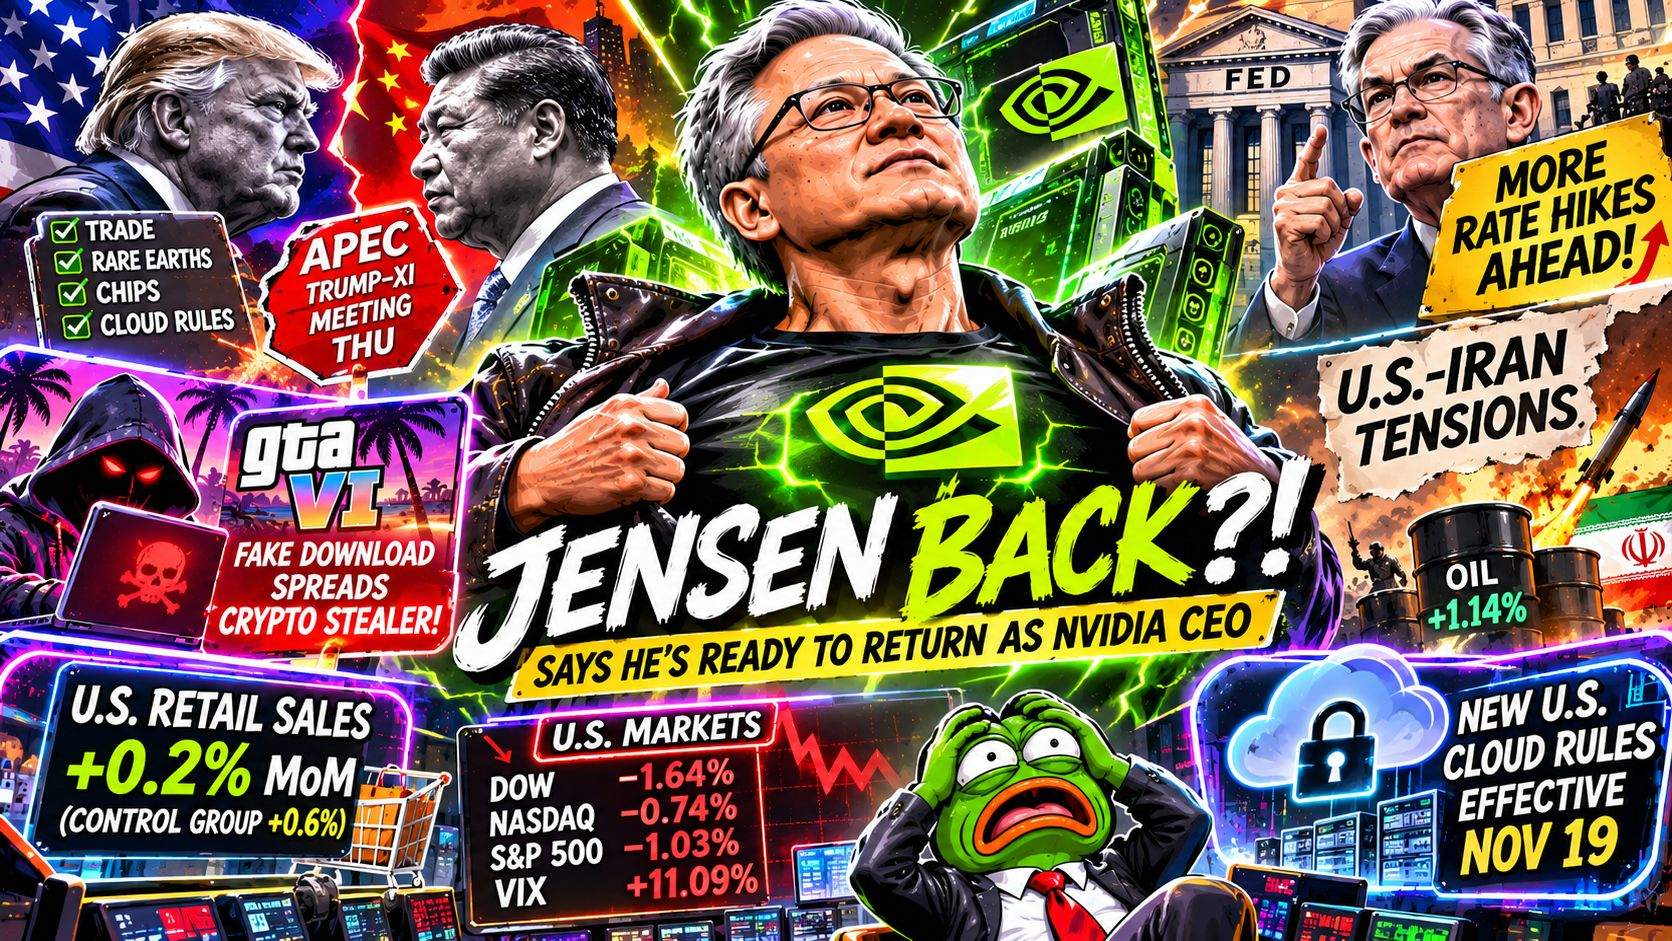
1/ 🚨 JENSEN HUANG SAYS HE IS READY TO RETURN TO NVIDIA
According to The Wall Street Journal, Jensen Huang said he was deeply moved by the support he received from outside parties and would be willing to return as NVIDIA CEO if the board allows it.
This adds another twist to NVIDIA's ongoing leadership saga.
Key questions:
Will the board reconsider its decision?
Could Jensen return to the CEO position?
Would investors regain confidence in NVIDIA's long-term direction?
📌 Market watch: NVDA, board decisions and potential leadership announcements.
The CEO comeback arc is officially on the table. NVIDIA might be getting a sequel nobody expected. 💀
2/ 🌏 TRUMP-XI MEETING: TRADE DEAL OR GEOPOLITICAL SHOWDOWN?
Trump is expected to arrive in Shenzhen on November 18 ahead of the China-US summit scheduled for Thursday.
His delegation reportedly includes:
Secretary of State Marco Rubio.
Treasury Secretary Scott Bessent.
US Trade Representative Jamieson Greer.
Other White House officials.
According to the report, Trump's advisers remain divided over China policy. One camp favors a friendlier relationship, while another wants a tougher approach focused on national security.
Trump also said the US could catch up with China's rare-earth production capacity within 10 months.
During his Manila visit, Trump met with leaders from Japan, India and Australia under the Quad framework, discussing critical minerals, rare earths, maritime security and regional economic cooperation.
📌 Market watch:
US-China trade negotiations.
Semiconductor and AI export restrictions.
Rare-earth supply chains.
Potential Chinese countermeasures.
One meeting could move markets more than a week of economic data. 👀
3/ 🛢️ US-IRAN CLASHES PUSH OIL HIGHER
Military tensions between the US and Iran have escalated again.
According to the supplied report:
The US struck Iranian missile-launch facilities near Qeshm Island.
Iran launched drones toward a US military radar facility in Bahrain.
Bahrain said its air defenses intercepted the attack without casualties or infrastructure damage.
The report also says the US maritime blockade of Iran costs approximately $32M per day, or nearly $1B per month.
Acting Navy Secretary Hung Cao confirmed the estimated daily cost during a Senate hearing, prompting Senator Elizabeth Warren to question the campaign's financial and military justification.
📌 Market watch:
Brent crude and energy prices.
Shipping and maritime security.
US defense spending.
Escalation risks across the Middle East.
Oil is getting another geopolitical premium. The market really didn't need another reason to worry about inflation. 💀
4/ 🛒 US RETAIL SALES SHOW CONSUMERS ARE STILL SPENDING
US retail sales increased 0.2% MoM in October, matching expectations but slowing from the previous month's 0.8% growth.
The control group, excluding autos, gasoline, building materials and food services, rose 0.6%, beating the 0.4% forecast.
Category highlights:
Gasoline sales: +1.5%.
Online sales: +1.2%.
Other retail stores: +4.7%, recovering from a 3.0% decline.
Autos and auto parts: -1.6%.
Furniture and home furnishings: -2.3%.
Food services: +0.2%.
The data suggests consumer spending remains resilient, but growth is uneven. Higher-income households continue to support overall consumption while some discretionary categories weaken.
📌 Market watch: Consumer resilience, inflation expectations and the Fed's next policy decisions.
The American consumer is still spending. Just becoming more selective about where the money goes.
5/ 🏦 FED OFFICIALS SIGNAL MORE RATE HIKES AHEAD
Fed officials are increasingly discussing additional tightening, with markets reportedly pricing in a 25-basis-point hike in December and at least two more hikes in 2027.
Three officials offered important signals:
John Williams, New York Fed President
Says further rate increases may be needed to bring inflation toward 2%.
Does not currently see a need for aggressive tightening.
AI infrastructure investment and stock-market wealth effects could support demand and potentially require more tightening in 2027.
Alberto Musalem, St. Louis Fed President
Says several rate hikes may be needed before spring 2027.
Suggests the policy rate may need to rise by approximately 100 basis points.
Believes acting early could help contain inflation without seriously damaging growth.
Beth Hammack, Cleveland Fed President
Maintains a hawkish position.
Supports establishing principles for potential Fed intervention during Treasury-market stress.
Says intervention should be considered if Treasury-market dysfunction threatens the broader economy.
📌 Market watch:
December FOMC expectations.
Treasury yields and the dollar.
AI investment and its impact on economic demand.
Liquidity conditions in the Treasury market.
AI investment is booming, but the Fed may respond by making money more expensive. The irony writes itself. 🤖
6/ ☁️ US CLOUD-COMPUTING RESTRICTIONS COULD TAKE EFFECT NOVEMBER 19
The US Commerce Department's new cloud-computing restrictions are moving toward implementation.
According to the report, BIS's interim final rule concerning remote access to advanced semiconductors and overseas cloud-computing services has entered the Federal Register publication process.
Document number: 2026-23529.
Expected publication: November 19.
Expected effective date: November 19.
Emergency information-collection approval is being pursued through the Office of Management and Budget.
The rules could affect overseas access to advanced computing capacity and semiconductor-related cloud services.
Attention is now turning to the Trump-Xi meeting and whether China will respond with countermeasures.
📌 Market watch:
NVIDIA and advanced AI chip exports.
Cloud infrastructure providers.
US-China technology policy.
Overseas access to AI computing capacity.
The AI race isn't just about who has the best chips. It's also about who gets permission to use them.
7/ 📊 MARKETS UNDER PRESSURE AS VOLATILITY JUMPS
Latest US market snapshot:
Equities
Dow Jones: -1.64%
Nasdaq: -0.74%
S&P 500: -1.03%
Russell 2000: -1.50%
US Treasury yields
2Y: 4.7977% (-2.95 bps)
10Y: 5.1068% (-2.43 bps)
30Y: 5.4558% (-2.16 bps)
Other markets
DXY: 103.5625 (-0.02%)
VIX: 25.45 (+11.09%)
Brent crude: $93.49 (+1.14%)
LBMA gold: $3,848.99 (-0.19%)
📌 Market watch: VIX above 25, geopolitical developments, oil prices and Treasury yields.
Stocks are falling, volatility is climbing, and the geopolitical calendar is getting crowded. Not exactly a risk-on morning.
👀 MY MARKET WATCHLIST
- NVDA: Jensen's potential return and board response.
- BTC / ETH: Watch risk sentiment as equities face pressure and Fed expectations turn hawkish.
- DXY / US Treasury yields: Key signals for liquidity and risk assets.
- Brent crude: Middle East tensions and potential inflation pressure.
- AI stocks: Cloud-computing restrictions and US-China negotiations.
- Gold: Safe-haven demand amid geopolitical uncertainty.
- VIX: Whether volatility remains above 25.
🧠 BIGGER PICTURE
Three forces are shaping the market:
AI and corporate leadership: Jensen's possible return could change NVIDIA's leadership outlook, while new US cloud restrictions may reshape global AI infrastructure.
Macro and monetary policy: Retail spending remains resilient, but Fed officials are signaling further tightening.
Geopolitics: The Trump-Xi meeting, rare-earth supply chains and US-Iran tensions could influence trade, energy and technology markets.
The AI industry wants cheaper computing, the Fed wants tighter financial conditions, and Washington wants more control over technology exports.
Those objectives are not exactly aligned.
What's the bigger market catalyst this week: Jensen's possible return, the Trump-Xi meeting, or the Fed's increasingly hawkish stance?
DYOR. Not financial advice.