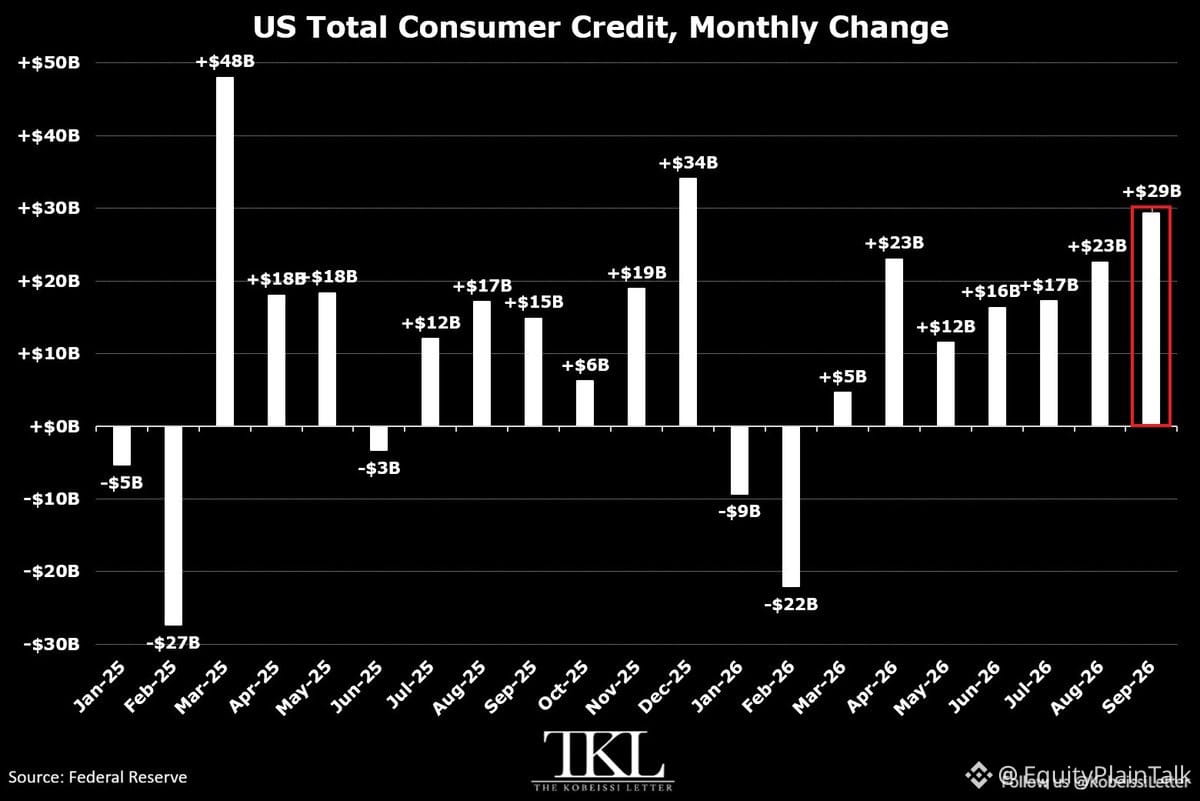
US consumers just added $29B in debt in September—biggest monthly jump since last December. Total consumer credit hit a record $5.19T.
Credit card balances alone surged $16B to $1.37T (new record). Auto and student loans up another $12B to $3.86T (also a record).
That's 7 straight months of rising debt, $125B total.
People aren't borrowing because they're confident. They're borrowing because prices are still high and paychecks aren't keeping up. When inflation eats into your budget, credit cards become the bridge.
This works until it doesn't. Higher debt means higher monthly payments. If the job market softens or rates stay elevated, those balances become a real problem.
Watch consumer credit closely. It's one of the clearest real-time signals of financial stress building under the surface.
Credit card balances alone surged $16B to $1.37T (new record). Auto and student loans up another $12B to $3.86T (also a record).
That's 7 straight months of rising debt, $125B total.
People aren't borrowing because they're confident. They're borrowing because prices are still high and paychecks aren't keeping up. When inflation eats into your budget, credit cards become the bridge.
This works until it doesn't. Higher debt means higher monthly payments. If the job market softens or rates stay elevated, those balances become a real problem.
Watch consumer credit closely. It's one of the clearest real-time signals of financial stress building under the surface.