US macro probabilities just flipped hard — and fast.
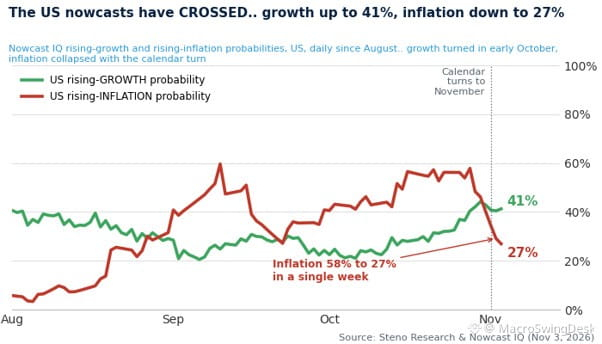
October started with rising-growth odds at 22%, weakest across all major regions tracked. Now? 41%.
Inflation probabilities collapsed even harder. From 58% on Oct 28 to 27% a week later. The lines crossed on Halloween.
Three catalysts:
• Brent crude dropped $118 → $104 in two sessions after Tehran signaled willingness to negotiate
• Shipping costs and refining margins already rolling over — tanker rates and gasoline cracks peaked
• Calendar effects kicking in — last year's energy spike starts falling out of the base in November
Regime shift in motion. "QE Like" environment (growth rising, inflation falling, liquidity ample) now at 35%. "Lame Duck QE" (stagflation vibes that dominated since September) down from 28% to 13% in a week.
Last time US growth probability turned this sharply? March. Led the April rally by six weeks.
Equity momentum hasn't caught up yet. That's the setup.
This is the edge: catching the turn before it shows up in the next CPI print. Growth, inflation, liquidity probabilities updated daily across US, Euro zone, UK, China, India — plus regime model and positioning reads.
Macro is moving. The question is whether you're positioned for what's coming or still fighting the last war.
October started with rising-growth odds at 22%, weakest across all major regions tracked. Now? 41%.
Inflation probabilities collapsed even harder. From 58% on Oct 28 to 27% a week later. The lines crossed on Halloween.
Three catalysts:
• Brent crude dropped $118 → $104 in two sessions after Tehran signaled willingness to negotiate
• Shipping costs and refining margins already rolling over — tanker rates and gasoline cracks peaked
• Calendar effects kicking in — last year's energy spike starts falling out of the base in November
Regime shift in motion. "QE Like" environment (growth rising, inflation falling, liquidity ample) now at 35%. "Lame Duck QE" (stagflation vibes that dominated since September) down from 28% to 13% in a week.
Last time US growth probability turned this sharply? March. Led the April rally by six weeks.
Equity momentum hasn't caught up yet. That's the setup.
This is the edge: catching the turn before it shows up in the next CPI print. Growth, inflation, liquidity probabilities updated daily across US, Euro zone, UK, China, India — plus regime model and positioning reads.
Macro is moving. The question is whether you're positioned for what's coming or still fighting the last war.