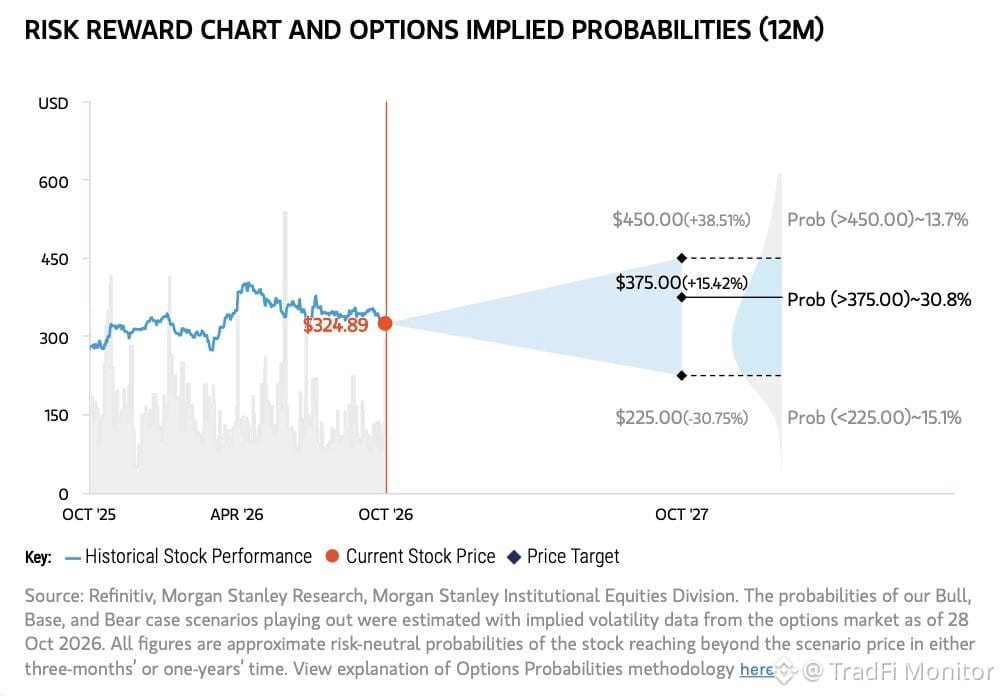
Moshaikh bought a sizable $GOOGL position into the post-rout drawdown.
The thesis is that the market is mispricing who can capitalize on the dislocation. Investors are extrapolating the large-cap advantage too broadly. Alphabet owns a full-stack AI solution (in-house infrastructure through distribution), while most peers are still building theirs from scratch. That means lower execution risk, less dependence on third-party suppliers, and better odds of converting the downturn into share gains.
The options overlay is still undecided. Calls, covered calls, or a collar each change the risk/reward on a core long. Without a defined strike and tenor, the position carries full delta and vol exposure.
The trade is a bet on vertical integration being undervalued during a risk-off tape. The main risk is further multiple compression if the macro drawdown extends.
The thesis is that the market is mispricing who can capitalize on the dislocation. Investors are extrapolating the large-cap advantage too broadly. Alphabet owns a full-stack AI solution (in-house infrastructure through distribution), while most peers are still building theirs from scratch. That means lower execution risk, less dependence on third-party suppliers, and better odds of converting the downturn into share gains.
The options overlay is still undecided. Calls, covered calls, or a collar each change the risk/reward on a core long. Without a defined strike and tenor, the position carries full delta and vol exposure.
The trade is a bet on vertical integration being undervalued during a risk-off tape. The main risk is further multiple compression if the macro drawdown extends.