


Deribit options price a 1.61% move in Bitcoin, about $1,304, over the day that holds Thursday's US GDP and PCE releases. That is a forward implied volatility of 30.7% for the window between the October 29 and October 30 expiries.
The figure comes from two short-dated expiries. Strip the variance the October 29 contract already prices out of the October 30 contract, and what is left is the day of the data. The day after it is priced higher, at 32.4%. Traders are not paying an event premium for the macro prints.
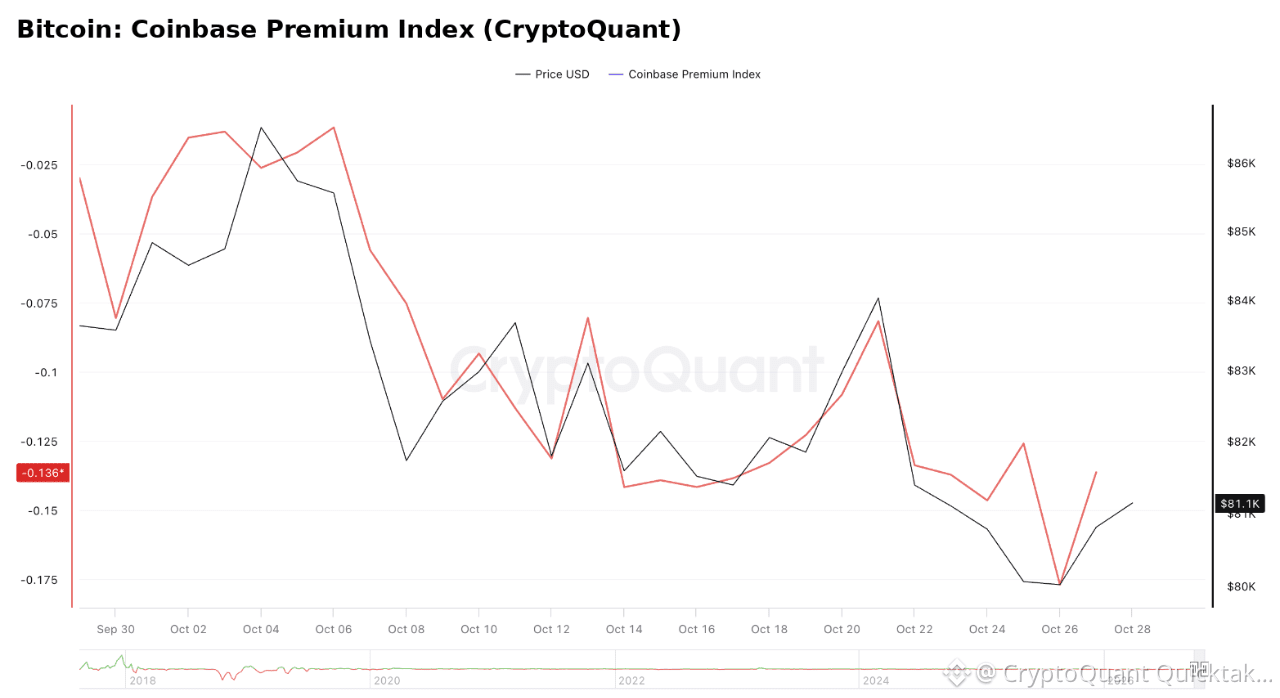
US spot buyers are not leaning in either. CryptoQuant's Coinbase Premium Index read -0.136 on October 27 and has stayed below zero on every day of the past month, with its deepest reading of the month, -0.177, on October 26. Bitcoin trades at a discount on the US venue, with spot at $81,134.
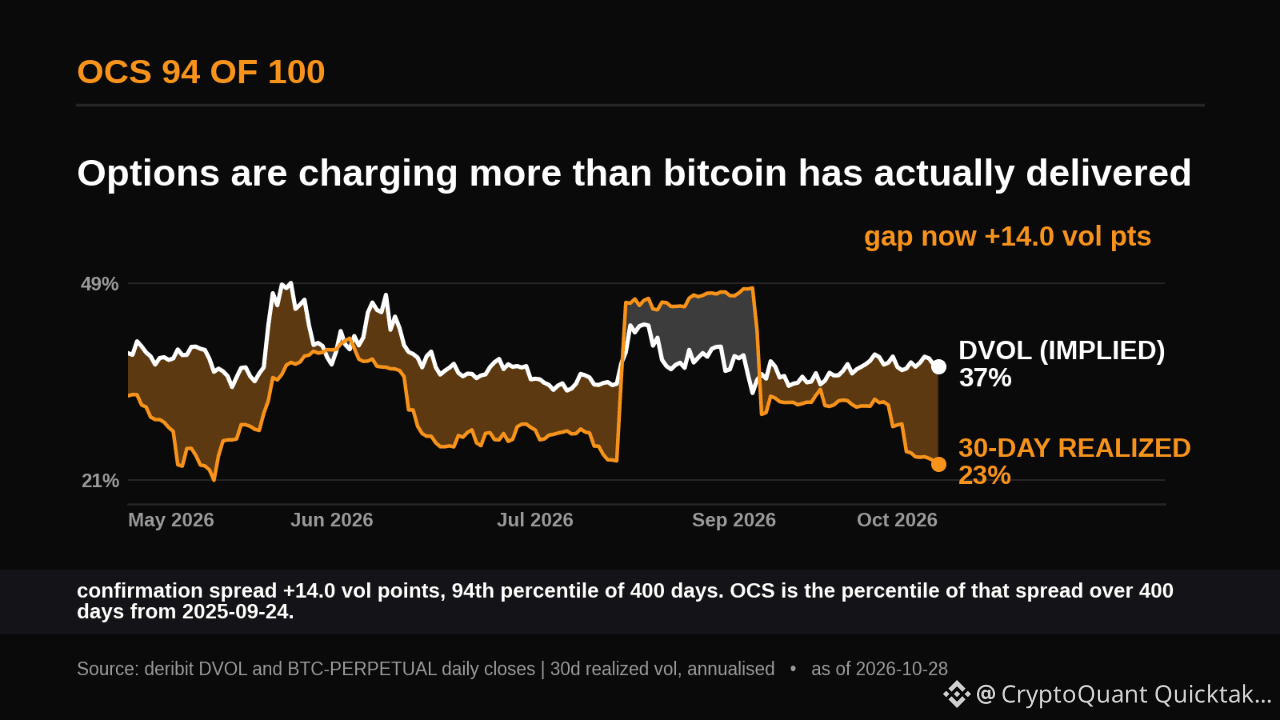
A caveat before calling calm pricing cheap. Options still charge more than Bitcoin delivers: DVOL sits at 37.44 against 30-day realized volatility of 23.46, an OCS of 94.5. In 16 distinct episodes in the DVOL record from March 2021 with OCS between 90 and 100, 30-day realized volatility finished above the implied level charged on entry only once.
The options market is treating Thursday's inflation data as an ordinary trading day.
What changes the read: a move larger than $1,304 in either direction between 08:00 UTC Thursday and 08:00 UTC Friday would show the data was underpriced. A Coinbase Premium Index back above zero after the release would show US buyers returning. A quiet day with the premium still negative keeps the calm read intact.
Written by The Daily Digits