

CENTRAL BANKS NAVIGATE SOFT LANDING PATHWAYS
Global economic policy enters a pivotal transition phase as major central banks align on cautious easing trajectories. Inflation figures across North America and Europe show steady moderation toward target levels, allowing policy committees to pivot focus toward maintaining labor market resilience and sustainable capital flow GLOBAL MACRO BRIEFING: INTEREST RATE POLICY & COMMODITY STRESS
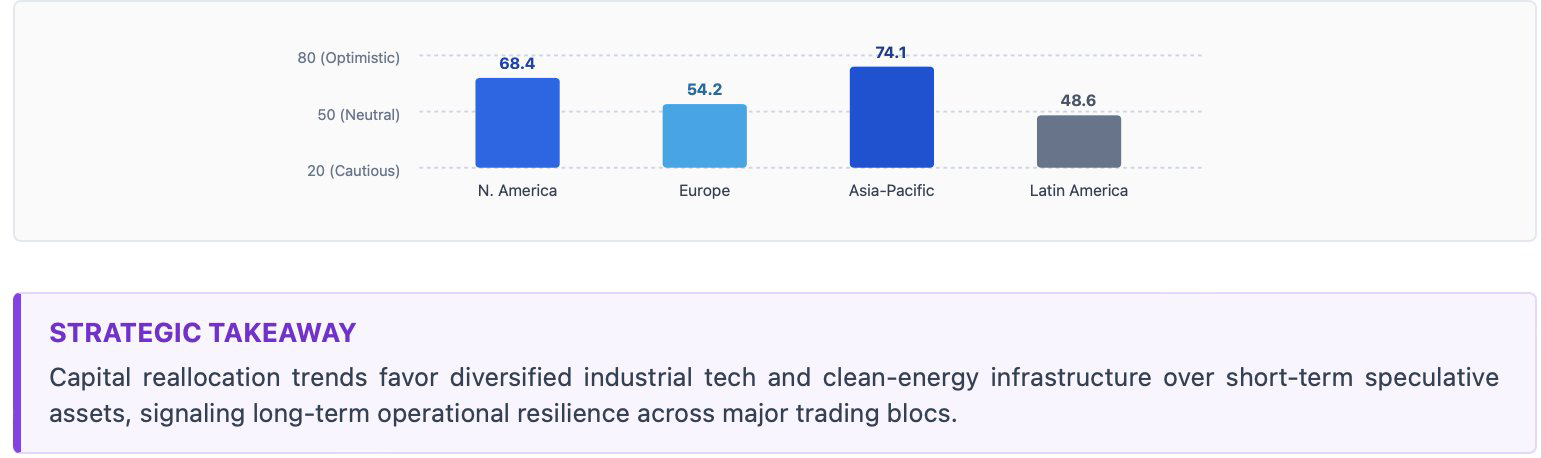
Regional Economic Sentiment Index
Americas Corridor
Consumer confidence indicators remain well-supported by robust service sector productivity and stable household savings balances.
EMEA Region
Energy grid transition funding reached record commitments this quarter, easing long-term operational margin concerns for manufacturing.
Asia-Pacific Rim
Export order volumes jumped modestly across high-tech manufacturing corridors, driven by sustained enterprise AI hardware demand.
GLOBAL MARKET BENCHMARKS & INDICATORS
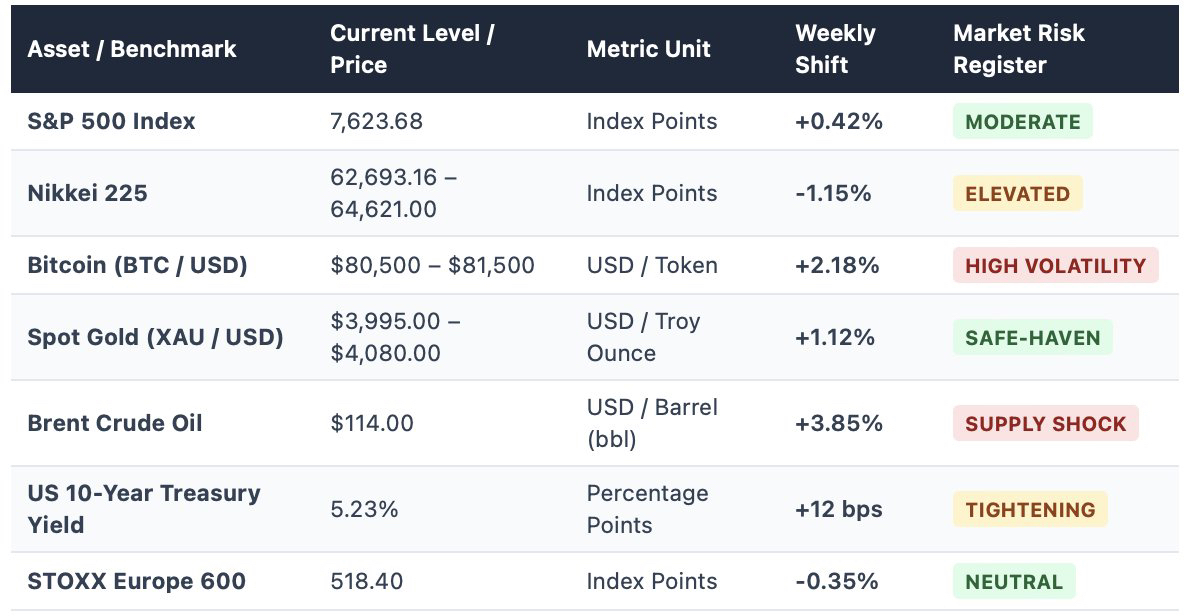
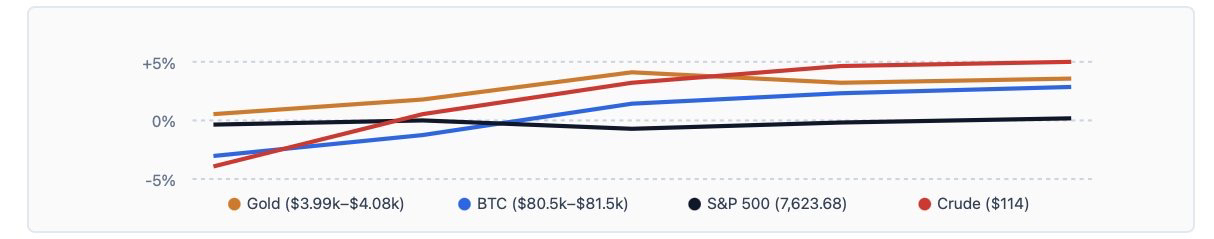
Cross-Asset Trajectory Index (Weekly Movement)
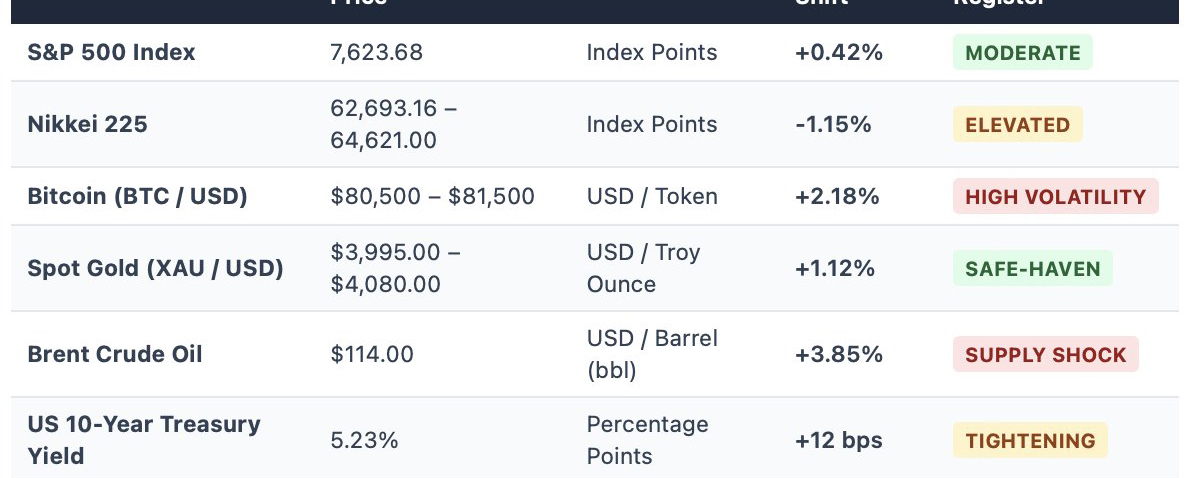
Global capital markets face cross-currents as major central banks balance elevated energy costs with corporate credit conditions. With Brent Crude elevated at $114/bbl, sovereign bond yields remain high, driving equity re-valuations and shifting institutional liquidity toward capital preservation instruments and mega-cap balance sheet fortresses.
Monetary Policy Outlook
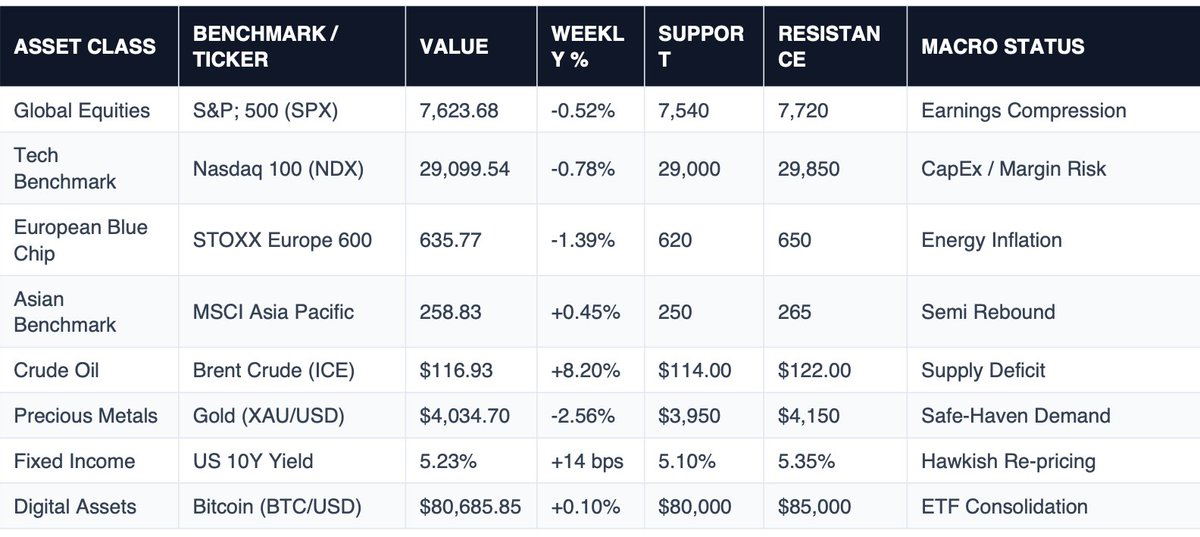
With sovereign bond yields remaining near 5.23%, central banks are signaling prolonged pauses. The macroeconomic stance favors mega-caps with minimal refinancing exposure.
Liquidity & Store of Value
Institutional digital asset inflows remain robust within the $80.5k–$81.5k corridor, acting as non-correlated liquidity alongside spot gold sovereign reserve accumulation.
MULTI-ASSET BENCHMARK SUMMARY
BITCOIN: ETF OUTFLOW SURGE & SUPPORT TEST
Bitcoin experienced sharp institutional liquidation mid-week before stabilizing around $81,500. Spot Bitcoin ETFs posted a massive single-day net outflow of $635.5 million, led by redemptions in BlackRock's IBIT
(-$254.1M) and Fidelity's FBTC (-$217.5M). The sell-off demonstrated BTC's continued short-term correlation with high-beta tech equities during sudden liquidity squeezes. $BTC 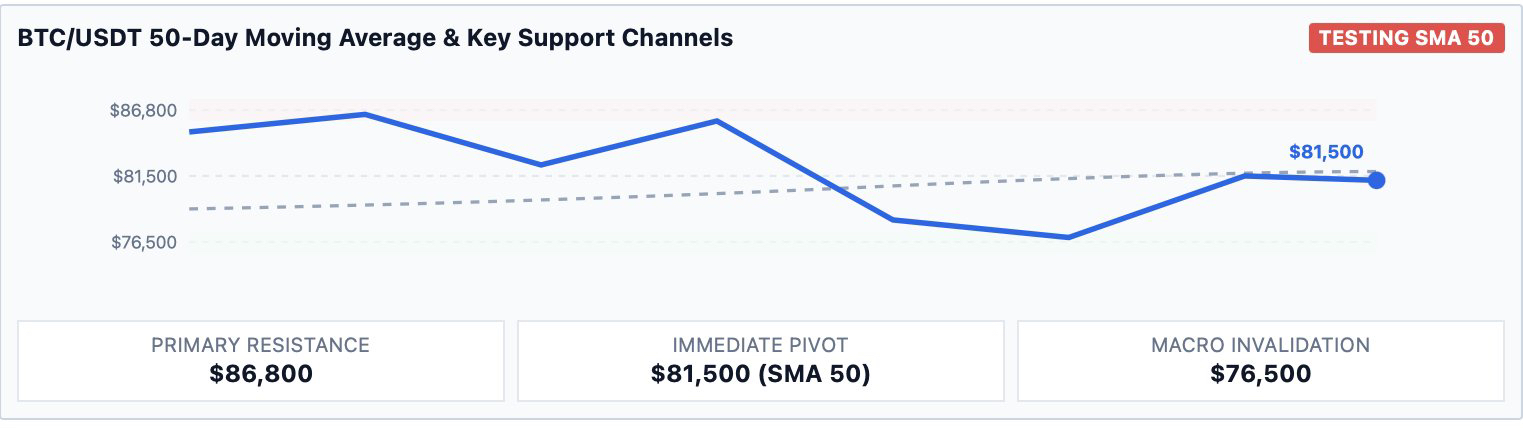
NORTH AMERICAN TECH & FINANCIAL HEAVYWEIGHTS
North American equity benchmarks, led by the S&P 500 at 7,623.68, demonstrate widening performance dispersion between hyper-scale tech infrastructure providers and cash-sensitive sectors.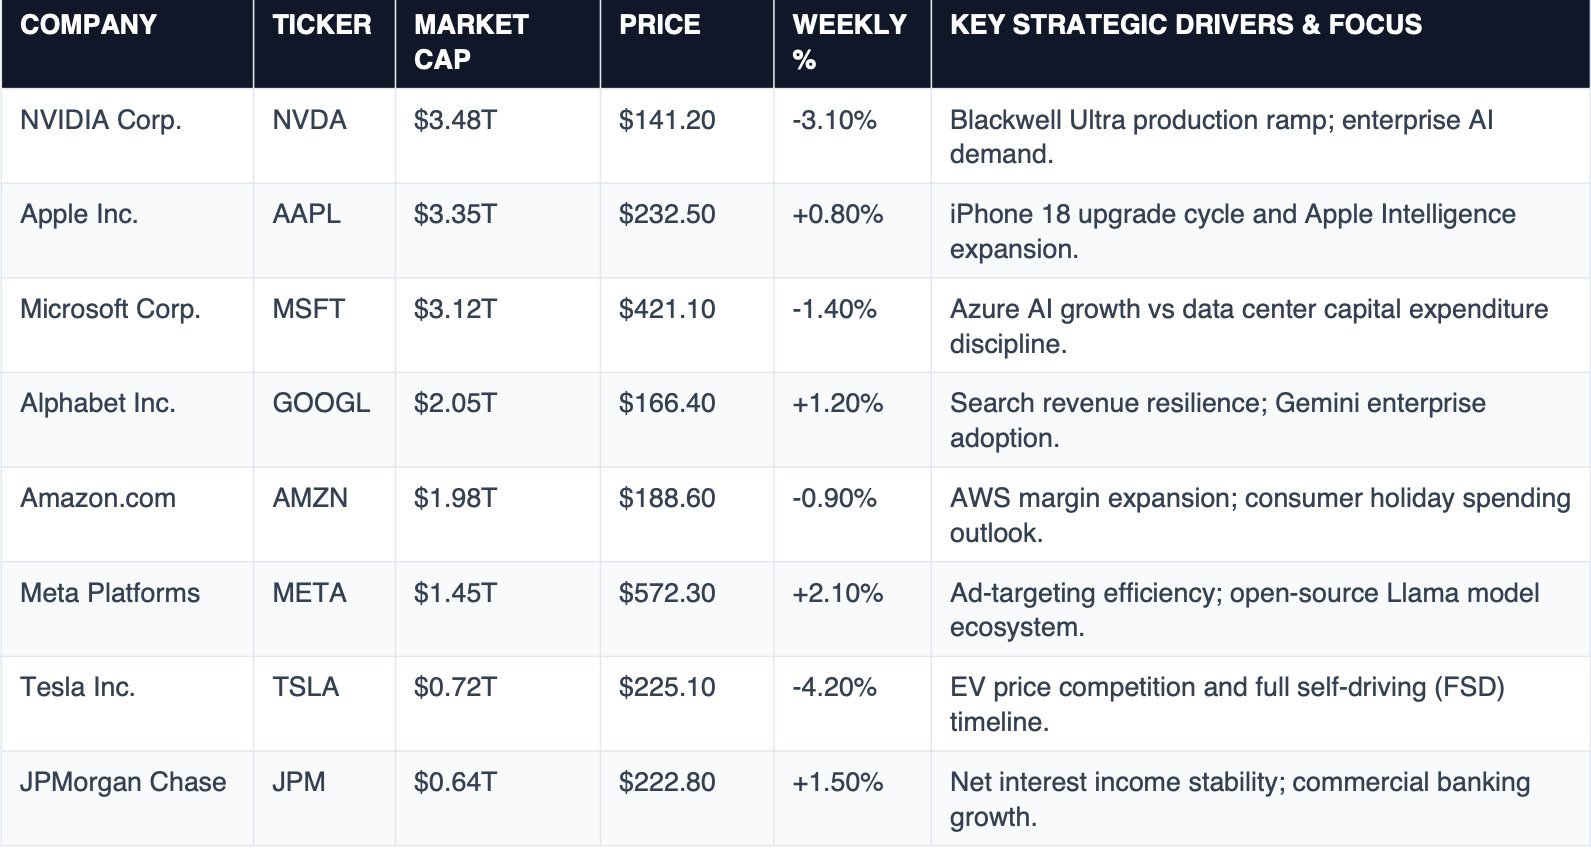
NVIDIA & Semiconductor Accelerators
NVIDIA maintains sector leadership via next-generation chip architecture deployments. Demand for data center compute platforms remains resilient, though export control adjustments continue to reshape regional delivery schedules.
Microsoft & Enterprise Cloud AI
Microsoft's Azure cloud suite recorded strong commercial expansion driven by copilot integrations. Capital expenditure in AI server capacity continues to expand balance sheet assets while maintaining top-tier operational margins.
Apple & Global Device Ecosystems
#Apple ecosystem retention and service subscription revenues offset hardware replacement cycle delays. On-device intelligence features are accelerating premium model upgrades across key North American and European markets.
Alphabet & Search Advertising
Alphabet displays robust search and cloud performance. Automated advertising platforms and proprietary generative infrastructure have bolstered cash flow generation despite regulatory scrutiny in regional markets.
Amazon & AWS Logistics Efficiency
#amazon Web Services (AWS) saw operating income expansion alongside fulfillment network regionalization. E-commerce segment margins are insulated by automated robotics deployment in core hubs.
Meta Platforms & Ad Monetization
#meta targeted advertising engine benefits from AI-driven recommendation models. Capital spend remains focused on data center upgrades, with digital ad unit pricing expanding across consumer segments.
Tesla & Next-Gen EV / Autonomy
#Tesla navigates EV price competition through cost-per-vehicle reductions and autonomous software licensing momentum. Energy storage deployments represent an expanding percentage of gross margins.
JPMorgan Chase & Banking Resilience
#JPMorgan Chase demonstrates commercial banking dominance with elevated net interest margins. Strong capital buffers and institutional advisory revenues offset consumer credit normalization trends.
EUROPEAN MEGA-CAP STOCKS & SECTOR CHAMPIONS
European equity performance reflects structural resilience in specialized healthcare, luxury heritage branding, semiconductor capital equipment, and energy sector cash buffers.
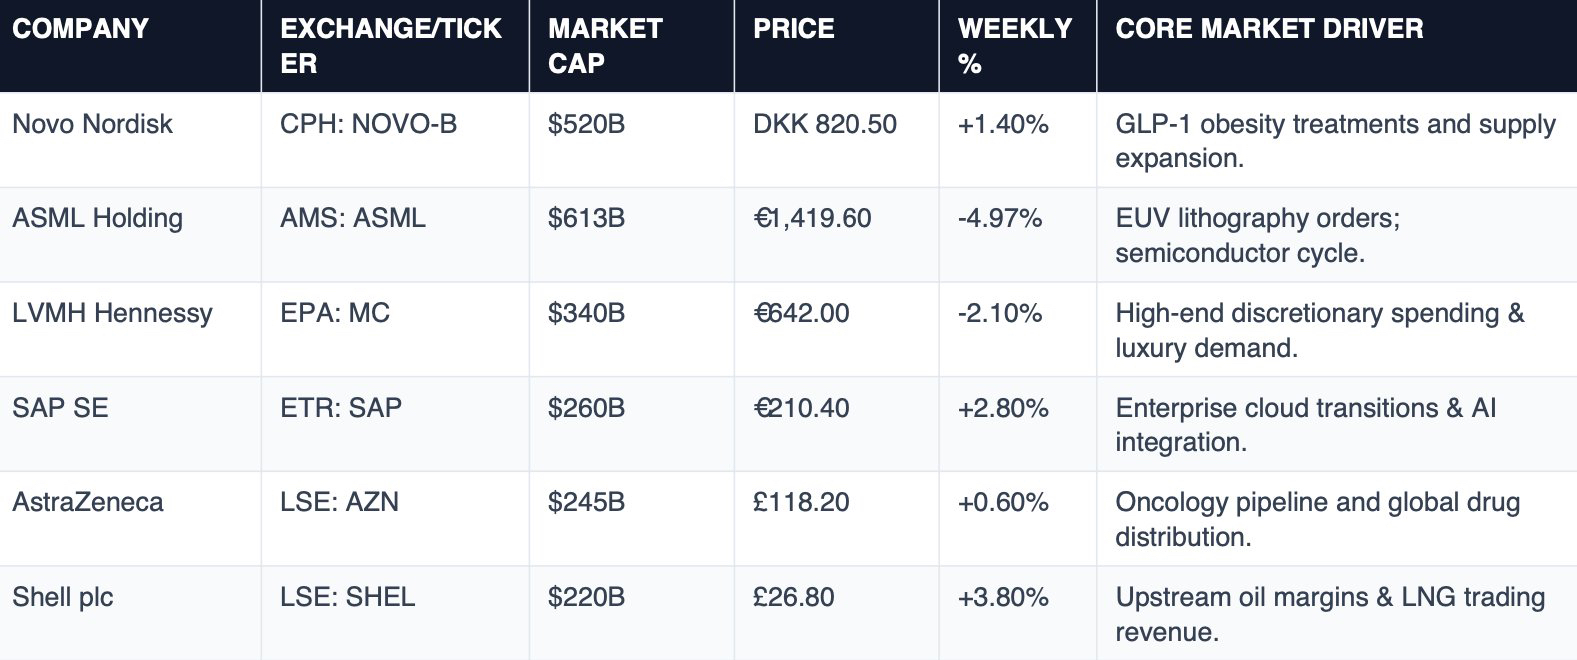
Novo Nordisk
Driver: GLP-1 Franchise
Novo Nordisk continues global expansion of Wegovy and Ozempic. Production capacity investments in Europe and North America are stabilizing supply constraints and supporting multi-year earnings visibility.
ASML Holding
Driver: Lithography Leadership
ASML's EUV (Extreme Ultraviolet) lithography systems remain essential for sub-2nm semiconductor fabrication. High-NA EUV shipments to tier-1 foundries secure long-term order backlogs.
LVMH Group
Driver: Luxury Heritage
LVMH maintains premium pricing power across Fashion & Leather Goods. Rebounding demand from high-net-worth international travelers cushions regional retail spending fluctuations.
SAP SE
Driver: Cloud ERP Migration
SAP's "Rise with SAP" cloud transformation initiative delivers double-digit cloud revenue expansion. Enterprise software retention across global industrial bases underpins cash flow predictability.
AstraZeneca
Driver: Oncology Pipeline
AstraZeneca advances targeted cancer therapies and biopharmaceuticals. Clinical trial milestones and expanding market authorization in Asia accelerate global revenue diversification.
HSBC Holdings
Driver: Global Banking & FXD
HSBC capitalizes on trade corridor financing between Europe and Asia. Wealth management expansion in Asia-Pacific compensates for lower European mortgage originations.
ENERGY SECTOR BUFFERS: SHELL & TOTAL ENERGIES
Shell plc (Energy Sector Buffer)
Shell leverages integrated gas and liquefied natural gas (LNG) trading platforms. High realized oil prices near $114/bbl enable continued share buybacks and deepwater exploration investment.
TotalEnergies SE (Multi-Energy Strategy)
TotalEnergies balances upstream hydrocarbon cash generation with utility-scale renewable power development. Disciplined capital allocation keeps payout ratios among the highest in European energy.
ASIAN MARKET LEADERS & HARDWARE SUPPLY CHAINS
Asian equities, anchored by the Nikkei 225 rebound (62,693.16 – 64,621.24), benefit from advanced semiconductor manufacturing, memory hardware super-cycles, and hybrid vehicle demand.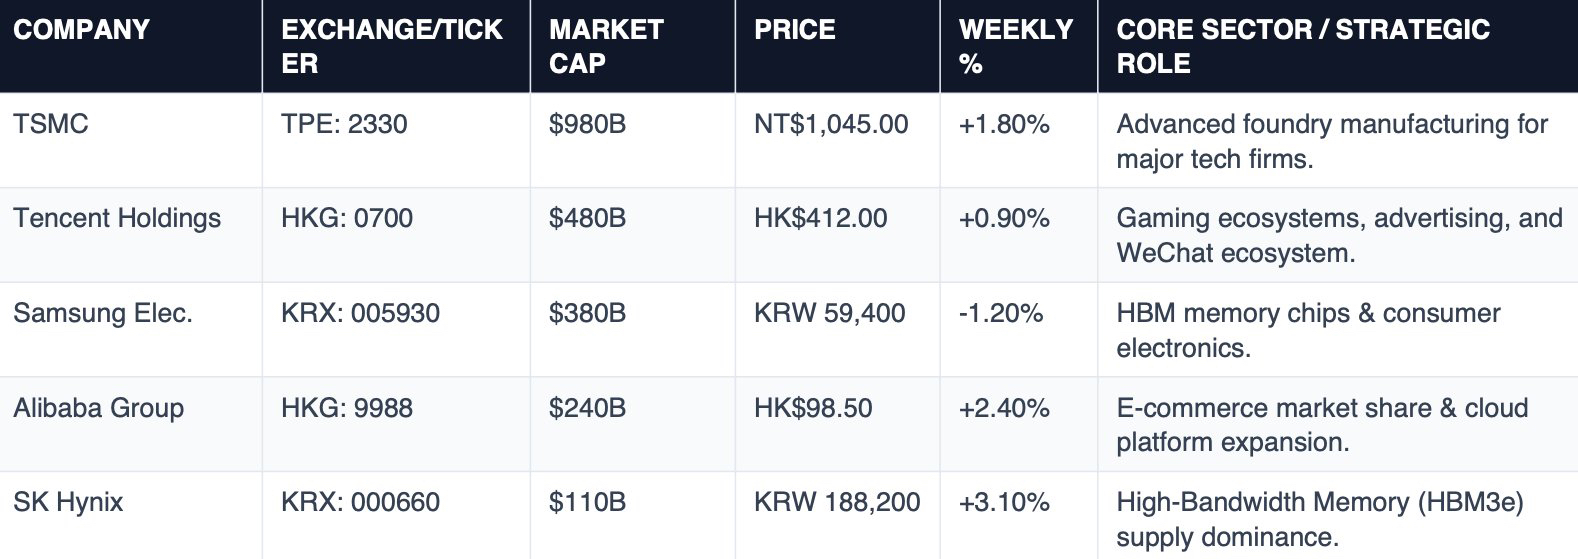
TSMC $TSMB
Advanced Foundry Dominance
TSMC commands over 60% of global foundry capacity and >90% of advanced node chips. N3 and N2 node expansion guarantees utilization rates driven by global AI hardware commitments.
Samsung & SK Hynix $SKHYB
HBM Memory Supply Chains
SK Hynix and Samsung dominate High Bandwidth Memory (HBM3e/HBM4) production. AI server memory requirements are driving pricing power and expanding semiconductor gross margins.
Toyota Motor
Hybrid & Auto Segment
Toyota achieves record operating income behind global consumer preference for hybrid powertrains. Manufacturing efficiency and favorable FX dynamics bolster net margin stability.
Tencent Holdings
Digital Ecosystems & Gaming
Tencent expands international gaming publishing and cloud advertising. Operational discipline and stock repurchases support equity valuation recovery in Asian markets.
Alibaba Group
Cloud & E-Commerce Logistics
Alibaba's Cloud Intelligence Group integrates proprietary AI models while Cainiao logistics accelerates cross-border e-commerce delivery speeds across Europe and Southeast Asia.
Reliance & ICBC
Emerging Market Giants
Reliance Industries leads energy-to-telecom expansion in South Asia, while ICBC maintains system liquidity leadership, supporting infrastructure finance across regional trade blocks.
GLOBAL STRATEGIC OUTLOOK & RISK REGISTER
Primary Risk Factors
1. Prolonged Crude Inflation ($114 Brent) squeezing consumer discretionary budgets.
2. High Sovereign Yields (5.23% 10-Yr) raising corporate debt refinancing costs.
3. Geopolitical Maritime Bottlenecks altering supply chain routing and transit times.
Institutional Portfolio Recommendations
Maintain overweight stances on global monopoly technology foundries, cash-generative energy majors, spot digital liquidity allocations, and physical gold reserves as inflation buffers.
KEY GEOPOLITICAL & STRATEGIC DEVELOPMENTS
Multilateral Summit Dynamics
Diplomatic delegations wrapped up intensive bilateral negotiations this week, focusing heavily on cross-border technological standards and supply chain transparency. Agreements signed in regional corridors emphasize joint investments in renewable grid infrastructure and secure data architecture.
Semiconductor Supply Chains
Global manufacturing clusters report normalized lead times for high-performance computing components. Strategic reserves established across secondary hubs have successfully mitigated localized logistics bottlenecks, stabilizing tech sector valuations globally.
AETHER GLOBAL RESEARCH NOTICE: This intelligence brief was written and prepared directly by Chief Market Strategist Farhan & Julian Vance for the Aether Global Research Division. All market data, earnings figures Asset performance history does not guarantee future results.
