

EXECUTIVE SUMMARY: THE DUAL SQUEEZE OF AI CAPEX AND ENERGY SHOCKS
Our analysis at Aether Global indicates that world markets stand at a critical inflection point on October 23, 2026. A powerful confluence of corporate structural shifts and macro-geopolitical friction is repricing financial assets across the globe. Technology equities are enduring a severe valuation recalibration following $METAB multi-billion dollar negative cash flow print, driven by aggressive AI infrastructure capex. Simultaneously, crude oil has spiked to multi-month highs near $114/bbl amidst military escalations surrounding the Strait of Hormuz. Meanwhile, corporate strategic activity—from $SPCXB ’s disruptive entry into US wireless infrastructure to massive financial services AI restructurings—signals that corporate leaders are pivoting toward lean, high-efficiency execution.
I. DAILY MARKET SNAPSHOT & KEY ASSET CLASS PERFORMANCE
Equity markets experienced significant cross-asset volatility on Thursday and Friday. High-flying technology mega-caps pulled broader indexes lower, while energy equities and commodities gained sharply on geopolitical risk premiums. Our proprietary tracking table below outlines core benchmark performance across international exchanges.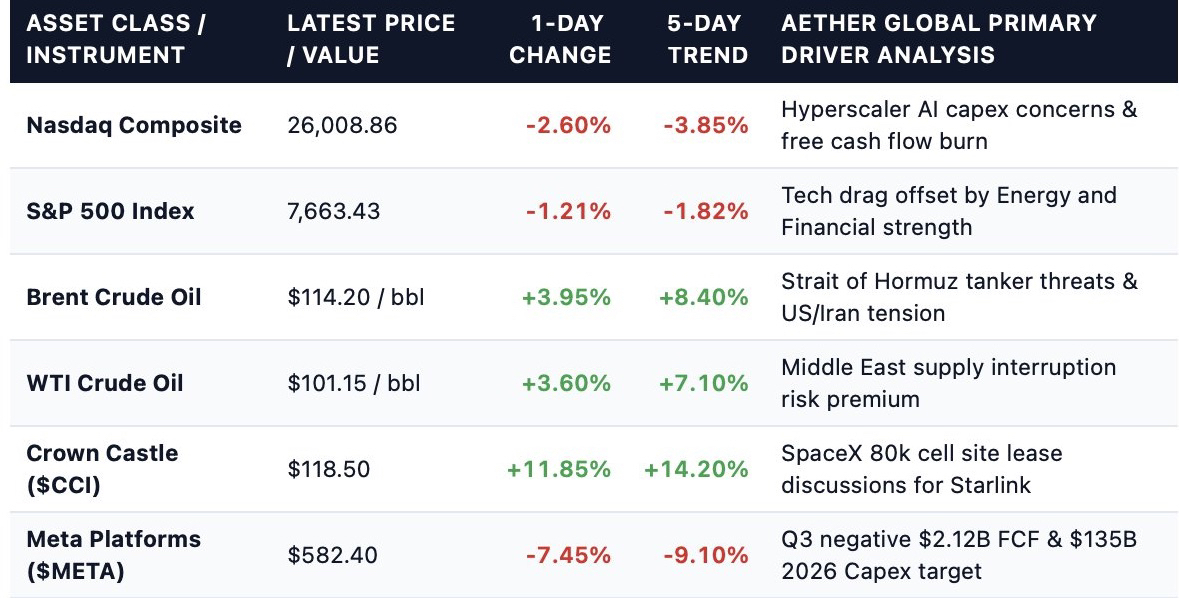
II. THE AI CAPEX RECKONING: HYPERSCALER FREE CASH FLOW SQUEEZE
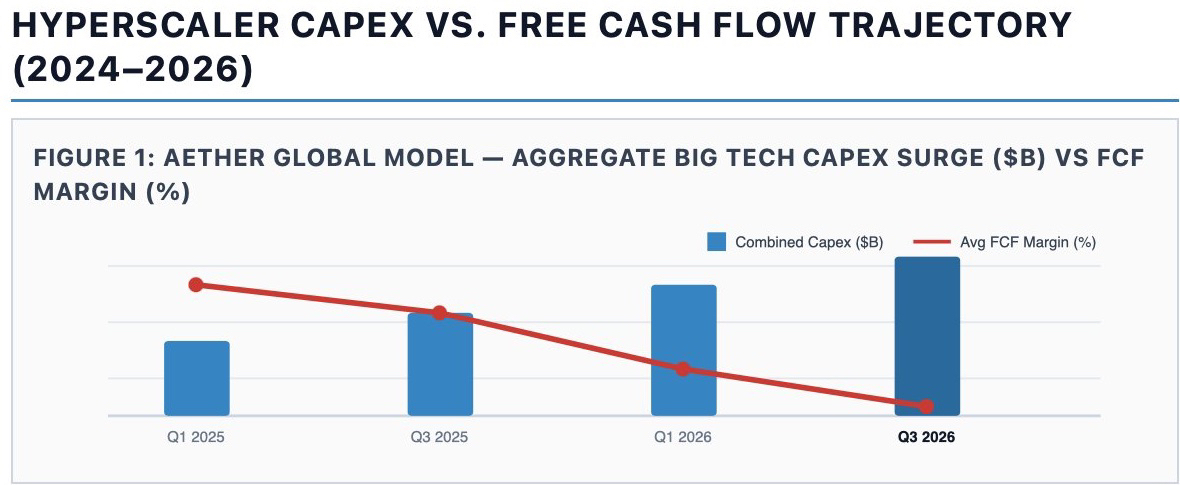
The market’s reaction reflects a broader structural transition identified by Aether Global: the shift from "hyperscale growth at any cost" to mandatory Return on Invested Capital (ROIC) accountability. Investors are demanding explicit monetization pathways for software applications, inference deployment, and enterprise workflow integration to justify annual capital spending now running at a $250B+ an annualized velocity across Meta, #Google Alphabet, #Microsoft , and #amazon .
III. CORPORATE RESTRUCTURING & M&A LANDSCAPE
Outside of mega-cap tech, today brought pivotal corporate moves across financial services, telecom infrastructure, luxury consumer goods, and healthcare.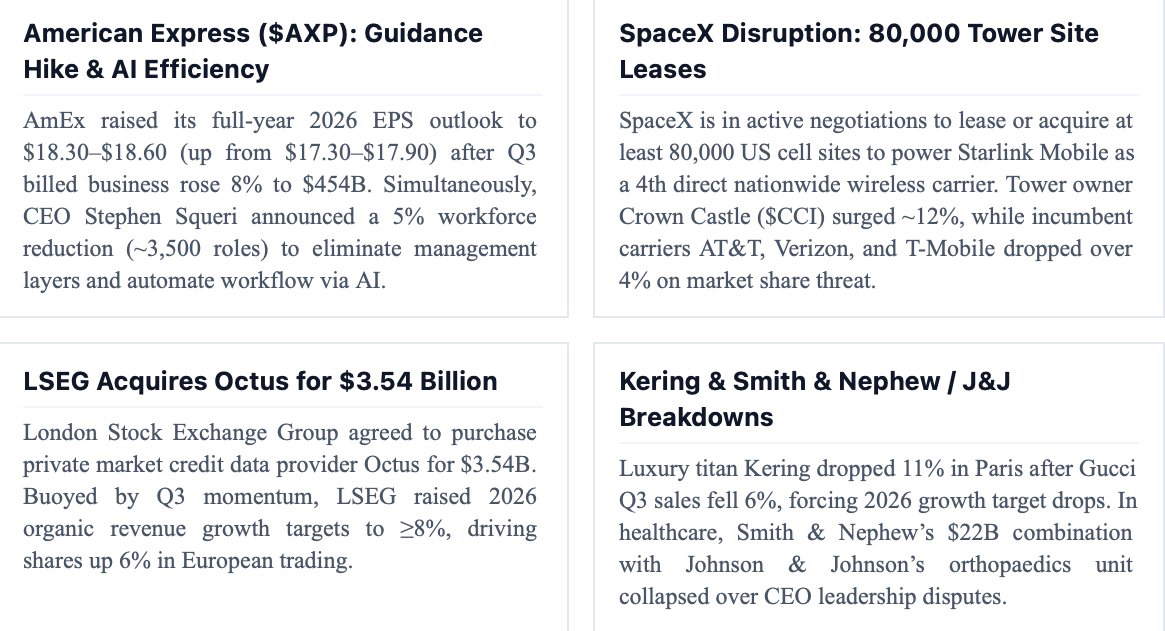
In Asia, South Korea's $SKHYB paused the prospective $10B US IPO of its Solidigm memory-chip unit. Citing global semiconductor equity volatility and regulatory warnings regarding dual-listing dilution risks, SK Hynix noted that its US manufacturing capital commitments remain unchanged despite the listing pause.
IV. GEOPOLITICAL RISK PREMIUMS & ENERGY MACROECONOMICS
The global energy landscape faced immediate supply disruption threats on Friday. Brent crude breached $114 per barrel while West Texas Intermediate (WTI) climbed past $101. The catalyst was a series of kinetic escalations near the Strait of Hormuz, including reports of damaged commercial oil tankers and military posture adjustments by US, Israeli, and Iranian forces. The Strait of Hormuz remains the world's primary energy bottleneck, facilitating the transit of approximately 20% of global petroleum liquids.
To bypass the high-risk maritime passage, Saudi Aramco has redirected partial volumes through its East-West Pipeline toward Red Sea export terminals. However, Aether Global energy strategists emphasize that alternative pipeline infrastructure cannot absorb a sustained maritime shutdown. Energy stocks globally outperformed, with European major Eni doubling its Q3 net profit to €2.8B and announcing an expanded €3.8B share buyback.
"A sustained crude price environment above $110/bbl acts as an unannounced tax on the global consumer. It injects fresh cost-push inflation into supply chains just as central banks were preparing to finalize their rate-cutting cycles." — Julian & Farhan, Aether Global
V. MACRO OUTLOOK: MONETARY POLICY & INFLATION INTERPLAY
The energy spike creates a complex dilemma for global central banks, particularly the US Federal Reserve. Heading into Q4 2026, monetary policymakers were navigating a slowing labor market and moderating core inflation. However, elevated energy costs threaten to re-anchor inflation expectations higher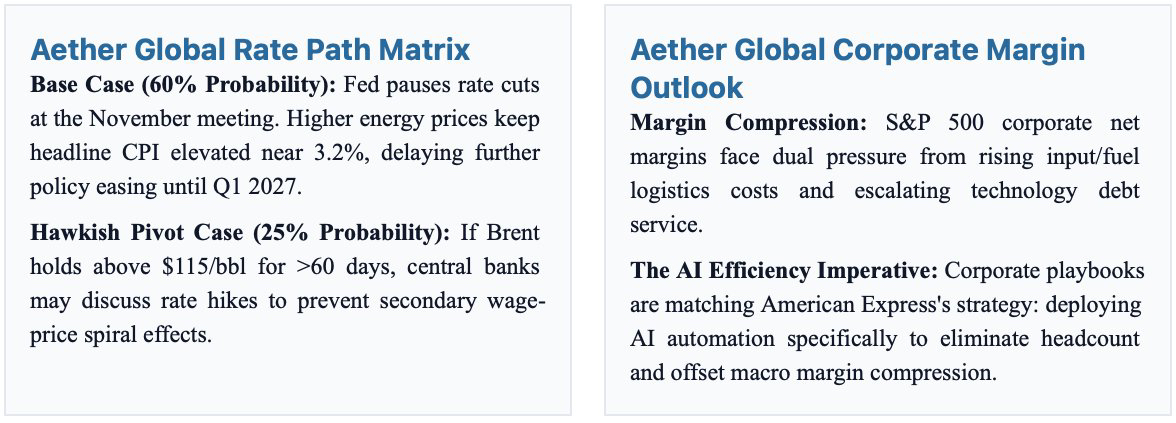
As corporate financial officers draft 2027 operational budgets, our intelligence indicates that emphasis has shifted decisively from aggressive market share acquisition toward operational agility, debt reduction, and strict capital allocation filters.
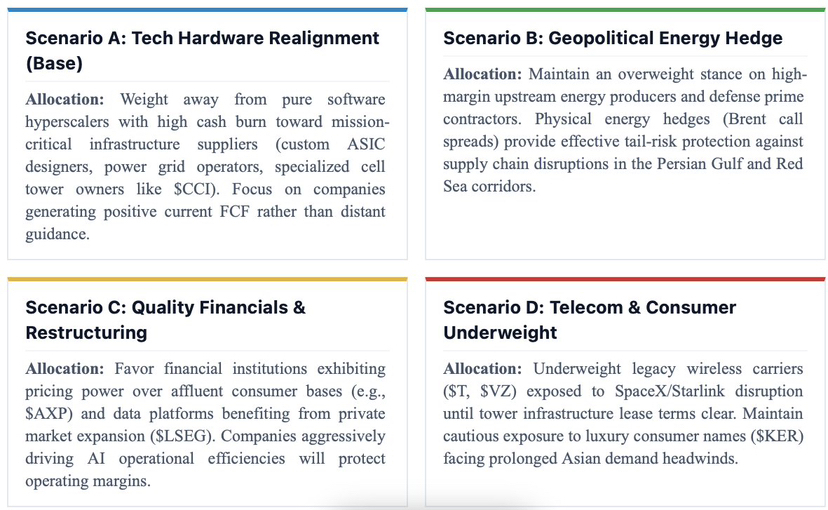
VI. ACTIONABLE INVESTMENT SCENARIOS (Q4 2026 – 2027)
In light of high hyperscaler capex volatility, elevated energy prices, and structural shifts in global infrastructure, Aether Global recommends institutional portfolio managers position across four distinct macro scenarios for the remainder of 2026 and early 2027.
VII. STRATEGIC CONCLUSION & FORWARD LOOK
October 23, 2026, marks a clear transition point in the current market cycle. At Aether Global, we contend that the "AI tailwind" can no longer blindly elevate equities without proof of capital efficiency and free cash flow generation. Simultaneously, traditional macroeconomic factors—geopolitical friction, energy supply security, and interest rate trajectories—have returned to center stage.
Investors and corporate executives who adapt to this dual regime—demanding discipline in technology investment while maintaining resilient hedges against geopolitical volatility—will be best positioned to navigate the market landscape into 2027.
AETHER GLOBAL RESEARCH NOTICE: This intelligence brief was written and prepared directly by Chief Market Strategist Julian and Farhan for the Aether Global Research Division. All market data, earnings figures, and strategic disclosures are current as of October 23, 2026. Asset performance history does not guarantee future results.
