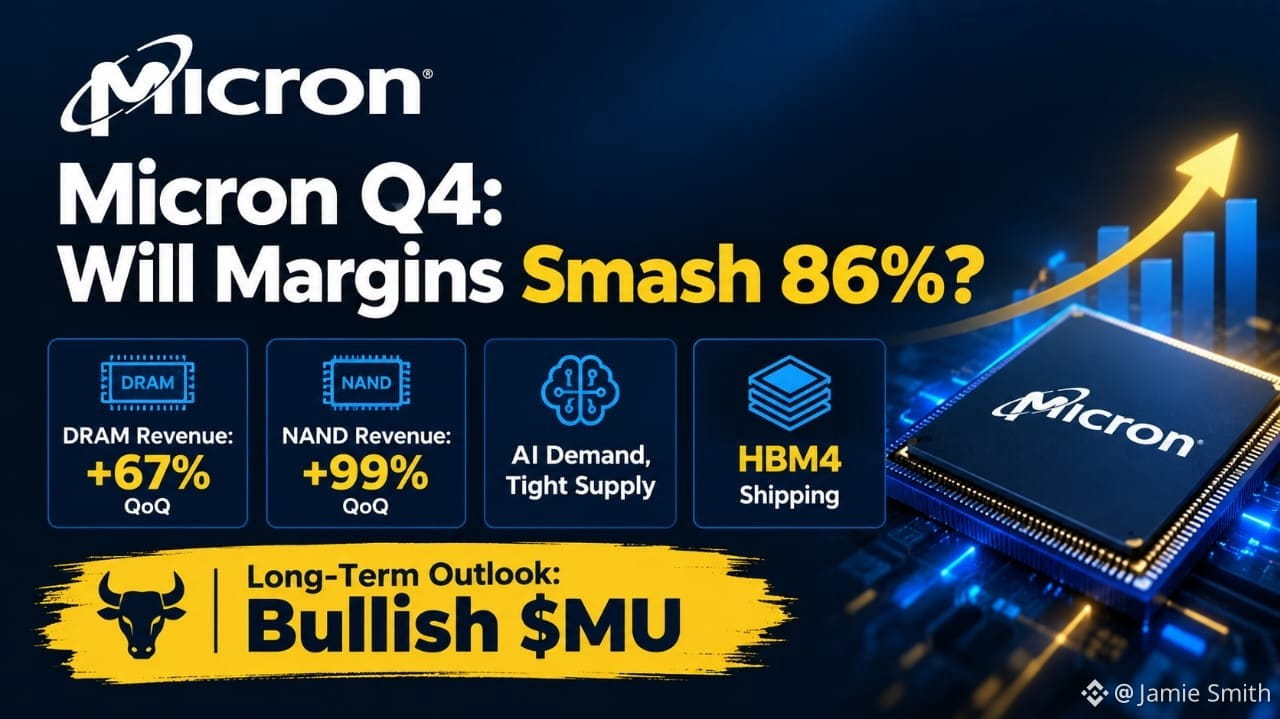

$MU Q4: Can Micron smash 86% gross margin and extend the memory supercycle?
Micron guides for $50B revenue and 86% gross margin, up from 84.9% in Q3. DRAM revenue surged 67% QoQ, NAND jumped 99%, and HBM4 is shipping in volume.
The real catalyst? Tight DRAM/NAND supply, strong AI demand, and improving product mix could push margins beyond 86%.
Micron expects supply constraints beyond 2027, with gradual relief in 2028. Its 16 strategic customer agreements strengthen long-term demand visibility through 2030.
My outlook: Bullish on MU, with gross margin and forward guidance as key indicators.
The big question: Is 86% just the beginning, or will Q4 expose the limits of this supercycle?
#EarningsSeason #MU