Global stocks hold gains, but market breadth remains narrow
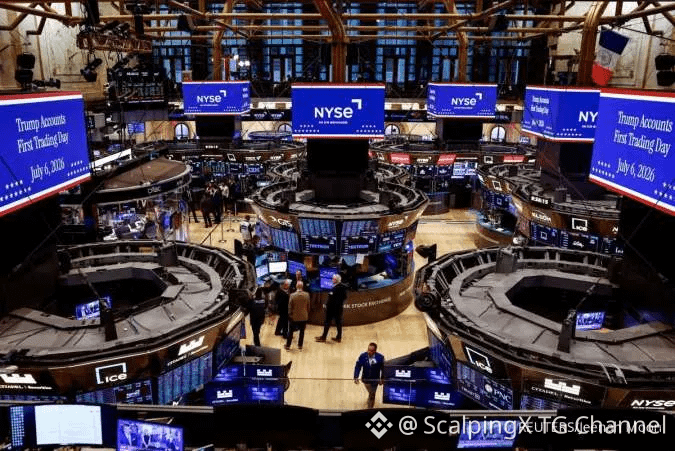
📈 U.S. equities ended the September 21–25 week higher, with the S&P 500 up about 1.2%, the Nasdaq gaining more than 2%, and the Dow rising only around 0.3%. Technology and AI-related names remained the main drivers, helping large-cap indexes advance despite persistent pressure from elevated yields.
📊 The U.S. 10-year Treasury yield briefly moved above 5.2%, while oil stayed near high levels before easing into the end of the week. The pullback in both yields and energy prices on Friday reduced pressure on equities, but it was not enough to produce a broad-based risk-on move.
🔍 Market breadth remains a key point to watch. The Nasdaq and S&P 500 advanced while small caps, value, utilities and several non-tech groups lagged. Capital therefore continues to concentrate in mega-cap and AI infrastructure names rather than spreading evenly across the market.
🌍 Europe recovered modestly after three weeks of declines, while Japan remained supported by technology shares and a weaker yen. Hong Kong and several emerging markets were less constructive, highlighting continued regional divergence.
📌 U.S. PCE data on September 30 will be one of the key catalysts next week. Softer inflation could ease pressure from yields, while persistently high rates would keep testing valuations in growth stocks.
#MarketInsights $NVDA $MU $GOOGL
📈 U.S. equities ended the September 21–25 week higher, with the S&P 500 up about 1.2%, the Nasdaq gaining more than 2%, and the Dow rising only around 0.3%. Technology and AI-related names remained the main drivers, helping large-cap indexes advance despite persistent pressure from elevated yields.
📊 The U.S. 10-year Treasury yield briefly moved above 5.2%, while oil stayed near high levels before easing into the end of the week. The pullback in both yields and energy prices on Friday reduced pressure on equities, but it was not enough to produce a broad-based risk-on move.
🔍 Market breadth remains a key point to watch. The Nasdaq and S&P 500 advanced while small caps, value, utilities and several non-tech groups lagged. Capital therefore continues to concentrate in mega-cap and AI infrastructure names rather than spreading evenly across the market.
🌍 Europe recovered modestly after three weeks of declines, while Japan remained supported by technology shares and a weaker yen. Hong Kong and several emerging markets were less constructive, highlighting continued regional divergence.
📌 U.S. PCE data on September 30 will be one of the key catalysts next week. Softer inflation could ease pressure from yields, while persistently high rates would keep testing valuations in growth stocks.
#MarketInsights $NVDA $MU $GOOGL