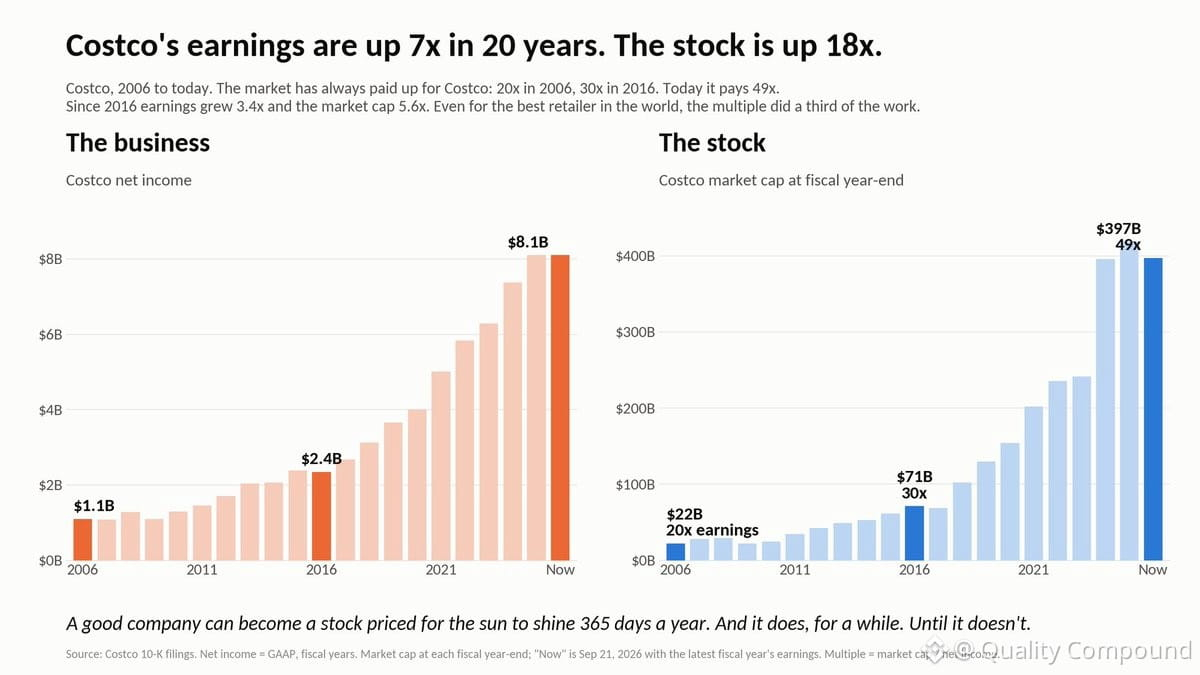
$COST — terrific business, no question. Earnings compounded beautifully over 20 years, up 7x. Stock's done even better, up 18x.
But here's the thing: that delta is all multiple expansion. We went from 20x P/E in 2006 to 30x in 2016, now sitting at 49x today.
At 49x, you're not just buying Costco's execution — you're pricing in perfection. You're assuming nothing goes wrong, competitive dynamics stay benign, and the next 20 years are somehow better than the last. That's a high bar.
I respect the franchise. But valuation matters. At these levels, the margin for error is razor-thin.
But here's the thing: that delta is all multiple expansion. We went from 20x P/E in 2006 to 30x in 2016, now sitting at 49x today.
At 49x, you're not just buying Costco's execution — you're pricing in perfection. You're assuming nothing goes wrong, competitive dynamics stay benign, and the next 20 years are somehow better than the last. That's a high bar.
I respect the franchise. But valuation matters. At these levels, the margin for error is razor-thin.