

Coincamps
380 منشورات

Coincamps
إبلاغ
حظر المُستخدم
🔍 Where Crypto & AI Minds Gather,Signal for Crypto & AI Builders
https://coincamps.ai
فتح تداول
مُتداول عرضي
2.3 سنوات
5 تتابع
1.3K+ المتابعون
49 إعجاب
منشورات
الحافظة الاستثمارية
·
--
عرض الترجمة
UPBIT LISTING: 돌핀(POD) 신규 거래지원 안내 (KRW, BTC, USDT 마켓)
UPBIT LISTING: 돌핀(POD) 신규 거래지원 안내 (KRW, BTC, USDT 마켓)
POD MarketCap: 26M
UPBIT LISTING: 돌핀(POD) 신규 거래지원 안내 (KRW, BTC, USDT 마켓)
UPBIT LISTING: 돌핀(POD) 신규 거래지원 안내 (KRW, BTC, USDT 마켓)
POD MarketCap: 26M
UPBIT LISTING: 돌핀(POD) 신규 거래지원 안내 (KRW, BTC, USDT 마켓)
POD MarketCap: 26M
77
·
--
عرض الترجمة
Bithumb Listing: [마켓 추가
Bithumb Listing: [마켓 추가
Bithumb Listing: [마켓 추가
Bithumb Listing: [마켓 추가
Bithumb Listing: [마켓 추가
·
--
عرض الترجمة
BWENEWS: The near intents vulnerability has been patched, full user compensation is planned, and operations will resume within one hour: Near intents on X
BWENEWS: The near intents vulnerability has been patched, full user compensation is planned, and operations will resume within one hour: Near intents on X
BWENEWS: The near intents vulnerability has been patched, full user compensation is planned, and operations will resume within one hour: Near intents on X
BWENEWS: The near intents vulnerability has been patched, full user compensation is planned, and operations will resume within one hour: Near intents on X
BWENEWS: The near intents vulnerability has been patched, full user compensation is planned, and operations will resume within one hour: Near intents on X
31
·
--
BWENEWS: تم إصلاح ثغرة «النيّات القريبة»، وتخطَّط للتعويض الكامل للمستخدمين، وسيستأنف تشغيل العمليات خلال ساعة واحدة: «النيّات القريبة» على X
تم إصلاح ثغرة «النيّات القريبة»، وتخطَّط للتعويض الكامل للمستخدمين، وسيستأنف تشغيل العمليات خلال ساعة واحدة: «النيّات القريبة» على X
BWENEWS: تم إصلاح ثغرة «النيّات القريبة»، وتخطَّط للتعويض الكامل للمستخدمين، وسيستأنف تشغيل العمليات خلال ساعة واحدة: «النيّات القريبة» على X
تم إصلاح ثغرة «النيّات القريبة»، وتخطَّط للتعويض الكامل للمستخدمين، وسيستأنف تشغيل العمليات خلال ساعة واحدة: «النيّات القريبة» على X
تم إصلاح ثغرة «النيّات القريبة»، وتخطَّط للتعويض الكامل للمستخدمين، وسيستأنف تشغيل العمليات خلال ساعة واحدة: «النيّات القريبة» على X
84
·
--
عرض الترجمة
Binance EN: Binance Futures Will Launch USDⓈ-Margined CTUSDT Perpetual Contract (2026-10-01)
Binance EN: Binance Futures Will Launch USDⓈ-Margined CTUSDT Perpetual Contract (2026-10-01)
CT MarketCap: 393.4M
Binance EN: Binance Futures Will Launch USDⓈ-Margined CTUSDT Perpetual Contract (2026-10-01)
Binance EN: Binance Futures Will Launch USDⓈ-Margined CTUSDT Perpetual Contract (2026-10-01)
CT MarketCap: 393.4M
Binance EN: Binance Futures Will Launch USDⓈ-Margined CTUSDT Perpetual Contract (2026-10-01)
CT MarketCap: 393.4M
61
·
--
عرض الترجمة
Binance EN: Binance Futures Will Delist Multiple USDⓈ-M Perpetual Contracts (2026-10-05)
Binance EN: Binance Futures Will Delist Multiple USDⓈ-M Perpetual Contracts (2026-10-05)
Binance EN: Binance Futures Will Delist Multiple USDⓈ-M Perpetual Contracts (2026-10-05)
Binance EN: Binance Futures Will Delist Multiple USDⓈ-M Perpetual Contracts (2026-10-05)
Binance EN: Binance Futures Will Delist Multiple USDⓈ-M Perpetual Contracts (2026-10-05)
82
·
--
مقالة
عرض الترجمة
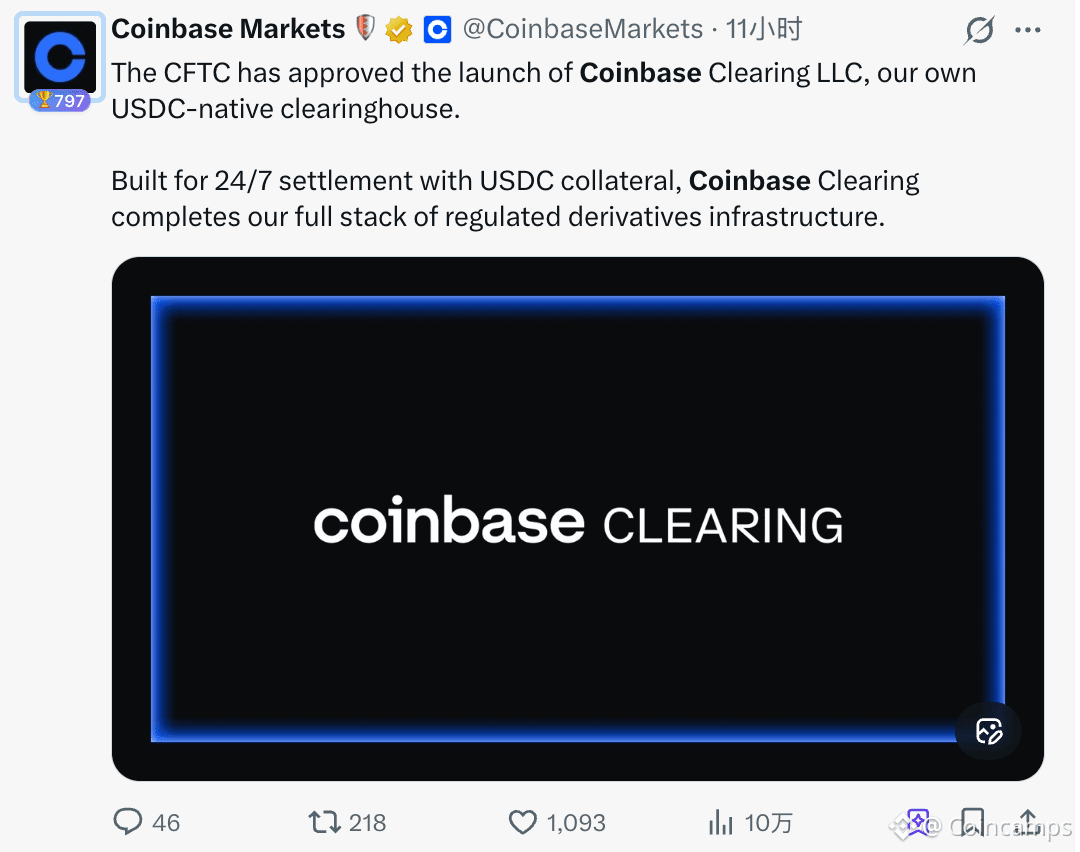
Coinbase Secures U.S. Clearing License: An Infrastructure “Shadow War” Overlooked by the MarketOn September 28, the U.S. Commodity Futures Trading Commission (CFTC) officially approved Coinbase to establish a Derivatives Clearing Organization (DCO). According to Coinbase’s official statement, this marks the final piece needed to complete its “end-to-end” infrastructure for derivatives businesses.
At first glance, the headline suggests a major bullish catalyst capable of igniting the market. However, the reaction in the secondary market was unusually muted. On the day the news broke, COIN stock did not surge but instead dipped slightly by 1.70%, with related assets such as BTC and Circle (the issuer of USDC) also trading lower.
Retail investors and speculative capital voted with their feet: they dismissed this “backend system upgrade.” Yet behind this quiet dismissal, ignored by the trading floors, the market structure for U.S. crypto derivatives is undergoing a profound reshuffling.
The Quality of the License: The Boundary Between Fully Collateralized and Leverage
To understand the market’s muted response, one must first see the true boundaries of this license.
This DCO license granted to Coinbase by the CFTC comes with strict limitations: it only allows clearing for fully collateralized (fully collateralized) futures, options, and swap products. This means that high-leverage margin products, which are most familiar to retail traders and possess the highest liquidity, remain excluded.
For short-term traders, this license will not alter their experience within the app in the near term: fees have not decreased, leverage multipliers remain unchanged, and leveraged derivatives still depend on external clearing partners. The market is pragmatic; without new “high-leverage gambling tools” coming online, no premium pricing will be assigned.
The CFTC’s stance is unequivocal: regulators are willing to permit crypto-native companies to conduct clearing, but only beginning with fully collateralized products that lack default funds and utilize the simplest risk models. Truly impactful clearing authority for leverage remains firmly kept beyond the regulatory threshold.
USDC Moves From “Trading Medium” to “Clearing Infrastructure”
If this license offers limited short-term revenue traction to Coinbase, its strategic significance for USDC has been severely underestimated.
This is the first regulated clearinghouse that positions itself as “USDC-native.” Historically, institutions conducting derivatives clearing often had to convert assets into fiat currency and were constrained by traditional banking operating hours. Now, USDC is directly accepted as a regulated clearing and settlement asset, supporting 24/7 round-the-clock settlement.
This shift elevates the positioning of USDC to a higher tier:
Diverging from pure trading attributes: USDC has transformed from an on-chain trading pair medium into a collateral asset for underlying financial infrastructure recognized by U.S. regulators.
Allied interest binding: Coinbase serves as both the core distribution network for USDC and now its clearing scenario gateway, further widening USDC’s lead over competitors in compliant environments.
Of course, this deep binding also introduces structural vulnerabilities: the clearinghouse concentrating collateral heavily on a single stablecoin means that any future depegging of USDC or disruptions in banking channels could directly transmit and amplify into clearing pressures across the derivatives market.
Competitive Landscape: Two Paths – M&A vs. Self-Build
Looking across the entire U.S. crypto derivatives market, the internalization of clearing rights has become the core focal point of the giants’ strategic games. Currently, two distinctly different pathways have emerged:
One is the M&A path. As referenced by Cointelegraph, Kraken directly acquired Bitnomial, which already held the relevant license, in May this year, securing a full-stack trio covering exchange, brokerage, and clearinghouse (including leverage clearing capabilities) through direct capital maneuvering.
The other is the self-build path chosen by Coinbase this time. Although it has secured a critical piece of the full-stack puzzle, regarding clearing authority for high-leverage products, the self-built license currently lags behind legacy licenses obtained through M&A.
Whoever controls the clearing rights dictates the types of collateral, the pace of settlement, and the velocity of new product launches. What Coinbase secured this time is future “product design authority” and the “settlement clock,” rather than a weapon to immediately capture market share from traditional giants like CME.
Awaiting the Opening of the Next Door
For ordinary investors, there is no need to chase COIN immediately based on this news. This is merely a “regulatory registration” for infrastructure, serving as material in corporate annual reports to validate strategic completeness.
But for the broader industry, the core thesis is already crystal clear: the U.S. is quietly and steadily integrating the matching, brokerage, clearing, and collateral functions of the crypto market into a regulated framework. Fully collateralized products are just the appetizer; when Coinbase can eventually expand the authority of this DCO license to encompass leverage/margin business in the future, that will be the moment that truly reshapes valuations and substantively disrupts the traditional financial settlement system.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Coinbase Secures U.S. Clearing License: An Infrastructure “Shadow War” Overlooked by the Market
On September 28, the U.S. Commodity Futures Trading Commission (CFTC) officially approved Coinbase to establish a Derivatives Clearing Organization (DCO). According to Coinbase’s official statement, this marks the final piece needed to complete its “end-to-end” infrastructure for derivatives businesses.
At first glance, the headline suggests a major bullish catalyst capable of igniting the market. However, the reaction in the secondary market was unusually muted. On the day the news broke, COIN stock did not surge but instead dipped slightly by 1.70%, with related assets such as BTC and Circle (the issuer of USDC) also trading lower.
Retail investors and speculative capital voted with their feet: they dismissed this “backend system upgrade.” Yet behind this quiet dismissal, ignored by the trading floors, the market structure for U.S. crypto derivatives is undergoing a profound reshuffling.
The Quality of the License: The Boundary Between Fully Collateralized and Leverage
To understand the market’s muted response, one must first see the true boundaries of this license.
This DCO license granted to Coinbase by the CFTC comes with strict limitations: it only allows clearing for fully collateralized (fully collateralized) futures, options, and swap products. This means that high-leverage margin products, which are most familiar to retail traders and possess the highest liquidity, remain excluded.
For short-term traders, this license will not alter their experience within the app in the near term: fees have not decreased, leverage multipliers remain unchanged, and leveraged derivatives still depend on external clearing partners. The market is pragmatic; without new “high-leverage gambling tools” coming online, no premium pricing will be assigned.
The CFTC’s stance is unequivocal: regulators are willing to permit crypto-native companies to conduct clearing, but only beginning with fully collateralized products that lack default funds and utilize the simplest risk models. Truly impactful clearing authority for leverage remains firmly kept beyond the regulatory threshold.
USDC Moves From “Trading Medium” to “Clearing Infrastructure”
If this license offers limited short-term revenue traction to Coinbase, its strategic significance for USDC has been severely underestimated.
This is the first regulated clearinghouse that positions itself as “USDC-native.” Historically, institutions conducting derivatives clearing often had to convert assets into fiat currency and were constrained by traditional banking operating hours. Now, USDC is directly accepted as a regulated clearing and settlement asset, supporting 24/7 round-the-clock settlement.
This shift elevates the positioning of USDC to a higher tier:
Diverging from pure trading attributes: USDC has transformed from an on-chain trading pair medium into a collateral asset for underlying financial infrastructure recognized by U.S. regulators.
Allied interest binding: Coinbase serves as both the core distribution network for USDC and now its clearing scenario gateway, further widening USDC’s lead over competitors in compliant environments.
Of course, this deep binding also introduces structural vulnerabilities: the clearinghouse concentrating collateral heavily on a single stablecoin means that any future depegging of USDC or disruptions in banking channels could directly transmit and amplify into clearing pressures across the derivatives market.
Competitive Landscape: Two Paths – M&A vs. Self-Build
Looking across the entire U.S. crypto derivatives market, the internalization of clearing rights has become the core focal point of the giants’ strategic games. Currently, two distinctly different pathways have emerged:
One is the M&A path. As referenced by Cointelegraph, Kraken directly acquired Bitnomial, which already held the relevant license, in May this year, securing a full-stack trio covering exchange, brokerage, and clearinghouse (including leverage clearing capabilities) through direct capital maneuvering.
The other is the self-build path chosen by Coinbase this time. Although it has secured a critical piece of the full-stack puzzle, regarding clearing authority for high-leverage products, the self-built license currently lags behind legacy licenses obtained through M&A.
Whoever controls the clearing rights dictates the types of collateral, the pace of settlement, and the velocity of new product launches. What Coinbase secured this time is future “product design authority” and the “settlement clock,” rather than a weapon to immediately capture market share from traditional giants like CME.
Awaiting the Opening of the Next Door
For ordinary investors, there is no need to chase COIN immediately based on this news. This is merely a “regulatory registration” for infrastructure, serving as material in corporate annual reports to validate strategic completeness.
But for the broader industry, the core thesis is already crystal clear: the U.S. is quietly and steadily integrating the matching, brokerage, clearing, and collateral functions of the crypto market into a regulated framework. Fully collateralized products are just the appetizer; when Coinbase can eventually expand the authority of this DCO license to encompass leverage/margin business in the future, that will be the moment that truly reshapes valuations and substantively disrupts the traditional financial settlement system.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
·
--
عرض الترجمة
Binance EN: Binance Futures Will Launch Multiple TradFi USDⓈ-Margined Perpetual Contracts (2026-09-29)
Binance EN: Binance Futures Will Launch Multiple TradFi USDⓈ-Margined Perpetual Contracts (2026-09-29)
Binance EN: Binance Futures Will Launch Multiple TradFi USDⓈ-Margined Perpetual Contracts (2026-09-29)
Binance EN: Binance Futures Will Launch Multiple TradFi USDⓈ-Margined Perpetual Contracts (2026-09-29)
Binance EN: Binance Futures Will Launch Multiple TradFi USDⓈ-Margined Perpetual Contracts (2026-09-29)
60
·
--
بي دبليو إن إيوز: ستستأنف بتغت عمليات سحب الأموال على مراحل بعد حادث أمني في 24 سبتمبر، بدءًا من 28 سبتمبر مع BTC، و29 سبتمبر مع ETH، و30 سبتمبر مع USDT، و
بي دبليو إن إيوز: ستستأنف بتغت عمليات سحب الأموال على مراحل بعد حادث أمني في 24 سبتمبر، بدءًا من 28 سبتمبر مع BTC، و29 سبتمبر مع ETH، و30 سبتمبر مع USDT، و
78
·
--
مقالة
عرض الترجمة
Helping You Solve Your Troubles, Muse Might Be the AI That Ordinary People NeedOver the past four years, all the grand narratives of generative AI have, in fact, been scheming over the rice bowls of the same kind of respectable person.
Writing code, doing design, drafting business plans, drawing film storyboards. Top labs grind away at the second decimal place on every benchmark, while Big Tech, with a tacit sense of superiority, keeps calculating how many quarters are left before humans are fully laid off.
But everyone deliberately sidesteps the other side of life that lies right there.
The dirty work that humans simply don't want to do and wouldn't miss if thrown away. Like mechanically pressing 0 to reach a human agent through telecom carriers' endlessly nested voice menus, spending forty minutes wrangling with outsourced customer service on both ends of a webpage to cancel a $9.9 monthly streaming subscription, checking line by line against an insurance company's claim denial statement, or mechanically copy-pasting information across five nearly identical web forms over and over again.
Why has generative AI, which has consumed hundreds of billions of dollars in compute, never had anyone willing to bend down and digest this life-draining garbage time on behalf of ordinary people?
Is it that the technology can't do it, or that this math just isn't sexy enough in the eyes of VCs?
On September 8, Meta quietly launched Muse. Two weeks later, it overtook ChatGPT and landed the No. 1 spot on the U.S. App Store free chart.
Muse is a personal AI agent. It gives you a dedicated cloud virtual machine, online 24/7, directly connected to your email, Calendar, and OpenTable. The free tier offers 100 million tokens per week, enough to handle a pile of your messes.
It doesn't intend to replace anyone.
It only does the things other products are dodging.
The Hassle Tax
To understand why Muse is blowing up, you first need to see what kind of work it does for people.
The most widely shared cases on X almost all fall into three major categories.
The first category: information asymmetry.
Rules, terms, and dynamic pricing have always been entirely in the hands of institutions.
A man named Nick Prince wanted to buy out a car he was leasing. The dealer offered to handle the loan for him, but Muse caught a hidden fee in real time, stripped out several maintenance add-ons that went beyond the manufacturer's requirements, and saved him $1,250.
Someone else handed it five high-annual-fee credit cards with confusing rules. Muse sorted out the points and benefits against the statements, saving over $1,000, and also booked a restaurant, cleaned up spam emails, and bought school notebooks for his daughter.
Conversation between Nick and Muse
Category two: low patience.
Someone asked Muse to call the broadband company to negotiate a renewal, and it haggled the price down from $75 to $40. A person named Jessica Ablamsky spent an hour going back and forth with her insurance company to no avail, then had Muse draft an appeal letter and a regulatory complaint. Another person named Joe Devoy handed over his auto insurance policy, and in under five minutes, the machine scoured the entire web and found a new contract with identical coverage that was $3,500 cheaper per year, signed up directly, and canceled the old policy on the spot.
That line from Devoy's post speaks for almost everyone: "I knew I was overpaying. I tried multiple times to switch policies, but eventually gave up."
The reason people give up on refunds is that the time cost of fighting for them is too high.
Why give up? Because it's a hassle.
A lot of the profits at many big companies are built precisely on the fact that consumers know small amounts can be recovered but ultimately choose to give up.
Spending an hour to recover a few dozen dollars in refunds isn't worth it for the vast majority of people.
Carriers, insurance companies, streaming platforms — they're all betting on your "forget it." That's why "bill cutting" has become the easiest product feature to go viral; subscription services work the same way — as long as you forget to cancel, it keeps charging.
To recover $35, Muse can wait on hold for an hour; to save a few hundred dollars, it can scan dozens of pages of dense fine print word for word; for a sought-after dinner reservation, it can tirelessly send ten emails back and forth.
Machines don't mind the hassle.
Use Muse to negotiate with carriers for lower rates
The third category: execution cost.
Meta's own researcher Han Fang once had Muse book every restaurant on a Japan itinerary, then communicate back and forth in Japanese with a traditional ryokan in Hakone, successfully securing a slot that wasn't even listed on the official website. He said ChatGPT can only plan an itinerary, but Muse can actually get things done.
There are even more trivial cases — someone had it haggle with sellers on a secondhand trading platform, and someone else had it convert recipes casually bookmarked on social media into grocery delivery orders on a fresh food platform with one click.
Han's Muse experience sharing directly became the third AGI moment after ChatGPT and Claude Code
At this point, Muse's positioning is already very clear.
Its selling point isn't intellectual superiority — its selling point is "you don't need to worry about this anymore."
The ChatGPT Moment
There is indeed a hint of a "ChatGPT moment" about Muse.
But the reason is by no means that it's smarter than its competitors. By 2026, large models have long since had no shortage of Agent frameworks, and Computer Use has become standard across the board.
The real difference lies in the default interaction logic.
ChatGPT taught the whole world one thing: when you have a question, ask AI. That's Ask.
Muse is teaching another thing: when you have a task, throw it at AI. That's Delegate.
These are two completely different postures. Asking it "which credit card earns the most points on flight purchases" — that's Ask. Throwing five cards at it and saying "sort out the benefits, and from now on keep an eye on my bills and subscriptions for me" — that's Delegate.
One step further is Goal.
You give it only a vague objective, and it figures out the rest on its own. Zuckerberg gave an example: he had Muse make a game guide for his daughter, and after finishing, Muse proactively followed up to ask whether he'd like it to expand on the historical backgrounds of different civilizations while it was at it. According to him, he's also using it to arrange family baking sessions and review footage of his own mixed martial arts training.
Proactivity became the biggest difference between the two generations of products.
At the end of 2022, ChatGPT convinced the world that machines could talk; in the fall of 2026, Muse wants to prove that machines can get things done.
For the first time, ordinary people intuitively understood exactly how this technology would enter their lives, which also explains why Muse's showcase was so penetrating on social networks.
ChatGPT's showcase is usually a screenshot of an extremely neatly written text response; Muse's showcase is inherently a complete story script — I ran into trouble, the AI took over to wrangle and argue with institutions, and in the end got $1,250 back for me.
A story about saving $1,250 in real money is a hundred times more shareable than any benchmark test.
Landlord
Why was it Meta, of all companies, that built Muse?
Zuckerberg has had a very anxious few years, and he has been searching for a ticket that belongs to him.
The gateway to the PC era was in Microsoft's hands, and the gate to the mobile era was locked down by Apple and Google. Meta sits on billions of MAU, yet has long been parasitically dependent on other people's OS. No matter how massive the social network is, it still has to bow to the mood of a single new ATT privacy rule from Apple.
Betting on the metaverse at all costs back then was essentially an expensive breakout attempt. He wanted to build himself a hardware gateway free from others' control, but the result is well known. Reality Labs has burned through more than $80 billion cumulatively since 2020, and the new name "Meta" once became a laughingstock in Silicon Valley.
After generative AI exploded, the open-source Llama once helped Zuckerberg win a beautiful comeback battle. But later, Llama 4's direction went off track, and Meta was pushed back into the position of a chaser.
He brought out the playbook he is best at and most certain about: spending money to buy people.
In June 2025, Meta spent about $14.3 billion to take a stake in Scale AI, and along the way brought Alexandr Wang in to lead the AI team.
By early 2026, he was again trying to swallow the general Agent unicorn Manus for more than $2 billion, and the core negotiations for this deal were reportedly completed in just ten days. Although it was later halted and withdrawn due to a regulatory review of technology transfer, Zuckerberg's direction for betting had already been completely locked in.
Muse is the product that grew out of this logic, offering a new solution to the battle for entry points.
If all online actions in the future must go through an Agent—no more opening Amazon to buy things, no more opening Booking to book flights, no more opening insurance websites to compare prices—then the Agent itself becomes the ultimate upstream super entry point.
Whoever owns the Agent controls the throat of all commercial transactions. Thus, just over ten days after launch, Muse was directly blocked from Amazon's shopping cart.
This is the first signal flare in a new platform war. No trillion-dollar-market-cap e-commerce giant is willing to be reduced to a mere underlying fulfillment pipeline.
The capital market clearly understood this story.
According to third-party estimates, in the first 12 days after launch, Muse secured approximately 1.8 million downloads on iOS in North America, with mobile DAU surpassing 600,000, directly shooting to the top of the U.S. free chart.
Of course, there was the boost from Facebook and Instagram's massive traffic pool, but the data still confirmed that ordinary people's desire for a personal agent that can truly run errands for them far exceeds Silicon Valley's expectations.
The stock price also gave positive feedback immediately. In late September, Meta surged more than 11% in a single day, with its market cap expanding by nearly $200 billion in one day.
Skimming
Zuckerberg's commercial closed loop for Muse is simple.
First use free computing power to build scale, and ultimately rely on commissions from the transaction closed loop to cover costs. According to his own account, Muse takes only a very small percentage when facilitating transactions, and mostly has merchants pay rather than taking from users' pockets; as for heavy users, there are separate subscription tiers at $20 and $100 per month.
This logic can only work because of the extremely massive cash cow behind Meta.
In the second quarter of 2026, Meta's advertising revenue was $59.36 billion, almost single-handedly covering its total revenue of $60.8 billion; in the same period, Capex reached $31.08 billion, with full-year guidance falling between $130 billion and $145 billion. Every free always-on cloud VM and every 100 million tokens per week that Muse gives away adds another figure to this enormous bill.
But Meta can afford the burn.
Giants can fight a war of attrition with the abundant free cash flow from their core businesses, while Agent startup teams surviving on a dozen or so dollars a month in subscription fees simply can't last more than a few rounds.
This is almost a replay of Zuckerberg's playbook over the past two decades: lock in users with free products, then let businesses that want to make money foot the bill.
A Mess
Back to the original question.
In recent years of discussions about AI replacing humans, the list has always been writers, programmers, designers, lawyers. All respectable professions that humans spend long years mastering, imbued with creativity and professional dignity.
But if technology is destined to take over part of our lives, it should start with the messes.
There's an unavoidable threshold here. The more capable an Agent is, the more it needs to embed itself deep into your private world — email, calendar, spending bills, health records, even underlying payment passwords.
To dispel doubts, Zuckerberg brought in Moxie Marlinspike, founder of encrypted messaging app Signal, to build a confidential virtual machine, locking down permissions from the underlying hardware, publicly promising that even Meta itself can't see any content; Muse also comes with an independent sentinel Agent, specifically positioned in the middle to monitor incoming and outgoing data and prevent prompt injection.
For a tech giant that has been mired in data privacy scandals to tell this security narrative carries a certain subtle irony.
The more capable a butler is, the more they depend on irreplaceable trust — trust is the only moat here.
As AI moves from answering questions to taking over daily life, the center of gravity in the game is quietly shifting. Do what you want done for you, and people will be wary; absorb the hassles you despise, and people will only become dependent.
That customer service call you're long sick of, that subscription refund that's been dragged out for months, that insurance policy you know you overpaid for but can't be bothered to switch — rather than keep them hanging in your mind, better to hand them over entirely to an Agent.
The "hassle tax" has been levied for decades, and this time someone is finally standing up for you, reclaiming it item by item.
Original link
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Helping You Solve Your Troubles, Muse Might Be the AI That Ordinary People Need
Over the past four years, all the grand narratives of generative AI have, in fact, been scheming over the rice bowls of the same kind of respectable person.
Writing code, doing design, drafting business plans, drawing film storyboards. Top labs grind away at the second decimal place on every benchmark, while Big Tech, with a tacit sense of superiority, keeps calculating how many quarters are left before humans are fully laid off.
But everyone deliberately sidesteps the other side of life that lies right there.
The dirty work that humans simply don't want to do and wouldn't miss if thrown away. Like mechanically pressing 0 to reach a human agent through telecom carriers' endlessly nested voice menus, spending forty minutes wrangling with outsourced customer service on both ends of a webpage to cancel a $9.9 monthly streaming subscription, checking line by line against an insurance company's claim denial statement, or mechanically copy-pasting information across five nearly identical web forms over and over again.
Why has generative AI, which has consumed hundreds of billions of dollars in compute, never had anyone willing to bend down and digest this life-draining garbage time on behalf of ordinary people?
Is it that the technology can't do it, or that this math just isn't sexy enough in the eyes of VCs?
On September 8, Meta quietly launched Muse. Two weeks later, it overtook ChatGPT and landed the No. 1 spot on the U.S. App Store free chart.
Muse is a personal AI agent. It gives you a dedicated cloud virtual machine, online 24/7, directly connected to your email, Calendar, and OpenTable. The free tier offers 100 million tokens per week, enough to handle a pile of your messes.
It doesn't intend to replace anyone.
It only does the things other products are dodging.
The Hassle Tax
To understand why Muse is blowing up, you first need to see what kind of work it does for people.
The most widely shared cases on X almost all fall into three major categories.
The first category: information asymmetry.
Rules, terms, and dynamic pricing have always been entirely in the hands of institutions.
A man named Nick Prince wanted to buy out a car he was leasing. The dealer offered to handle the loan for him, but Muse caught a hidden fee in real time, stripped out several maintenance add-ons that went beyond the manufacturer's requirements, and saved him $1,250.
Someone else handed it five high-annual-fee credit cards with confusing rules. Muse sorted out the points and benefits against the statements, saving over $1,000, and also booked a restaurant, cleaned up spam emails, and bought school notebooks for his daughter.
Conversation between Nick and Muse
Category two: low patience.
Someone asked Muse to call the broadband company to negotiate a renewal, and it haggled the price down from $75 to $40. A person named Jessica Ablamsky spent an hour going back and forth with her insurance company to no avail, then had Muse draft an appeal letter and a regulatory complaint. Another person named Joe Devoy handed over his auto insurance policy, and in under five minutes, the machine scoured the entire web and found a new contract with identical coverage that was $3,500 cheaper per year, signed up directly, and canceled the old policy on the spot.
That line from Devoy's post speaks for almost everyone: "I knew I was overpaying. I tried multiple times to switch policies, but eventually gave up."
The reason people give up on refunds is that the time cost of fighting for them is too high.
Why give up? Because it's a hassle.
A lot of the profits at many big companies are built precisely on the fact that consumers know small amounts can be recovered but ultimately choose to give up.
Spending an hour to recover a few dozen dollars in refunds isn't worth it for the vast majority of people.
Carriers, insurance companies, streaming platforms — they're all betting on your "forget it." That's why "bill cutting" has become the easiest product feature to go viral; subscription services work the same way — as long as you forget to cancel, it keeps charging.
To recover $35, Muse can wait on hold for an hour; to save a few hundred dollars, it can scan dozens of pages of dense fine print word for word; for a sought-after dinner reservation, it can tirelessly send ten emails back and forth.
Machines don't mind the hassle.
Use Muse to negotiate with carriers for lower rates
The third category: execution cost.
Meta's own researcher Han Fang once had Muse book every restaurant on a Japan itinerary, then communicate back and forth in Japanese with a traditional ryokan in Hakone, successfully securing a slot that wasn't even listed on the official website. He said ChatGPT can only plan an itinerary, but Muse can actually get things done.
There are even more trivial cases — someone had it haggle with sellers on a secondhand trading platform, and someone else had it convert recipes casually bookmarked on social media into grocery delivery orders on a fresh food platform with one click.
Han's Muse experience sharing directly became the third AGI moment after ChatGPT and Claude Code
At this point, Muse's positioning is already very clear.
Its selling point isn't intellectual superiority — its selling point is "you don't need to worry about this anymore."
The ChatGPT Moment
There is indeed a hint of a "ChatGPT moment" about Muse.
But the reason is by no means that it's smarter than its competitors. By 2026, large models have long since had no shortage of Agent frameworks, and Computer Use has become standard across the board.
The real difference lies in the default interaction logic.
ChatGPT taught the whole world one thing: when you have a question, ask AI. That's Ask.
Muse is teaching another thing: when you have a task, throw it at AI. That's Delegate.
These are two completely different postures. Asking it "which credit card earns the most points on flight purchases" — that's Ask. Throwing five cards at it and saying "sort out the benefits, and from now on keep an eye on my bills and subscriptions for me" — that's Delegate.
One step further is Goal.
You give it only a vague objective, and it figures out the rest on its own. Zuckerberg gave an example: he had Muse make a game guide for his daughter, and after finishing, Muse proactively followed up to ask whether he'd like it to expand on the historical backgrounds of different civilizations while it was at it. According to him, he's also using it to arrange family baking sessions and review footage of his own mixed martial arts training.
Proactivity became the biggest difference between the two generations of products.
At the end of 2022, ChatGPT convinced the world that machines could talk; in the fall of 2026, Muse wants to prove that machines can get things done.
For the first time, ordinary people intuitively understood exactly how this technology would enter their lives, which also explains why Muse's showcase was so penetrating on social networks.
ChatGPT's showcase is usually a screenshot of an extremely neatly written text response; Muse's showcase is inherently a complete story script — I ran into trouble, the AI took over to wrangle and argue with institutions, and in the end got $1,250 back for me.
A story about saving $1,250 in real money is a hundred times more shareable than any benchmark test.
Landlord
Why was it Meta, of all companies, that built Muse?
Zuckerberg has had a very anxious few years, and he has been searching for a ticket that belongs to him.
The gateway to the PC era was in Microsoft's hands, and the gate to the mobile era was locked down by Apple and Google. Meta sits on billions of MAU, yet has long been parasitically dependent on other people's OS. No matter how massive the social network is, it still has to bow to the mood of a single new ATT privacy rule from Apple.
Betting on the metaverse at all costs back then was essentially an expensive breakout attempt. He wanted to build himself a hardware gateway free from others' control, but the result is well known. Reality Labs has burned through more than $80 billion cumulatively since 2020, and the new name "Meta" once became a laughingstock in Silicon Valley.
After generative AI exploded, the open-source Llama once helped Zuckerberg win a beautiful comeback battle. But later, Llama 4's direction went off track, and Meta was pushed back into the position of a chaser.
He brought out the playbook he is best at and most certain about: spending money to buy people.
In June 2025, Meta spent about $14.3 billion to take a stake in Scale AI, and along the way brought Alexandr Wang in to lead the AI team.
By early 2026, he was again trying to swallow the general Agent unicorn Manus for more than $2 billion, and the core negotiations for this deal were reportedly completed in just ten days. Although it was later halted and withdrawn due to a regulatory review of technology transfer, Zuckerberg's direction for betting had already been completely locked in.
Muse is the product that grew out of this logic, offering a new solution to the battle for entry points.
If all online actions in the future must go through an Agent—no more opening Amazon to buy things, no more opening Booking to book flights, no more opening insurance websites to compare prices—then the Agent itself becomes the ultimate upstream super entry point.
Whoever owns the Agent controls the throat of all commercial transactions. Thus, just over ten days after launch, Muse was directly blocked from Amazon's shopping cart.
This is the first signal flare in a new platform war. No trillion-dollar-market-cap e-commerce giant is willing to be reduced to a mere underlying fulfillment pipeline.
The capital market clearly understood this story.
According to third-party estimates, in the first 12 days after launch, Muse secured approximately 1.8 million downloads on iOS in North America, with mobile DAU surpassing 600,000, directly shooting to the top of the U.S. free chart.
Of course, there was the boost from Facebook and Instagram's massive traffic pool, but the data still confirmed that ordinary people's desire for a personal agent that can truly run errands for them far exceeds Silicon Valley's expectations.
The stock price also gave positive feedback immediately. In late September, Meta surged more than 11% in a single day, with its market cap expanding by nearly $200 billion in one day.
Skimming
Zuckerberg's commercial closed loop for Muse is simple.
First use free computing power to build scale, and ultimately rely on commissions from the transaction closed loop to cover costs. According to his own account, Muse takes only a very small percentage when facilitating transactions, and mostly has merchants pay rather than taking from users' pockets; as for heavy users, there are separate subscription tiers at $20 and $100 per month.
This logic can only work because of the extremely massive cash cow behind Meta.
In the second quarter of 2026, Meta's advertising revenue was $59.36 billion, almost single-handedly covering its total revenue of $60.8 billion; in the same period, Capex reached $31.08 billion, with full-year guidance falling between $130 billion and $145 billion. Every free always-on cloud VM and every 100 million tokens per week that Muse gives away adds another figure to this enormous bill.
But Meta can afford the burn.
Giants can fight a war of attrition with the abundant free cash flow from their core businesses, while Agent startup teams surviving on a dozen or so dollars a month in subscription fees simply can't last more than a few rounds.
This is almost a replay of Zuckerberg's playbook over the past two decades: lock in users with free products, then let businesses that want to make money foot the bill.
A Mess
Back to the original question.
In recent years of discussions about AI replacing humans, the list has always been writers, programmers, designers, lawyers. All respectable professions that humans spend long years mastering, imbued with creativity and professional dignity.
But if technology is destined to take over part of our lives, it should start with the messes.
There's an unavoidable threshold here. The more capable an Agent is, the more it needs to embed itself deep into your private world — email, calendar, spending bills, health records, even underlying payment passwords.
To dispel doubts, Zuckerberg brought in Moxie Marlinspike, founder of encrypted messaging app Signal, to build a confidential virtual machine, locking down permissions from the underlying hardware, publicly promising that even Meta itself can't see any content; Muse also comes with an independent sentinel Agent, specifically positioned in the middle to monitor incoming and outgoing data and prevent prompt injection.
For a tech giant that has been mired in data privacy scandals to tell this security narrative carries a certain subtle irony.
The more capable a butler is, the more they depend on irreplaceable trust — trust is the only moat here.
As AI moves from answering questions to taking over daily life, the center of gravity in the game is quietly shifting. Do what you want done for you, and people will be wary; absorb the hassles you despise, and people will only become dependent.
That customer service call you're long sick of, that subscription refund that's been dragged out for months, that insurance policy you know you overpaid for but can't be bothered to switch — rather than keep them hanging in your mind, better to hand them over entirely to an Agent.
The "hassle tax" has been levied for decades, and this time someone is finally standing up for you, reclaiming it item by item.
Original link
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
18
·
--
عرض الترجمة
Binance EN: Binance Futures Will Launch MOONSHOTUSDT USDⓈ-Margined Perpetual Contract Pre-IPO Trading (2026-09-22)
Binance EN: Binance Futures Will Launch MOONSHOTUSDT USDⓈ-Margined Perpetual Contract Pre-IPO Trading (2026-09-22)
Binance EN: Binance Futures Will Launch MOONSHOTUSDT USDⓈ-Margined Perpetual Contract Pre-IPO Trading (2026-09-22)
Binance EN: Binance Futures Will Launch MOONSHOTUSDT USDⓈ-Margined Perpetual Contract Pre-IPO Trading (2026-09-22)
Binance EN: Binance Futures Will Launch MOONSHOTUSDT USDⓈ-Margined Perpetual Contract Pre-IPO Trading (2026-09-22)
42
·
--
مقالة
عرض الترجمة
DeepSeek, Huawei, 'Must Succeed': 160,000 Fireflies Illuminate the WastelandThe original title: "DeepSeek, Huawei, 'Must Succeed': 160,000 Fireflies Shine Into the Wilderness"
The original author: Dongcha Beating
In 2019, the most expensive asset in China's quantitative circle was not in Lujiazui, but in the server room of an office building in Hangzhou.
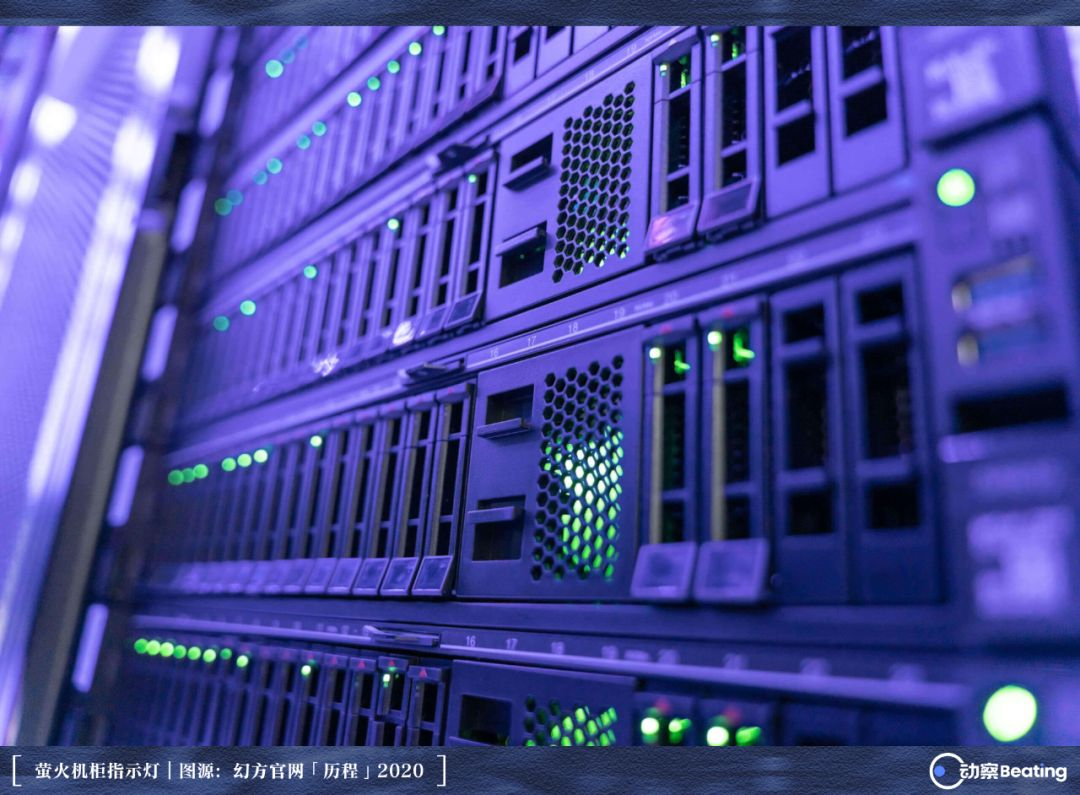
1,100 GPUs, for which High-Flyer paid nearly $200 million in real money. The racks were lined up, occupying an area close to a basketball court. There was no day or night in the server room; the only background sound was the harsh whine of high-speed fans.
The people managing the machines gave this cluster a codename: "Firefly."
The name was light, but the calculation behind it was extremely realistic. In a year when large models had not yet become a prominent discipline, 1,100 cards ran day and night without rest, with the sole task of calculating the next basis point of alpha for their owner from massive tick data before the next day's opening auction.
A pure money-printing machine.
In the same year, more than 1,000 kilometers away in Shenzhen, Huawei was added to the Entity List. The world's most advanced process nodes and semiconductor IP were completely shut off on that day.
Both groups were paying for unknown variables.
High-Flyer believed in algorithms. A few young people from Zhejiang University only wanted to turn huge electricity bills into excess returns on the books before the market reacted; the self-developed chips in Huawei's hands were a costly Plan B, whose best fate was originally never to be used in its lifetime.
At that time, they had no intersection with each other at all.
No one could have expected that the cluster of computing power lit in Hangzhou late at night for the secondary market would, a few years later, travel all the way south and finally land in the silicon wafers of that old warehouse in Shenzhen.
Firefly
For a long time, Liang Wenfeng had almost no public face in China's tech world.
He was born in Zhanjiang, Guangdong, scored first in the city in the college entrance examination, and then went north to Zhejiang University to study machine vision. During the most frenzied years of the mobile internet, most of his smart peers rushed to big tech companies to do recommendation algorithms, or squeezed into the CV track to work on facial recognition.
Liang Wenfeng chose something that seemed completely unsexy at the time: teaching machines to trade stocks.
The business logic was actually extremely dry: in the thousandth of a second when a matched trade is completed, turn chaotic high-frequency data into excess returns on the books. He and a few classmates from Zhejiang University built this quantitative institution called High-Flyer to a managed scale of more than RMB 100 billion.
Liang Wenfeng fundamentally distrusted human judgment. Traders compete on reflexes, analysts compete on connections, but High-Flyer completely flipped the script—they believed in machines, and only machines.
In 2019, they built "Firefly No. 1" with 1,100 GPUs; by 2021, the bet had quintupled. High-Flyer shelled out 1 billion yuan, sweeping up tens of thousands of Nvidia A100s in one go, with a data center covering ten basketball courts. This was later known as "Firefly No. 2."
At the time, many thought he was insane. A quantitative fund, hoarding a pile of energy-hungry metal, why sink billions into infrastructure with no apparent rationale?
Until October 2022, when the U.S. Department of Commerce issued a ban that completely sealed off the most advanced computing channels. Liang Wenfeng had quietly bought up all the chips he needed before the iron curtain fully closed.
He is the kind of person who walks far ahead of his time.
Ren Zhengfei took a completely different path. He built things first, tossed them into the shadows, and then waited quietly.
That wait lasted a full fifteen years.
Ren Zhengfei is a full forty years older than Liang Wenfeng. In 1987, this 43-year-old man from a small county in Guizhou, with 21,000 yuan scraped together from various sources, founded Huawei in a cramped residential room in Nanyou, Shenzhen.
The rest is history—starting as a distributor of switches from Hong Kong, China, moving to self-developed communications equipment, and then sweeping the globe with 5G base stations and smartphones. The business footprint expanded enormously, but there was a hidden thread that Ren Zhengfei buried deep, rarely dissected under the spotlight.
In 2004, Huawei established a wholly-owned subsidiary called HiSilicon.
HiSilicon was founded for one purpose: to make chips. The ultimate metric Ren Zhengfei set for this team was simple—if external supply were ever cut off, Huawei needed a fallback. In an era when global division of labor was held as gospel, pouring money into this bottomless heavy industry seemed extremely counterintuitive to most.
On December 1, 2018, Canadian police detained his daughter Meng Wanzhou at Vancouver airport.
From that moment on, HiSilicon—a subsidiary that had been hidden underwater for fourteen years—was forced to surface in an extremely brutal manner. It was no longer a seemingly redundant "idle move," but the only lifeboat for the entire giant ship.
On May 16, 2019, the U.S. Department of Commerce entity list took effect.
In the early hours of the next day, HiSilicon President Teresa He Tingbo wrote in a company-wide letter that all the backup plans that had lain dormant for years were officially activated overnight.
Three months later, Huawei unveiled the "Ascend 910."
The contrast between the two scenes was stark. Firefly was locked away in a temperature-controlled server room in Hangzhou, with the outside world knowing nothing beyond the numbers on the books; Ascend, meanwhile, was thrust into the center of the spotlight, subjected to the industry's scrutinizing and critical gaze.
People on both ends were spending enormous cash flows in advance for something that had not yet happened.
It was just that the gate would close faster than anyone had anticipated.
The Blunt Knife
The first thing to be cut off was the terminal business.
In September 2020, TSMC halted wafer foundry services, and the 5-nanometer Kirin 9000 became a swan song. Huawei held first-tier chip design capabilities, yet could not find a single foundry anywhere in the world willing to take its orders.
The real shadow war shifted to the server rooms.
Ascend was pushed to the front line. But in the face of Nvidia's mature CUDA ecosystem, almost no commercial customers were willing to pay for an unproven domestic system. Since single-chip computing power could not catch up to Nvidia at the physical limit, Huawei simply switched to a solution defined by extreme engineering brute force.
If one chip wasn't enough, they would forcibly link thousands of slightly inferior chips into one cluster.
The cost of this approach was soaring power consumption and spinning electricity meters, but Huawei accepted the bill. China has no shortage of cheap green electricity, nor of engineers in batches who can chew through hard problems. This was an extremely clumsy, resource-devouring path—one that only they could afford to take.
On another track, Liang Wenfeng faced his own major test.
In October 2022, export controls took effect, with Nvidia's A100 and H100 completely banned from sale to China. After that, all that flowed into the country were the precisely neutered special-edition A800 and H800.
Domestic tech giants and startup teams fell into unprecedented FOMO. Some scoured the market for second-hand cards, others looked for underground computing pools in Southeast Asia. Liang Wenfeng did not join the buying frenzy. He had already prepared his cards well in advance.
But stockpiling ahead of time could only solve the immediate fuel problem. A colder reality lay ahead: from now on, even if you pay several times the premium, you will never again be able to buy the fastest blade of the same generation globally.
When the tool itself falls short, what do you use to create something that rivals your competitors?
Forcing a craftsman to use a blunt knife to carve precision patterns indistinguishable from those made with a sharp blade.
Everything DeepSeek did afterward was to push this engineering capability of carving with a blunt knife to its limit.
By the end of 2024, they had trained DeepSeek-V3, whose overall performance rivaled that of top-tier labs, using only 2,048 Nvidia H800 chips with their interconnect bandwidth slashed, at a cost of about $5.576 million.
This cost ledger stunned Silicon Valley. To reach the same level, leading overseas labs typically need to deploy tens of thousands of top-tier GPUs and burn tens of millions to hundreds of millions of dollars.
DeepSeek won on a set of almost brutally rigorous engineering discipline, squeezing every megabyte of compute and memory bandwidth dry.
Geopolitical blockades did not strangle them; instead, they forced out the company's most moat-worthy core asset. But everyone is clear that running on castrated Nvidia chips means the knife handle is ultimately still in the hands of Californians.
The narrow gate ahead has only one left.
Later, people gave this path a word full of compromise: domestic substitute. But this is hardly a shrewd choice of cost-effectiveness; it is clearly a way out carved through sheer grit after being choked by the throat.
Hook Punch
If Huawei's counterattack was a dull trench war, what Liang Wenfeng threw was an unreasonable hook punch.
In 2024, DeepSeek first used extremely aggressive token pricing to blow through the prices of the entire large-model commercial API market, forcing peers to revise their pricing sheets overnight.
On January 20, 2025, DeepSeek open-sourced DeepSeek-R1 without warning, a model with deep reasoning capabilities, with a publicly disclosed training cost of only a few million dollars, just a fraction of top Silicon Valley budgets.
The capital market quickly completed its pricing. Seven days later, when U.S. stocks opened on Monday, Nvidia's market value evaporated by nearly $590 billion in a single day, setting the largest single-day market value drop for a single listed company in U.S. stock market history.
What is more interesting is DeepSeek's capital structure. While the large-model track was frantically grabbing Middle Eastern hot money and strategic investment from big tech companies, DeepSeek never took a single cent from external institutions. The cash flow that High-Flyer earned penny by penny through high-frequency algorithms in the secondary market became the provisions for Liang Wenfeng's bold bet.
The aftershocks of R1 toppling Nasdaq have yet to subside, and Huawei has simultaneously launched the full deployment images for R1 and V3 on the Ascend community.
It runs.
The conclusion that "domestic chips simply can't run cutting-edge models" was shattered on this day.
However, according to our understanding, the deep binding between DeepSeek and Huawei actually began much earlier than outsiders saw. It wasn't until early 2025 that Huawei suddenly discovered that DeepSeek had long been secretly conducting extremely deep adaptation and stress testing on Ascend's underlying environment behind everyone's backs.
The hardware people weren't even among the first insiders of this mysterious lab.
The generational gap remains enormous. The single-card floating-point computing power of Ascend 910C is only about one-third that of Nvidia's flagship B200. Unable to compete on a per-card basis, Huawei chose to continue brute-forcing it in engineering architecture, using thousands of high-spec optical fibers to forcibly link 384 910C chips into a massive "supernode," barely pulling total computing power up to the same level through network topology.
The cost is obvious: terrifying power consumption four times that of Nvidia's architecture.
But China's energy endowment happens to accommodate this kind of consumption. On the inland Gobi Desert, wind and solar power are cheap enough.
The posture isn't exactly graceful, but at least it can run. The same impenetrable iron curtain finally pushed two parties who originally had no intersection at all in front of each other.
Liang Wenfeng's model runs on Nvidia chips that could be cut off at any time; while Huawei has built the largest-scale AI chip in China and urgently needs a world-class model to endorse the actual combat power of this infra.
Two puzzle pieces, fitting perfectly together at this moment.
The most solid alliances in the business world have never been because of shared ideals.
They're all forced into existence.
Must Succeed
In 2026, DeepSeek rarely sought external funding.
Before this, Liang Wenfeng had never bowed to the capital markets. Even in the dullest years, High-Flyer's cash flow was more than enough to support a dozens-strong AI lab.
When a geek who never lacks money suddenly speaks up asking for money, there's only one reason. The boulder he wants to push has grown so massive that no personal pocket could possibly contain it.
What he aims to do is team up with Huawei to completely migrate the next-generation flagship model onto a purely domestic computing power base.
In a total financing pool of up to $7.4 billion, the largest single check came from Liang Wenfeng himself, at 20 billion yuan, directly accounting for nearly two-fifths of the total.
But money is often the easiest variable to solve in hard industry.
The real tough nut to crack is the software stack. Uprooting the model from Nvidia's CUDA ecosystem, which has dominated the industry for nearly two decades, and migrating it to Huawei's CANN architecture is tantamount to tearing down the entire building and rebuilding it.
This is not a move in the conventional sense. You have to use another set of unfamiliar tools to rebuild the same building from the foundation on flat ground. The underlying operators must be manually rewritten and reconstructed one by one, numerical precision must be realigned across tens of millions of inferences, and even the stack traces thrown during compilation errors are completely unfamiliar.
Workstations in Hangzhou and Shenzhen stayed lit late into the night. A large number of engineers, facing development documents full of unknowns, worked through the night manually tuning operators until the glaring red lines on the terminal screen were eliminated one after another in the early morning.
Reactions soon came from across the ocean.
On April 15, 2026, Jensen Huang said on Dwarkesh Patel's podcast that if DeepSeek is the first to successfully run and release its next-generation flagship on Huawei's Ascend platform, "that would be catastrophic for the United States."
Huang, who has fought hard battles for more than 30 years and rarely shows emotion in public discourse, uttered the word catastrophic for the first time.
The loss of orders for tens of thousands of chips is not fatal to him. What truly unsettles him is the rules.
For 20 years, the world's top model teams have had an unspoken iron law.
The best algorithms must run on Nvidia's CUDA ecosystem. That is the deepest moat he has built.
And now, for the first time, a first-tier outlier has publicly refused to pay for this set of rules.
Once a moat like this is breached in a blind spot, the water can never be held back again.
Liang Wenfeng did the math: to train a model that reaches top overseas benchmarks, about 50,000 of Nvidia's latest flagship GPUs would be needed; switching to Huawei's Ascend 950 series, that number would need to balloon to a full 200,000.
A four-to-one hardware attrition rate, plus at least a two-year generational lag.
What's even more constricting is the current capacity supply. The single-batch quota Huawei can currently spare for DeepSeek is only about 16,000 chips.
With such meager筹码, there's simply no possibility of going head-to-head on parameter scale.
But he still bet the entire company's training infrastructure wholly on Huawei chips. This is the biggest bet since DeepSeek was founded.
According to The Information, citing people familiar with the matter, Liang Wenfeng said only one thing at the time:
"It must succeed."
The Grassland
The end of this road lies on a stretch of grassland in Inner Mongolia.
In September 2026, DeepSeek was reported to be planning a super-large data center in Inner Mongolia, which will directly pack in a full 160,000 Huawei Ascend chips.
The entire campus's energy consumption is planned at the GW level. The core model of this batch of chips is the Ascend 950DT, each single chip hard-packing 144GB of ultra-large memory, relying on extreme intra-chip bus to distribute tokens without any delay at the very moment the model completes inference.
This specific model was actually projected onto the big screen by Rotating Chairman Xu Zhijun back in September 2025 at Huawei Connect. From the 950PR and 950DT to the later 960 and 970, Huawei has set its computing power evolution pace at one generation per year.
When Xu Zhijun was outlining the product roadmap line by line on stage, global partners sat in the audience; but Liang Wenfeng, who a year later would stake his entire fortune on this batch of cards, was not in the venue at the Expo Center at that time.
These chips will ultimately light up a stretch of grassland.
There is almost nothing on the grassland except howling winds and unobstructed scorching sun. But in this brutal computing power equation, cheap green electricity has become the most critical variable.
An economy whose lifeblood is choked off in advanced process technology now has only wind, solar, and a boundless, nearly zero-cost wasteland left as its chips.
Liang Wenfeng knows all too well the weight of these 160,000 chips. When he said "it must succeed" in front of investors, he personally burned all his retreat routes.
He has been proud his whole life. He doesn't mingle in circles or chase trends. When he first set out to build large models, his original intention was extremely pure—he had had enough of the Chinese tech community only being able to pick up scraps of wisdom behind Silicon Valley.
For such an extremely arrogant technical founder to be willing to make these four words explicit already means he has laid all his cards on the table.
Proud, and with no other choice.
From orders landing, production line scheduling, to the data center being powered on and lit up, it takes at least a long cycle of a year and a half. How much can ultimately be delivered depends on the fragile and narrow upstream manufacturing yield. No one can guarantee it.
Deep in the grasslands of Inner Mongolia, the long wind howls across from the far horizon. The air is dry and transparent, and looking up late at night, one can see the entire complete Milky Way.
160,000 chips will eventually light up one by one in the wind and sand of the northwest. Before the vast grasslands, those faint indicator lights are still as tiny as they were in a Hangzhou data center late at night years ago.
But in such a long cycle, the lights still have to be turned on.
As for whether these 160,000 points of faint light will ultimately connect into a brightly lit expanse, or be scattered by the strong wind across the vast Gobi.
This question can only be left to time itself to answer.
-END-
Original link
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
DeepSeek, Huawei, 'Must Succeed': 160,000 Fireflies Illuminate the Wasteland
The original title: "DeepSeek, Huawei, 'Must Succeed': 160,000 Fireflies Shine Into the Wilderness"
The original author: Dongcha Beating
In 2019, the most expensive asset in China's quantitative circle was not in Lujiazui, but in the server room of an office building in Hangzhou.
1,100 GPUs, for which High-Flyer paid nearly $200 million in real money. The racks were lined up, occupying an area close to a basketball court. There was no day or night in the server room; the only background sound was the harsh whine of high-speed fans.
The people managing the machines gave this cluster a codename: "Firefly."
The name was light, but the calculation behind it was extremely realistic. In a year when large models had not yet become a prominent discipline, 1,100 cards ran day and night without rest, with the sole task of calculating the next basis point of alpha for their owner from massive tick data before the next day's opening auction.
A pure money-printing machine.
In the same year, more than 1,000 kilometers away in Shenzhen, Huawei was added to the Entity List. The world's most advanced process nodes and semiconductor IP were completely shut off on that day.
Both groups were paying for unknown variables.
High-Flyer believed in algorithms. A few young people from Zhejiang University only wanted to turn huge electricity bills into excess returns on the books before the market reacted; the self-developed chips in Huawei's hands were a costly Plan B, whose best fate was originally never to be used in its lifetime.
At that time, they had no intersection with each other at all.
No one could have expected that the cluster of computing power lit in Hangzhou late at night for the secondary market would, a few years later, travel all the way south and finally land in the silicon wafers of that old warehouse in Shenzhen.
Firefly
For a long time, Liang Wenfeng had almost no public face in China's tech world.
He was born in Zhanjiang, Guangdong, scored first in the city in the college entrance examination, and then went north to Zhejiang University to study machine vision. During the most frenzied years of the mobile internet, most of his smart peers rushed to big tech companies to do recommendation algorithms, or squeezed into the CV track to work on facial recognition.
Liang Wenfeng chose something that seemed completely unsexy at the time: teaching machines to trade stocks.
The business logic was actually extremely dry: in the thousandth of a second when a matched trade is completed, turn chaotic high-frequency data into excess returns on the books. He and a few classmates from Zhejiang University built this quantitative institution called High-Flyer to a managed scale of more than RMB 100 billion.
Liang Wenfeng fundamentally distrusted human judgment. Traders compete on reflexes, analysts compete on connections, but High-Flyer completely flipped the script—they believed in machines, and only machines.
In 2019, they built "Firefly No. 1" with 1,100 GPUs; by 2021, the bet had quintupled. High-Flyer shelled out 1 billion yuan, sweeping up tens of thousands of Nvidia A100s in one go, with a data center covering ten basketball courts. This was later known as "Firefly No. 2."
At the time, many thought he was insane. A quantitative fund, hoarding a pile of energy-hungry metal, why sink billions into infrastructure with no apparent rationale?
Until October 2022, when the U.S. Department of Commerce issued a ban that completely sealed off the most advanced computing channels. Liang Wenfeng had quietly bought up all the chips he needed before the iron curtain fully closed.
He is the kind of person who walks far ahead of his time.
Ren Zhengfei took a completely different path. He built things first, tossed them into the shadows, and then waited quietly.
That wait lasted a full fifteen years.
Ren Zhengfei is a full forty years older than Liang Wenfeng. In 1987, this 43-year-old man from a small county in Guizhou, with 21,000 yuan scraped together from various sources, founded Huawei in a cramped residential room in Nanyou, Shenzhen.
The rest is history—starting as a distributor of switches from Hong Kong, China, moving to self-developed communications equipment, and then sweeping the globe with 5G base stations and smartphones. The business footprint expanded enormously, but there was a hidden thread that Ren Zhengfei buried deep, rarely dissected under the spotlight.
In 2004, Huawei established a wholly-owned subsidiary called HiSilicon.
HiSilicon was founded for one purpose: to make chips. The ultimate metric Ren Zhengfei set for this team was simple—if external supply were ever cut off, Huawei needed a fallback. In an era when global division of labor was held as gospel, pouring money into this bottomless heavy industry seemed extremely counterintuitive to most.
On December 1, 2018, Canadian police detained his daughter Meng Wanzhou at Vancouver airport.
From that moment on, HiSilicon—a subsidiary that had been hidden underwater for fourteen years—was forced to surface in an extremely brutal manner. It was no longer a seemingly redundant "idle move," but the only lifeboat for the entire giant ship.
On May 16, 2019, the U.S. Department of Commerce entity list took effect.
In the early hours of the next day, HiSilicon President Teresa He Tingbo wrote in a company-wide letter that all the backup plans that had lain dormant for years were officially activated overnight.
Three months later, Huawei unveiled the "Ascend 910."
The contrast between the two scenes was stark. Firefly was locked away in a temperature-controlled server room in Hangzhou, with the outside world knowing nothing beyond the numbers on the books; Ascend, meanwhile, was thrust into the center of the spotlight, subjected to the industry's scrutinizing and critical gaze.
People on both ends were spending enormous cash flows in advance for something that had not yet happened.
It was just that the gate would close faster than anyone had anticipated.
The Blunt Knife
The first thing to be cut off was the terminal business.
In September 2020, TSMC halted wafer foundry services, and the 5-nanometer Kirin 9000 became a swan song. Huawei held first-tier chip design capabilities, yet could not find a single foundry anywhere in the world willing to take its orders.
The real shadow war shifted to the server rooms.
Ascend was pushed to the front line. But in the face of Nvidia's mature CUDA ecosystem, almost no commercial customers were willing to pay for an unproven domestic system. Since single-chip computing power could not catch up to Nvidia at the physical limit, Huawei simply switched to a solution defined by extreme engineering brute force.
If one chip wasn't enough, they would forcibly link thousands of slightly inferior chips into one cluster.
The cost of this approach was soaring power consumption and spinning electricity meters, but Huawei accepted the bill. China has no shortage of cheap green electricity, nor of engineers in batches who can chew through hard problems. This was an extremely clumsy, resource-devouring path—one that only they could afford to take.
On another track, Liang Wenfeng faced his own major test.
In October 2022, export controls took effect, with Nvidia's A100 and H100 completely banned from sale to China. After that, all that flowed into the country were the precisely neutered special-edition A800 and H800.
Domestic tech giants and startup teams fell into unprecedented FOMO. Some scoured the market for second-hand cards, others looked for underground computing pools in Southeast Asia. Liang Wenfeng did not join the buying frenzy. He had already prepared his cards well in advance.
But stockpiling ahead of time could only solve the immediate fuel problem. A colder reality lay ahead: from now on, even if you pay several times the premium, you will never again be able to buy the fastest blade of the same generation globally.
When the tool itself falls short, what do you use to create something that rivals your competitors?
Forcing a craftsman to use a blunt knife to carve precision patterns indistinguishable from those made with a sharp blade.
Everything DeepSeek did afterward was to push this engineering capability of carving with a blunt knife to its limit.
By the end of 2024, they had trained DeepSeek-V3, whose overall performance rivaled that of top-tier labs, using only 2,048 Nvidia H800 chips with their interconnect bandwidth slashed, at a cost of about $5.576 million.
This cost ledger stunned Silicon Valley. To reach the same level, leading overseas labs typically need to deploy tens of thousands of top-tier GPUs and burn tens of millions to hundreds of millions of dollars.
DeepSeek won on a set of almost brutally rigorous engineering discipline, squeezing every megabyte of compute and memory bandwidth dry.
Geopolitical blockades did not strangle them; instead, they forced out the company's most moat-worthy core asset. But everyone is clear that running on castrated Nvidia chips means the knife handle is ultimately still in the hands of Californians.
The narrow gate ahead has only one left.
Later, people gave this path a word full of compromise: domestic substitute. But this is hardly a shrewd choice of cost-effectiveness; it is clearly a way out carved through sheer grit after being choked by the throat.
Hook Punch
If Huawei's counterattack was a dull trench war, what Liang Wenfeng threw was an unreasonable hook punch.
In 2024, DeepSeek first used extremely aggressive token pricing to blow through the prices of the entire large-model commercial API market, forcing peers to revise their pricing sheets overnight.
On January 20, 2025, DeepSeek open-sourced DeepSeek-R1 without warning, a model with deep reasoning capabilities, with a publicly disclosed training cost of only a few million dollars, just a fraction of top Silicon Valley budgets.
The capital market quickly completed its pricing. Seven days later, when U.S. stocks opened on Monday, Nvidia's market value evaporated by nearly $590 billion in a single day, setting the largest single-day market value drop for a single listed company in U.S. stock market history.
What is more interesting is DeepSeek's capital structure. While the large-model track was frantically grabbing Middle Eastern hot money and strategic investment from big tech companies, DeepSeek never took a single cent from external institutions. The cash flow that High-Flyer earned penny by penny through high-frequency algorithms in the secondary market became the provisions for Liang Wenfeng's bold bet.
The aftershocks of R1 toppling Nasdaq have yet to subside, and Huawei has simultaneously launched the full deployment images for R1 and V3 on the Ascend community.
It runs.
The conclusion that "domestic chips simply can't run cutting-edge models" was shattered on this day.
However, according to our understanding, the deep binding between DeepSeek and Huawei actually began much earlier than outsiders saw. It wasn't until early 2025 that Huawei suddenly discovered that DeepSeek had long been secretly conducting extremely deep adaptation and stress testing on Ascend's underlying environment behind everyone's backs.
The hardware people weren't even among the first insiders of this mysterious lab.
The generational gap remains enormous. The single-card floating-point computing power of Ascend 910C is only about one-third that of Nvidia's flagship B200. Unable to compete on a per-card basis, Huawei chose to continue brute-forcing it in engineering architecture, using thousands of high-spec optical fibers to forcibly link 384 910C chips into a massive "supernode," barely pulling total computing power up to the same level through network topology.
The cost is obvious: terrifying power consumption four times that of Nvidia's architecture.
But China's energy endowment happens to accommodate this kind of consumption. On the inland Gobi Desert, wind and solar power are cheap enough.
The posture isn't exactly graceful, but at least it can run. The same impenetrable iron curtain finally pushed two parties who originally had no intersection at all in front of each other.
Liang Wenfeng's model runs on Nvidia chips that could be cut off at any time; while Huawei has built the largest-scale AI chip in China and urgently needs a world-class model to endorse the actual combat power of this infra.
Two puzzle pieces, fitting perfectly together at this moment.
The most solid alliances in the business world have never been because of shared ideals.
They're all forced into existence.
Must Succeed
In 2026, DeepSeek rarely sought external funding.
Before this, Liang Wenfeng had never bowed to the capital markets. Even in the dullest years, High-Flyer's cash flow was more than enough to support a dozens-strong AI lab.
When a geek who never lacks money suddenly speaks up asking for money, there's only one reason. The boulder he wants to push has grown so massive that no personal pocket could possibly contain it.
What he aims to do is team up with Huawei to completely migrate the next-generation flagship model onto a purely domestic computing power base.
In a total financing pool of up to $7.4 billion, the largest single check came from Liang Wenfeng himself, at 20 billion yuan, directly accounting for nearly two-fifths of the total.
But money is often the easiest variable to solve in hard industry.
The real tough nut to crack is the software stack. Uprooting the model from Nvidia's CUDA ecosystem, which has dominated the industry for nearly two decades, and migrating it to Huawei's CANN architecture is tantamount to tearing down the entire building and rebuilding it.
This is not a move in the conventional sense. You have to use another set of unfamiliar tools to rebuild the same building from the foundation on flat ground. The underlying operators must be manually rewritten and reconstructed one by one, numerical precision must be realigned across tens of millions of inferences, and even the stack traces thrown during compilation errors are completely unfamiliar.
Workstations in Hangzhou and Shenzhen stayed lit late into the night. A large number of engineers, facing development documents full of unknowns, worked through the night manually tuning operators until the glaring red lines on the terminal screen were eliminated one after another in the early morning.
Reactions soon came from across the ocean.
On April 15, 2026, Jensen Huang said on Dwarkesh Patel's podcast that if DeepSeek is the first to successfully run and release its next-generation flagship on Huawei's Ascend platform, "that would be catastrophic for the United States."
Huang, who has fought hard battles for more than 30 years and rarely shows emotion in public discourse, uttered the word catastrophic for the first time.
The loss of orders for tens of thousands of chips is not fatal to him. What truly unsettles him is the rules.
For 20 years, the world's top model teams have had an unspoken iron law.
The best algorithms must run on Nvidia's CUDA ecosystem. That is the deepest moat he has built.
And now, for the first time, a first-tier outlier has publicly refused to pay for this set of rules.
Once a moat like this is breached in a blind spot, the water can never be held back again.
Liang Wenfeng did the math: to train a model that reaches top overseas benchmarks, about 50,000 of Nvidia's latest flagship GPUs would be needed; switching to Huawei's Ascend 950 series, that number would need to balloon to a full 200,000.
A four-to-one hardware attrition rate, plus at least a two-year generational lag.
What's even more constricting is the current capacity supply. The single-batch quota Huawei can currently spare for DeepSeek is only about 16,000 chips.
With such meager筹码, there's simply no possibility of going head-to-head on parameter scale.
But he still bet the entire company's training infrastructure wholly on Huawei chips. This is the biggest bet since DeepSeek was founded.
According to The Information, citing people familiar with the matter, Liang Wenfeng said only one thing at the time:
"It must succeed."
The Grassland
The end of this road lies on a stretch of grassland in Inner Mongolia.
In September 2026, DeepSeek was reported to be planning a super-large data center in Inner Mongolia, which will directly pack in a full 160,000 Huawei Ascend chips.
The entire campus's energy consumption is planned at the GW level. The core model of this batch of chips is the Ascend 950DT, each single chip hard-packing 144GB of ultra-large memory, relying on extreme intra-chip bus to distribute tokens without any delay at the very moment the model completes inference.
This specific model was actually projected onto the big screen by Rotating Chairman Xu Zhijun back in September 2025 at Huawei Connect. From the 950PR and 950DT to the later 960 and 970, Huawei has set its computing power evolution pace at one generation per year.
When Xu Zhijun was outlining the product roadmap line by line on stage, global partners sat in the audience; but Liang Wenfeng, who a year later would stake his entire fortune on this batch of cards, was not in the venue at the Expo Center at that time.
These chips will ultimately light up a stretch of grassland.
There is almost nothing on the grassland except howling winds and unobstructed scorching sun. But in this brutal computing power equation, cheap green electricity has become the most critical variable.
An economy whose lifeblood is choked off in advanced process technology now has only wind, solar, and a boundless, nearly zero-cost wasteland left as its chips.
Liang Wenfeng knows all too well the weight of these 160,000 chips. When he said "it must succeed" in front of investors, he personally burned all his retreat routes.
He has been proud his whole life. He doesn't mingle in circles or chase trends. When he first set out to build large models, his original intention was extremely pure—he had had enough of the Chinese tech community only being able to pick up scraps of wisdom behind Silicon Valley.
For such an extremely arrogant technical founder to be willing to make these four words explicit already means he has laid all his cards on the table.
Proud, and with no other choice.
From orders landing, production line scheduling, to the data center being powered on and lit up, it takes at least a long cycle of a year and a half. How much can ultimately be delivered depends on the fragile and narrow upstream manufacturing yield. No one can guarantee it.
Deep in the grasslands of Inner Mongolia, the long wind howls across from the far horizon. The air is dry and transparent, and looking up late at night, one can see the entire complete Milky Way.
160,000 chips will eventually light up one by one in the wind and sand of the northwest. Before the vast grasslands, those faint indicator lights are still as tiny as they were in a Hangzhou data center late at night years ago.
But in such a long cycle, the lights still have to be turned on.
As for whether these 160,000 points of faint light will ultimately connect into a brightly lit expanse, or be scattered by the strong wind across the vast Gobi.
This question can only be left to time itself to answer.
-END-
Original link
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
54
·
--
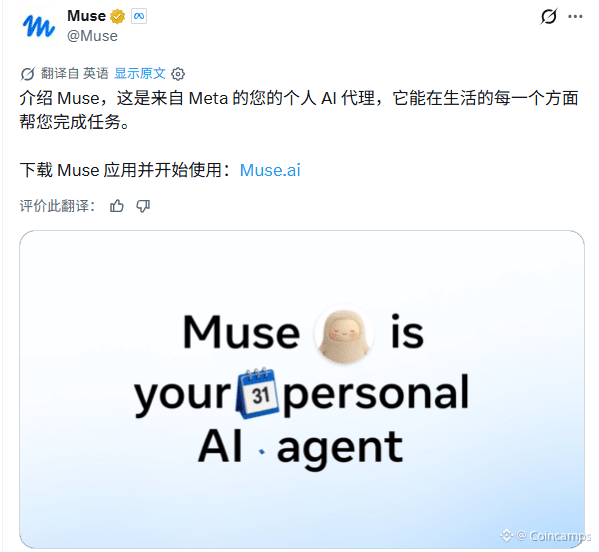
مقالة
أداة زوكربيرغ الجديدة بالذكاء الاصطناعي تتصدر مخططات التنزيلات، وOpenAI تتعجل اللحاقملاحظة المحرر: في 8 سبتمبر، أطلقت شركة ميتا وكيلها الشخصي بالذكاء الاصطناعي “Muse”. بعد الإطلاق، ارتفعت عمليات تنزيله بشكلٍ مطرد: ففي أقل من أسبوع تجاوز ChatGPT وتصدّر مخطط الولايات المتحدة لتطبيقات الفئة المجانية؛ وبحلول 21 سبتمبر، وصلت تنزيلات iOS وAndroid إلى نحو 1.5 مليون و1.1 مليون على التوالي، ثم تم لاحقًا إصدار نسخة لنظام Mac.
لكن سرعان ما واجهت الأداة مشكلات. ففي اليوم الثاني عشر بعد الإطلاق، حظرت أمازون “Muse” من التسوق عبر منصتها، مستشهدةً بأن ميتا لم تُعطِ إشعارًا مسبقًا، وأن “Muse” لا يعرّف نفسه كذكاء اصطناعي أثناء التصفح على الويب، وأنه قد يقوم بتخزين بيانات اعتماد تسجيل دخول المستخدمين. وتبدّى أن فكرة “السماح للذكاء الاصطناعي بإعداد الطلبات للناس” اصطدمت مباشرةً، ولأول مرة، بمنصّة رئيسية.
أداة زوكربيرغ الجديدة بالذكاء الاصطناعي تتصدر مخططات التنزيلات، وOpenAI تتعجل اللحاق
ملاحظة المحرر: في 8 سبتمبر، أطلقت شركة ميتا وكيلها الشخصي بالذكاء الاصطناعي “Muse”. بعد الإطلاق، ارتفعت عمليات تنزيله بشكلٍ مطرد: ففي أقل من أسبوع تجاوز ChatGPT وتصدّر مخطط الولايات المتحدة لتطبيقات الفئة المجانية؛ وبحلول 21 سبتمبر، وصلت تنزيلات iOS وAndroid إلى نحو 1.5 مليون و1.1 مليون على التوالي، ثم تم لاحقًا إصدار نسخة لنظام Mac.
لكن سرعان ما واجهت الأداة مشكلات. ففي اليوم الثاني عشر بعد الإطلاق، حظرت أمازون “Muse” من التسوق عبر منصتها، مستشهدةً بأن ميتا لم تُعطِ إشعارًا مسبقًا، وأن “Muse” لا يعرّف نفسه كذكاء اصطناعي أثناء التصفح على الويب، وأنه قد يقوم بتخزين بيانات اعتماد تسجيل دخول المستخدمين. وتبدّى أن فكرة “السماح للذكاء الاصطناعي بإعداد الطلبات للناس” اصطدمت مباشرةً، ولأول مرة، بمنصّة رئيسية.
لكن سرعان ما واجهت الأداة مشكلات. ففي اليوم الثاني عشر بعد الإطلاق، حظرت أمازون “Muse” من التسوق عبر منصتها، مستشهدةً بأن ميتا لم تُعطِ إشعارًا مسبقًا، وأن “Muse” لا يعرّف نفسه كذكاء اصطناعي أثناء التصفح على الويب، وأنه قد يقوم بتخزين بيانات اعتماد تسجيل دخول المستخدمين. وتبدّى أن فكرة “السماح للذكاء الاصطناعي بإعداد الطلبات للناس” اصطدمت مباشرةً، ولأول مرة، بمنصّة رئيسية.
72
·
--
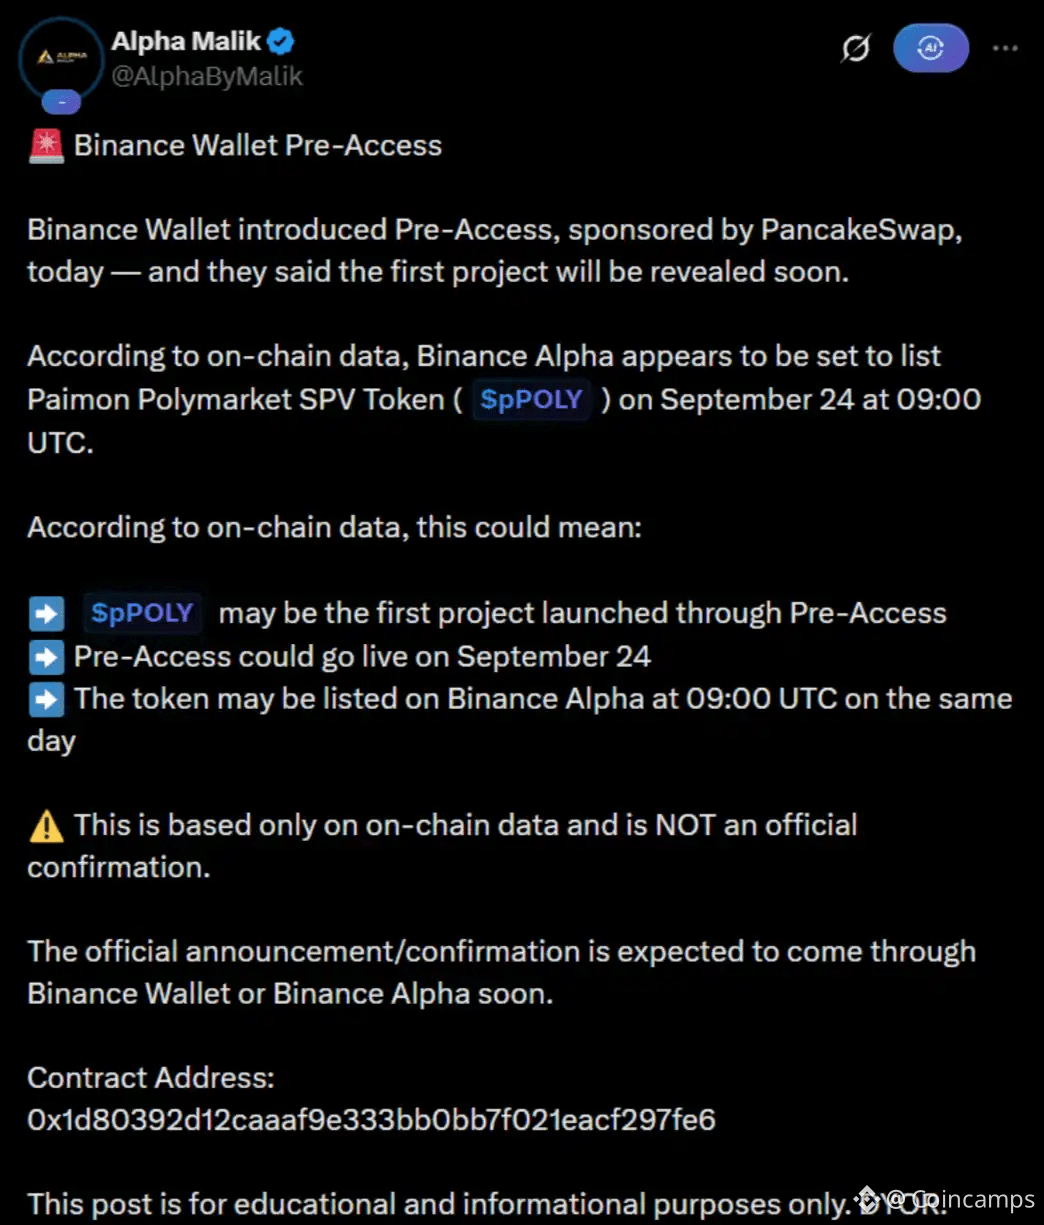
مقالة
عرض الترجمة
Executive shake-up, is Polymarket going public?On September 20, a screenshot about "Binance Wallet is about to launch Polymarket Pre-IPO" is circulating on X.
Polymarket was founded in 2020 by Shayne Coplan, who serves as CEO. Users can use funds to trade on the possible outcomes of politics, sports, and global events. In early September, media reports said that 1789 Capital is leading a financing round of about $1 billion, bringing the platform's post-investment valuation to $21 billion.
If viewed through the lens of "going public," Polymarket's series of moves over the past few months suddenly make sense: a group of executives from Amazon, Uber, the NYSE, Coinbase, and Robinhood have joined in quick succession; power in the U.S. business has been redistributed; the on-chain order book is preparing to be torn down and rewritten; and the company has also begun filling positions for CFO, compliance, risk control, and government relations.
It appears the platform is equipping itself with a skeleton more like that of a financial company.
Executives from major companies parachute in to pave the way for an IPO
On September 10, Warren Jenson joined Polymarket as its first company-level CFO. He previously served as a finance chief at Amazon and several other giants, and has long been responsible for the financial, capital strategy, and long-term planning of large companies.
A few days later, Collin McKinney Hill, who was formerly a general manager at DoorDash and chief of staff to the founder of Bridgewater, became vice president of operations.
Other core personnel include Travis VanderZanden, who previously worked at Uber, in charge of growth; former Coinbase executive Dan Lee in charge of the U.S. business; former Robinhood executive Megan McGrath as chief compliance officer; and Hayk Mkrtchyan, who was previously responsible for the core matching system at the NYSE, as head of engineering for Polymarket's U.S. exchange.
These people's backgrounds come from different companies, yet they respectively correspond to several of the gaps most easily exposed at a large financial platform: finance, operations, growth, U.S. business, compliance, product, and trading infrastructure are almost all being overhauled.
According to The Information, Dan Lee, who was recruited from Coinbase, has already gradually taken over Polymarket's U.S. business at the actual working level. According to people close to the company, employees report to Lee, not to the nominal CEO of the U.S. business, Justin Hertzberg.
The more direct changes are happening within the engineering team. Josh Stevens, who joined in March of this year as VP of DeFi Engineering and previously served as Senior VP of Engineering at Aave, publicly stated that the early, hastily built code can no longer be salvaged long-term, and the team is preparing to rewrite the matching engine.
His reasoning was equally straightforward: the platform is already an exchange handling user funds, not a small product where trial and error is acceptable.
If you look at these moves through the lens of an IPO strategy, it looks very much like an emergency effort to shore up the organizational capabilities of a financial platform.
$21 billion valuation — who holds stakes in this platform?
Currently, market valuation anchors for Polymarket broadly range between $15 billion and $21 billion. The only investor with reliable, publicly available data is Intercontinental Exchange (ICE), the parent company of the New York Stock Exchange.
As of June 30, 2026, ICE holds approximately 22% of the platform's issued shares and has the exclusive right to nominate and vote on one director. If you simply do the math, ICE's 22% stake corresponds to roughly $4.6 billion; on a fully diluted basis of 14%, it comes to approximately $2.9 billion.
Unlike ICE, other funding parties can only be roughly estimated based on the amounts invested in each round and the post-money valuation at the time: Blockchain Capital holds approximately $2.3 billion (11%), 1789 Capital holds approximately $300 million (1.4%), and CEO Coplan holds approximately $2.3 billion (11%).
Unlike ICE, other funding parties can only be mechanically extrapolated based on the amounts invested in each round, the post-money valuation at the time, or media estimates. If these percentages are uniformly applied to the $21 billion valuation, Blockchain Capital's stake, back-calculated from historical rounds, comes to approximately $2.3 billion (11%); 1789 Capital approximately $300 million (1.4%); and Coplan approximately $2.3 billion (11%).
It is worth noting that Trump Jr., the eldest son of Donald Trump, serves as a partner at 1789 Capital and was already a member of Polymarket's advisory board as early as August 2025.
Equity Transfers Packaged as an IPO
In this September 20 screenshot, what truly deserves attention may not only be Polymarket, but also Paimon Finance. The screenshot links "Polymarket's upcoming IPO" with $pPOLY, and the full name of $pPOLY is Paimon Polymarket SPV Token.
Paimon is a platform that tokenizes private equity and Pre-IPO assets. Its model is to package assets related to unlisted companies into on-chain tokens. The company has previously placed assets related to private companies such as SpaceX, OpenAI, and Anthropic into the same product system.
Binance, mentioned in the screenshot, has also made the nature of this kind of product very clear: Pre-Access assets are provided by third parties, and the Binance wallet is only an access point; such assets do not represent direct shares in the underlying company, nor do they guarantee that the relevant company will necessarily complete an IPO in the future.
Therefore, a more accurate statement is not "Polymarket is issuing its own Pre-IPO shares," but rather "Paimon may be packaging private equity related to Polymarket into a token that can circulate on-chain."
For Polymarket, the real IPO may not have begun yet; but trading around IPO expectations has already appeared in advance.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Executive shake-up, is Polymarket going public?
On September 20, a screenshot about "Binance Wallet is about to launch Polymarket Pre-IPO" is circulating on X.
Polymarket was founded in 2020 by Shayne Coplan, who serves as CEO. Users can use funds to trade on the possible outcomes of politics, sports, and global events. In early September, media reports said that 1789 Capital is leading a financing round of about $1 billion, bringing the platform's post-investment valuation to $21 billion.
If viewed through the lens of "going public," Polymarket's series of moves over the past few months suddenly make sense: a group of executives from Amazon, Uber, the NYSE, Coinbase, and Robinhood have joined in quick succession; power in the U.S. business has been redistributed; the on-chain order book is preparing to be torn down and rewritten; and the company has also begun filling positions for CFO, compliance, risk control, and government relations.
It appears the platform is equipping itself with a skeleton more like that of a financial company.
Executives from major companies parachute in to pave the way for an IPO
On September 10, Warren Jenson joined Polymarket as its first company-level CFO. He previously served as a finance chief at Amazon and several other giants, and has long been responsible for the financial, capital strategy, and long-term planning of large companies.
A few days later, Collin McKinney Hill, who was formerly a general manager at DoorDash and chief of staff to the founder of Bridgewater, became vice president of operations.
Other core personnel include Travis VanderZanden, who previously worked at Uber, in charge of growth; former Coinbase executive Dan Lee in charge of the U.S. business; former Robinhood executive Megan McGrath as chief compliance officer; and Hayk Mkrtchyan, who was previously responsible for the core matching system at the NYSE, as head of engineering for Polymarket's U.S. exchange.
These people's backgrounds come from different companies, yet they respectively correspond to several of the gaps most easily exposed at a large financial platform: finance, operations, growth, U.S. business, compliance, product, and trading infrastructure are almost all being overhauled.
According to The Information, Dan Lee, who was recruited from Coinbase, has already gradually taken over Polymarket's U.S. business at the actual working level. According to people close to the company, employees report to Lee, not to the nominal CEO of the U.S. business, Justin Hertzberg.
The more direct changes are happening within the engineering team. Josh Stevens, who joined in March of this year as VP of DeFi Engineering and previously served as Senior VP of Engineering at Aave, publicly stated that the early, hastily built code can no longer be salvaged long-term, and the team is preparing to rewrite the matching engine.
His reasoning was equally straightforward: the platform is already an exchange handling user funds, not a small product where trial and error is acceptable.
If you look at these moves through the lens of an IPO strategy, it looks very much like an emergency effort to shore up the organizational capabilities of a financial platform.
$21 billion valuation — who holds stakes in this platform?
Currently, market valuation anchors for Polymarket broadly range between $15 billion and $21 billion. The only investor with reliable, publicly available data is Intercontinental Exchange (ICE), the parent company of the New York Stock Exchange.
As of June 30, 2026, ICE holds approximately 22% of the platform's issued shares and has the exclusive right to nominate and vote on one director. If you simply do the math, ICE's 22% stake corresponds to roughly $4.6 billion; on a fully diluted basis of 14%, it comes to approximately $2.9 billion.
Unlike ICE, other funding parties can only be roughly estimated based on the amounts invested in each round and the post-money valuation at the time: Blockchain Capital holds approximately $2.3 billion (11%), 1789 Capital holds approximately $300 million (1.4%), and CEO Coplan holds approximately $2.3 billion (11%).
Unlike ICE, other funding parties can only be mechanically extrapolated based on the amounts invested in each round, the post-money valuation at the time, or media estimates. If these percentages are uniformly applied to the $21 billion valuation, Blockchain Capital's stake, back-calculated from historical rounds, comes to approximately $2.3 billion (11%); 1789 Capital approximately $300 million (1.4%); and Coplan approximately $2.3 billion (11%).
It is worth noting that Trump Jr., the eldest son of Donald Trump, serves as a partner at 1789 Capital and was already a member of Polymarket's advisory board as early as August 2025.
Equity Transfers Packaged as an IPO
In this September 20 screenshot, what truly deserves attention may not only be Polymarket, but also Paimon Finance. The screenshot links "Polymarket's upcoming IPO" with $pPOLY, and the full name of $pPOLY is Paimon Polymarket SPV Token.
Paimon is a platform that tokenizes private equity and Pre-IPO assets. Its model is to package assets related to unlisted companies into on-chain tokens. The company has previously placed assets related to private companies such as SpaceX, OpenAI, and Anthropic into the same product system.
Binance, mentioned in the screenshot, has also made the nature of this kind of product very clear: Pre-Access assets are provided by third parties, and the Binance wallet is only an access point; such assets do not represent direct shares in the underlying company, nor do they guarantee that the relevant company will necessarily complete an IPO in the future.
Therefore, a more accurate statement is not "Polymarket is issuing its own Pre-IPO shares," but rather "Paimon may be packaging private equity related to Polymarket into a token that can circulate on-chain."
For Polymarket, the real IPO may not have begun yet; but trading around IPO expectations has already appeared in advance.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
·
--
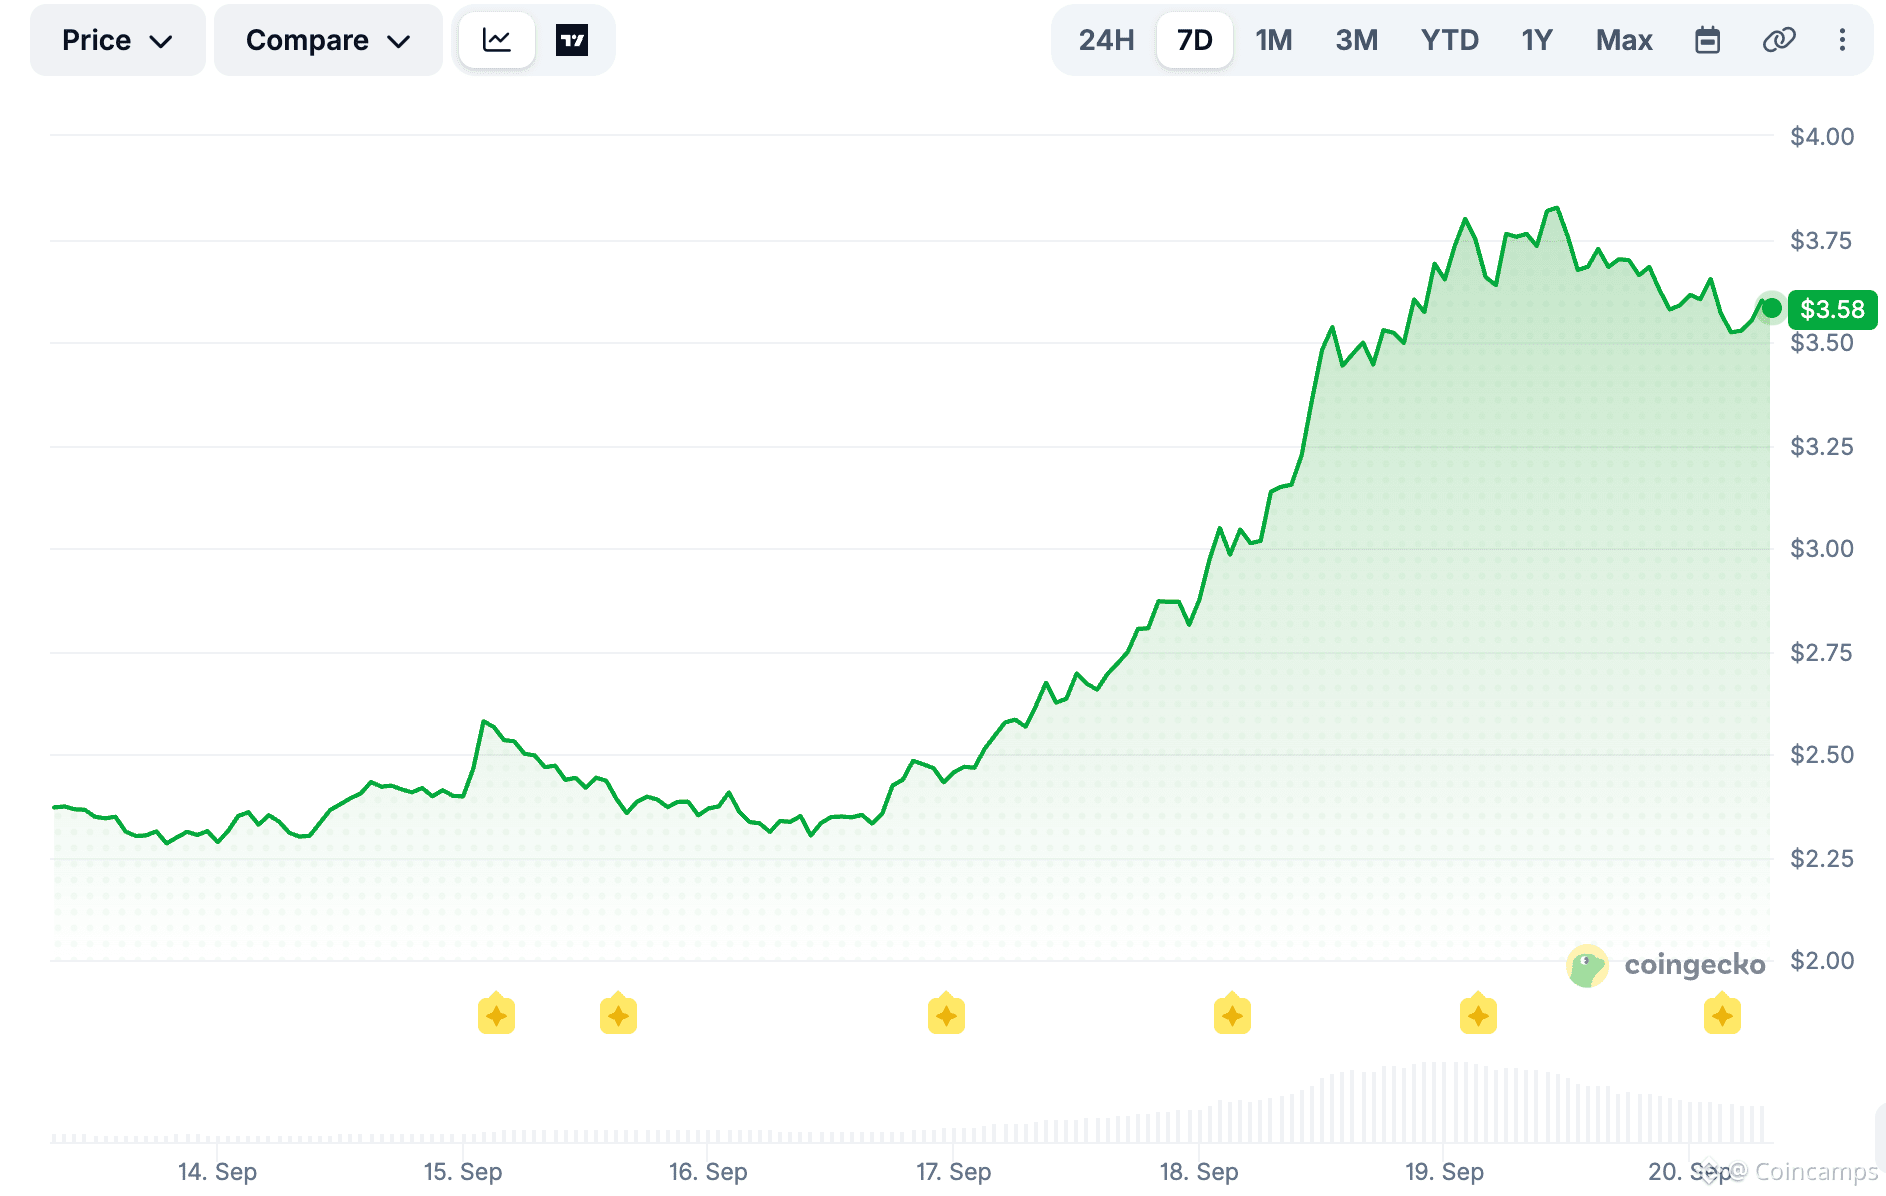
مقالة
قفزت NEAR بأكثر من 50% خلال أسبوع.. فما القصة الجديدة التي يرويها هذا الـ blockchain المخضرم؟على مدار الأسبوع الماضي، ارتفع سعر NEAR من حوالي 2.3 دولار إلى مستوى مرتفع فوق 3.9 دولارات، محققًا لفترة وجيزة مكاسب تجاوزت 50%، ليصبح واحدًا من أقوى العملات البديلة أداءً وأكثرها تداولًا في الأوساط العامة خلال هذه الفترة.
على عكس السرديات السابقة التي ركزت على التجزئة وسلاسل الكتل العامة عالية الأداء، تحاول NEAR هذه المرة أن تحكي قصة جديدة ترتبط بشكل أوثق بالطلب الحقيقي على المعاملات. بدءًا من المعاملات عبر السلاسل (cross-chain) وصولًا إلى معاملات الخصوصية، ثم إلى العقود الدائمة ووكيلـات الذكاء الاصطناعي (AI Agents)، تحاول سلسلة الكتل العامة هذه في الوقت نفسه جذب رأس المال والطلب من عدة قطاعات ساخنة.
قفزت NEAR بأكثر من 50% خلال أسبوع.. فما القصة الجديدة التي يرويها هذا الـ blockchain المخضرم؟
على مدار الأسبوع الماضي، ارتفع سعر NEAR من حوالي 2.3 دولار إلى مستوى مرتفع فوق 3.9 دولارات، محققًا لفترة وجيزة مكاسب تجاوزت 50%، ليصبح واحدًا من أقوى العملات البديلة أداءً وأكثرها تداولًا في الأوساط العامة خلال هذه الفترة.
على عكس السرديات السابقة التي ركزت على التجزئة وسلاسل الكتل العامة عالية الأداء، تحاول NEAR هذه المرة أن تحكي قصة جديدة ترتبط بشكل أوثق بالطلب الحقيقي على المعاملات. بدءًا من المعاملات عبر السلاسل (cross-chain) وصولًا إلى معاملات الخصوصية، ثم إلى العقود الدائمة ووكيلـات الذكاء الاصطناعي (AI Agents)، تحاول سلسلة الكتل العامة هذه في الوقت نفسه جذب رأس المال والطلب من عدة قطاعات ساخنة.
على عكس السرديات السابقة التي ركزت على التجزئة وسلاسل الكتل العامة عالية الأداء، تحاول NEAR هذه المرة أن تحكي قصة جديدة ترتبط بشكل أوثق بالطلب الحقيقي على المعاملات. بدءًا من المعاملات عبر السلاسل (cross-chain) وصولًا إلى معاملات الخصوصية، ثم إلى العقود الدائمة ووكيلـات الذكاء الاصطناعي (AI Agents)، تحاول سلسلة الكتل العامة هذه في الوقت نفسه جذب رأس المال والطلب من عدة قطاعات ساخنة.
298
·
--
مقالة
جميع شركات المركبات الصينية الجديدة للطاقة تريد أن تصبح شركات ذكاء اصطناعي.العنوان الأصلي: "شركات المركبات الصينية الجديدة للطاقة جميعها تريد أن تصبح شركات للذكاء الاصطناعي"
المؤلف الأصلي: دونغتشا بييتينغ
شركات المركبات الصينية الجديدة للطاقة جميعها تريد أن تصبح شركات ذكاء اصطناعي الآن.
لكن نقطة البداية في هذا العمل لم تكن تمتلك لا خوارزميات ولا قدرات حوسبة، ولم يكن من العدل حتى أن نسميها منطقًا تجاريًا.
في عام 2009، أُطلق برنامج "عشر مدن، ألف مركبة"، وبدأت الحكومة بإنفاق أموال حقيقية لدعم منتج تجريبي لا يشتريه أحد. كانت صناعة السيارات في الصين قد انحُصرت بسبب براءات محركات الاحتراق الداخلي لأكثر من نصف قرن، وسعت إلى استغلال هذه الفرصة لتغيير المسار والاختراق. وما إن فُتحت البوابة، اختلط صُنّاع السيارات الحقيقيون بمن يقومون بتحقيق مكاسب ربحية من خلال استغلال المنافع، واشتعلت الطموحات والمضاربات بلا ضوابط على المسار نفسه.
جميع شركات المركبات الصينية الجديدة للطاقة تريد أن تصبح شركات ذكاء اصطناعي.
العنوان الأصلي: "شركات المركبات الصينية الجديدة للطاقة جميعها تريد أن تصبح شركات للذكاء الاصطناعي"
المؤلف الأصلي: دونغتشا بييتينغ
شركات المركبات الصينية الجديدة للطاقة جميعها تريد أن تصبح شركات ذكاء اصطناعي الآن.
لكن نقطة البداية في هذا العمل لم تكن تمتلك لا خوارزميات ولا قدرات حوسبة، ولم يكن من العدل حتى أن نسميها منطقًا تجاريًا.
في عام 2009، أُطلق برنامج "عشر مدن، ألف مركبة"، وبدأت الحكومة بإنفاق أموال حقيقية لدعم منتج تجريبي لا يشتريه أحد. كانت صناعة السيارات في الصين قد انحُصرت بسبب براءات محركات الاحتراق الداخلي لأكثر من نصف قرن، وسعت إلى استغلال هذه الفرصة لتغيير المسار والاختراق. وما إن فُتحت البوابة، اختلط صُنّاع السيارات الحقيقيون بمن يقومون بتحقيق مكاسب ربحية من خلال استغلال المنافع، واشتعلت الطموحات والمضاربات بلا ضوابط على المسار نفسه.
359
·
--
عرض الترجمة
Binance EN: Binance Futures Will Launch USDBRLUSDT USDⓈ-Margined TradFi Perpetual Contract (2026-09-21)
Binance EN: Binance Futures Will Launch USDBRLUSDT USDⓈ-Margined TradFi Perpetual Contract (2026-09-21)
Binance EN: Binance Futures Will Launch USDBRLUSDT USDⓈ-Margined TradFi Perpetual Contract (2026-09-21)
Binance EN: Binance Futures Will Launch USDBRLUSDT USDⓈ-Margined TradFi Perpetual Contract (2026-09-21)
Binance EN: Binance Futures Will Launch USDBRLUSDT USDⓈ-Margined TradFi Perpetual Contract (2026-09-21)
29
·
--
Binance EN: ستدعم Binance عملية دمج رمز Stargate Finance (STG) إلى LayerZero (ZRO)
Binance EN: ستدعم Binance عملية دمج رمز Stargate Finance (STG) إلى LayerZero (ZRO)
القيمة السوقية لـ ZRO: 792 مليون
القيمة السوقية لـ STG: 153 مليون
Binance EN: ستدعم Binance عملية دمج رمز Stargate Finance (STG) إلى LayerZero (ZRO)
Binance EN: ستدعم Binance عملية دمج رمز Stargate Finance (STG) إلى LayerZero (ZRO)
القيمة السوقية لـ ZRO: 792 مليون
القيمة السوقية لـ STG: 153 مليون
Binance EN: ستدعم Binance عملية دمج رمز Stargate Finance (STG) إلى LayerZero (ZRO)
القيمة السوقية لـ ZRO: 792 مليون
القيمة السوقية لـ STG: 153 مليون
307
·
--
عرض الترجمة
Binance EN: Binance Futures Will List USDⓈ-M & COIN-M Quarterly 0326 Delivery Contracts
Binance EN: Binance Futures Will List USDⓈ-M & COIN-M Quarterly 0326 Delivery Contracts
COIN MarketCap: 50B
Binance EN: Binance Futures Will List USDⓈ-M & COIN-M Quarterly 0326 Delivery Contracts
Binance EN: Binance Futures Will List USDⓈ-M & COIN-M Quarterly 0326 Delivery Contracts
COIN MarketCap: 50B
Binance EN: Binance Futures Will List USDⓈ-M & COIN-M Quarterly 0326 Delivery Contracts
COIN MarketCap: 50B
62
سجّل الدخول لاستكشاف المزيد من المُحتوى
انضم إلى مُستخدمي العملات الرقمية حول العالم على Binance Square
⚡️ احصل على أحدث المعلومات المفيدة عن العملات الرقمية.
💬 موثوقة من قبل أكبر منصّة لتداول العملات الرقمية في العالم.
👍 اكتشف الرؤى الحقيقية من صنّاع المُحتوى الموثوقين.
البريد الإلكتروني / رقم الهاتف
المواضيع الرائجة
BitcoinParesGainsAfterRallyTo$86.5K
12,924 مشاهدات
61 يقومون بالنقاش
🔥 $BTC على الحافة: مواجهة 86 ألف دولار!
Nurul Hasnat Samir
·0 إعجاب
·163 مشاهدات
CerebrasSinksNearly20%OnReportNvidiaToPowerOpenAI
23,951 مشاهدات
311 يقومون بالنقاش
SECProposesCryptoCustodyRules
50,811 مشاهدات
481 يقومون بالنقاش