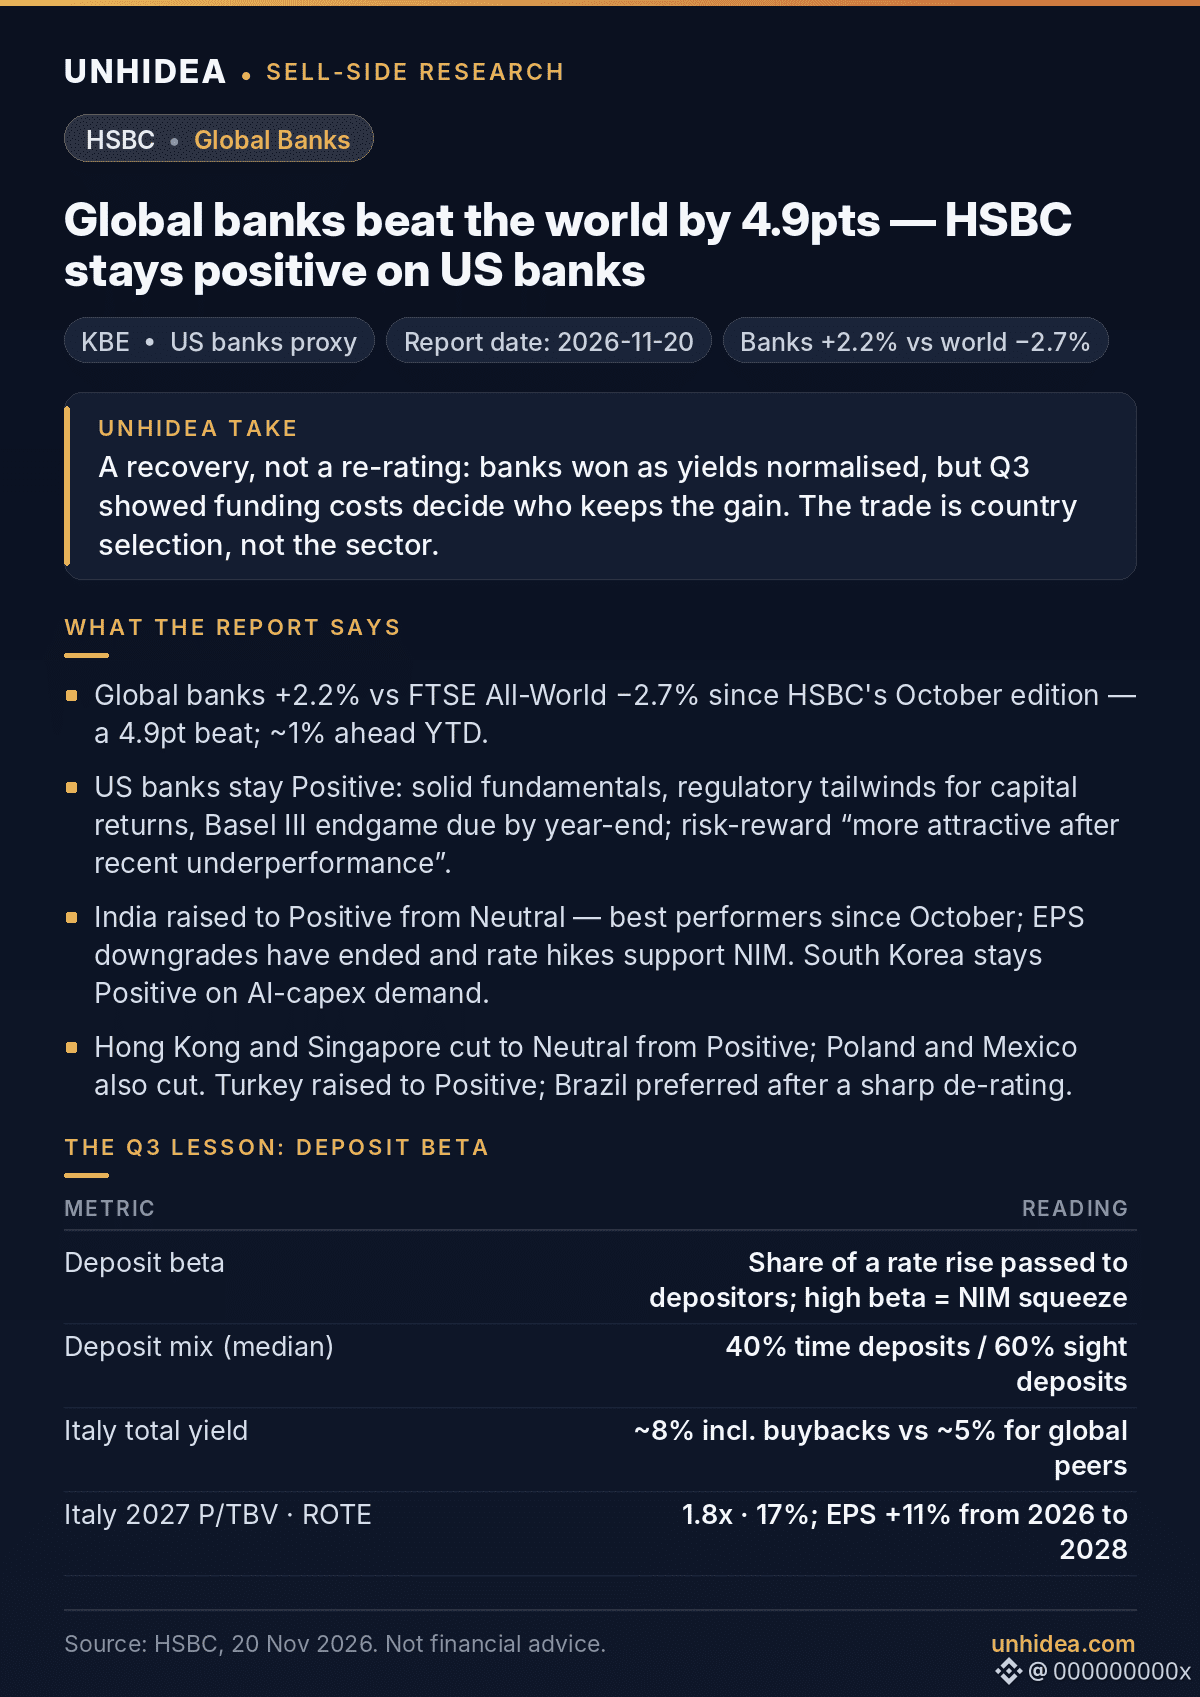
$KBE: global banks beat the world by 4.9pts since October — and HSBC stays positive on US banks.
- HSBC, 20 Nov: global banks +2.2% vs FTSE All-World −2.7% since its October edition; ~1% ahead YTD as yields normalised from their October peak.
- US banks stay Positive: solid fundamentals, regulatory tailwinds for capital returns, Basel III endgame due by year-end. Risk-reward "more attractive after recent underperformance".
- India raised to Positive — best performers since October; EPS downgrades have ended, rate hikes support NIM. South Korea stays Positive on AI-capex demand.
- HK and Singapore cut to Neutral; Turkey raised to Positive; Brazil preferred after a sharp de-rating.
- The Q3 lesson: deposit beta. Funding costs repriced ahead of asset yields, squeezing NIM; median deposit mix is 40% time / 60% sight.
Unhidea take: a recovery, not a re-rating — banks won because yields normalised. The trade is country selection, not the sector.
Unhidea take: watch deposit beta, not just rates. Where deposits reprice fast, higher rates help banks less.
Post-report, 20 Nov: S&P 500 −3.8%, Nasdaq −5.1%.
Risks: fiscal consolidation (HSBC's main 2027 risk), deposit-cost pressure, AI-spending worries.
Source: HSBC, 20 Nov 2026. Not financial advice.
- HSBC, 20 Nov: global banks +2.2% vs FTSE All-World −2.7% since its October edition; ~1% ahead YTD as yields normalised from their October peak.
- US banks stay Positive: solid fundamentals, regulatory tailwinds for capital returns, Basel III endgame due by year-end. Risk-reward "more attractive after recent underperformance".
- India raised to Positive — best performers since October; EPS downgrades have ended, rate hikes support NIM. South Korea stays Positive on AI-capex demand.
- HK and Singapore cut to Neutral; Turkey raised to Positive; Brazil preferred after a sharp de-rating.
- The Q3 lesson: deposit beta. Funding costs repriced ahead of asset yields, squeezing NIM; median deposit mix is 40% time / 60% sight.
Unhidea take: a recovery, not a re-rating — banks won because yields normalised. The trade is country selection, not the sector.
Unhidea take: watch deposit beta, not just rates. Where deposits reprice fast, higher rates help banks less.
Post-report, 20 Nov: S&P 500 −3.8%, Nasdaq −5.1%.
Risks: fiscal consolidation (HSBC's main 2027 risk), deposit-cost pressure, AI-spending worries.
Source: HSBC, 20 Nov 2026. Not financial advice.