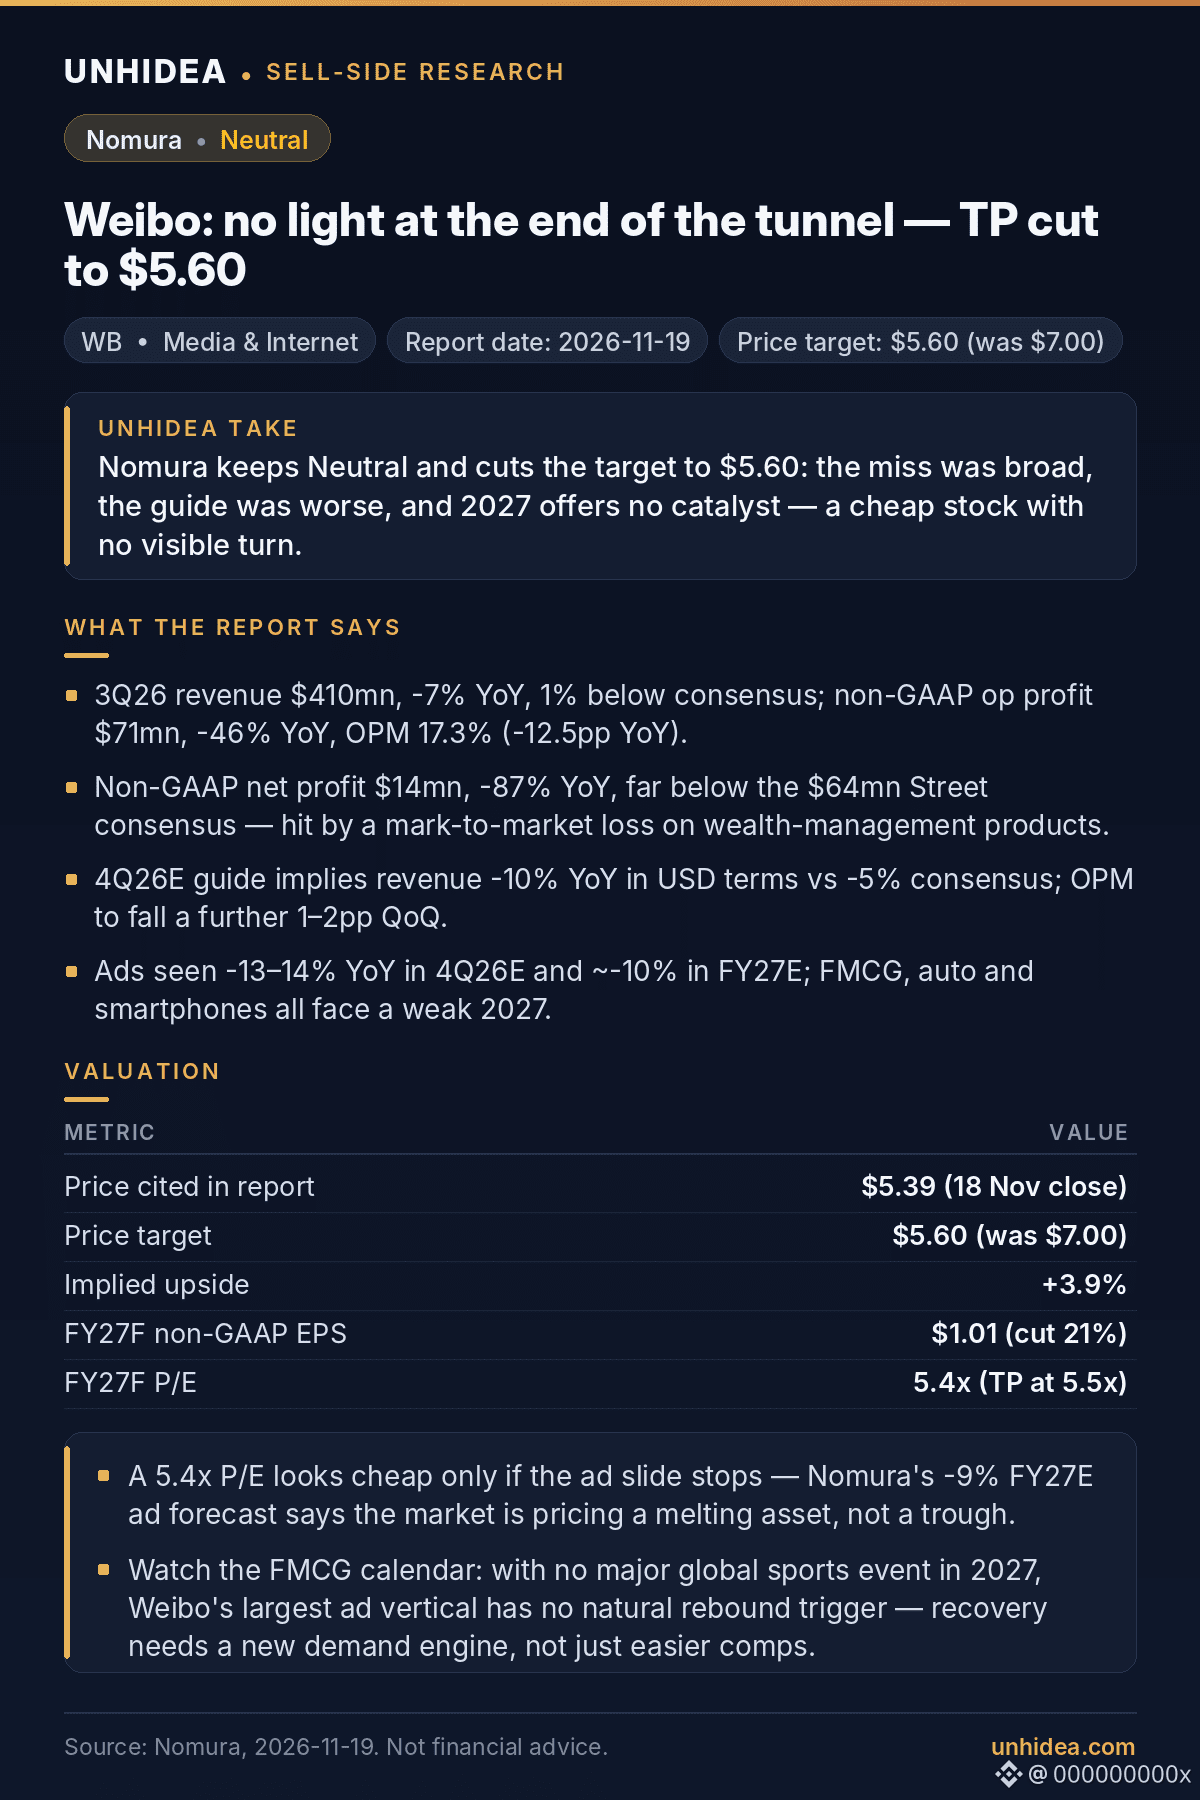
$WB: Nomura keeps Neutral on Weibo and cuts its target to $5.60 from $7.00 — just +3.9% above the $5.39 close cited in the report (18 Nov). "No light at the end of the tunnel."
- 3Q26 revenue $410mn, -7% YoY and 1% below consensus; non-GAAP operating profit $71mn, -46% YoY, with margin down 12.5pp to 17.3%.
- Non-GAAP net profit fell 87% YoY to $14mn vs a $64mn consensus, hit by a mark-to-market loss on wealth-management products.
- 4Q26E guidance implies revenue -10% YoY in USD terms vs -5% consensus; margin is guided down another 1–2pp QoQ.
- Ads are the problem: -13–14% YoY guided for 4Q26E, ~-10% in FY27E. FMCG, the largest vertical, faces a 2027 with no major global sports event; auto and smartphone spend also weaken.
- Nomura cut FY27E non-GAAP EPS 21% to $1.01 and revenue 10% to $1,595mn; the stock trades at 5.4x FY27E P/E.
Unhidea take: 5.4x looks cheap only if the ad slide stops — Nomura's -9% FY27E ad forecast says the market is pricing a melting asset, not a trough.
Unhidea take: watch the FMCG calendar — with no big sports event in 2027, the largest ad vertical has no natural rebound trigger; recovery needs a new demand engine.
Risks: a faster ad recovery is the upside; tighter UGC regulation and rival social platforms are the downsides.
Source: Nomura, 19 Nov 2026. Not financial advice.
- 3Q26 revenue $410mn, -7% YoY and 1% below consensus; non-GAAP operating profit $71mn, -46% YoY, with margin down 12.5pp to 17.3%.
- Non-GAAP net profit fell 87% YoY to $14mn vs a $64mn consensus, hit by a mark-to-market loss on wealth-management products.
- 4Q26E guidance implies revenue -10% YoY in USD terms vs -5% consensus; margin is guided down another 1–2pp QoQ.
- Ads are the problem: -13–14% YoY guided for 4Q26E, ~-10% in FY27E. FMCG, the largest vertical, faces a 2027 with no major global sports event; auto and smartphone spend also weaken.
- Nomura cut FY27E non-GAAP EPS 21% to $1.01 and revenue 10% to $1,595mn; the stock trades at 5.4x FY27E P/E.
Unhidea take: 5.4x looks cheap only if the ad slide stops — Nomura's -9% FY27E ad forecast says the market is pricing a melting asset, not a trough.
Unhidea take: watch the FMCG calendar — with no big sports event in 2027, the largest ad vertical has no natural rebound trigger; recovery needs a new demand engine.
Risks: a faster ad recovery is the upside; tighter UGC regulation and rival social platforms are the downsides.
Source: Nomura, 19 Nov 2026. Not financial advice.