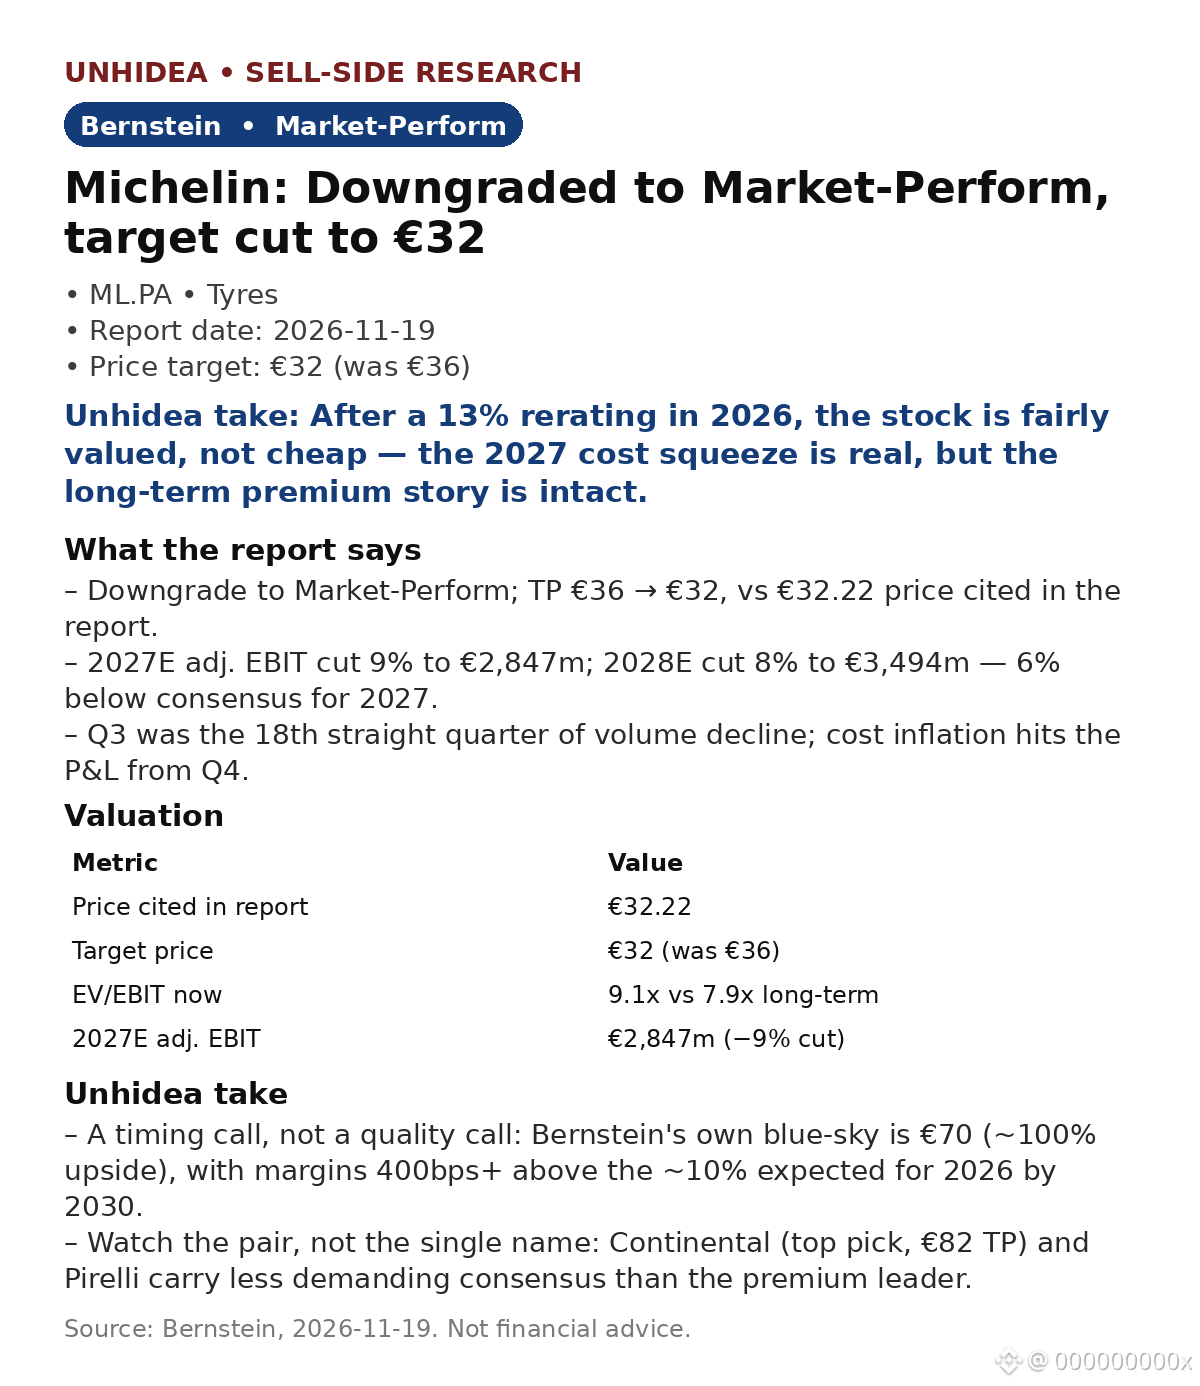
$ML.PA: Bernstein cuts Michelin to Market-Perform, target €32 (was €36) — after a 13% rerating in 2026, fairly valued, not cheap.
- 2027E adj. EBIT cut 9% to €2,847m; 2028E cut 8% to €3,494m — 6% below consensus for 2027 (>10% below in H1) as raw-material inflation hits from Q4 and pricing power fades.
- Consensus still sees +8% EBIT growth in 2027; Bernstein says recovery slips into 2028. Q3 was the 18th straight quarter of volume decline.
- At 9.1x EBIT vs a 7.9x long-term multiple, the rerating has done the work. Continental stays top pick (€82 TP); Pirelli kept Outperform.
Unhidea take: a timing call, not a quality call — Bernstein's own blue-sky is €70 (~100% upside), margins 400bps+ above 2026's ~10% by 2030. The 2027 air pocket is real; the franchise isn't broken.
Unhidea take: watch the pair, not the single name — the "downtrade" hits the premium leader hardest. Feb results are the negative catalyst; May's CMD could re-rate the story.
Valuation: Market-Perform, €32 TP at 7.9x EBIT, ~flat vs the €32.22 price cited in the report.
Risks: raw-material inflation, pricing pressure, share loss, supply/demand imbalance by 2030.
Source: Bernstein, 19 Nov 2026. Not financial advice.
- 2027E adj. EBIT cut 9% to €2,847m; 2028E cut 8% to €3,494m — 6% below consensus for 2027 (>10% below in H1) as raw-material inflation hits from Q4 and pricing power fades.
- Consensus still sees +8% EBIT growth in 2027; Bernstein says recovery slips into 2028. Q3 was the 18th straight quarter of volume decline.
- At 9.1x EBIT vs a 7.9x long-term multiple, the rerating has done the work. Continental stays top pick (€82 TP); Pirelli kept Outperform.
Unhidea take: a timing call, not a quality call — Bernstein's own blue-sky is €70 (~100% upside), margins 400bps+ above 2026's ~10% by 2030. The 2027 air pocket is real; the franchise isn't broken.
Unhidea take: watch the pair, not the single name — the "downtrade" hits the premium leader hardest. Feb results are the negative catalyst; May's CMD could re-rate the story.
Valuation: Market-Perform, €32 TP at 7.9x EBIT, ~flat vs the €32.22 price cited in the report.
Risks: raw-material inflation, pricing pressure, share loss, supply/demand imbalance by 2030.
Source: Bernstein, 19 Nov 2026. Not financial advice.