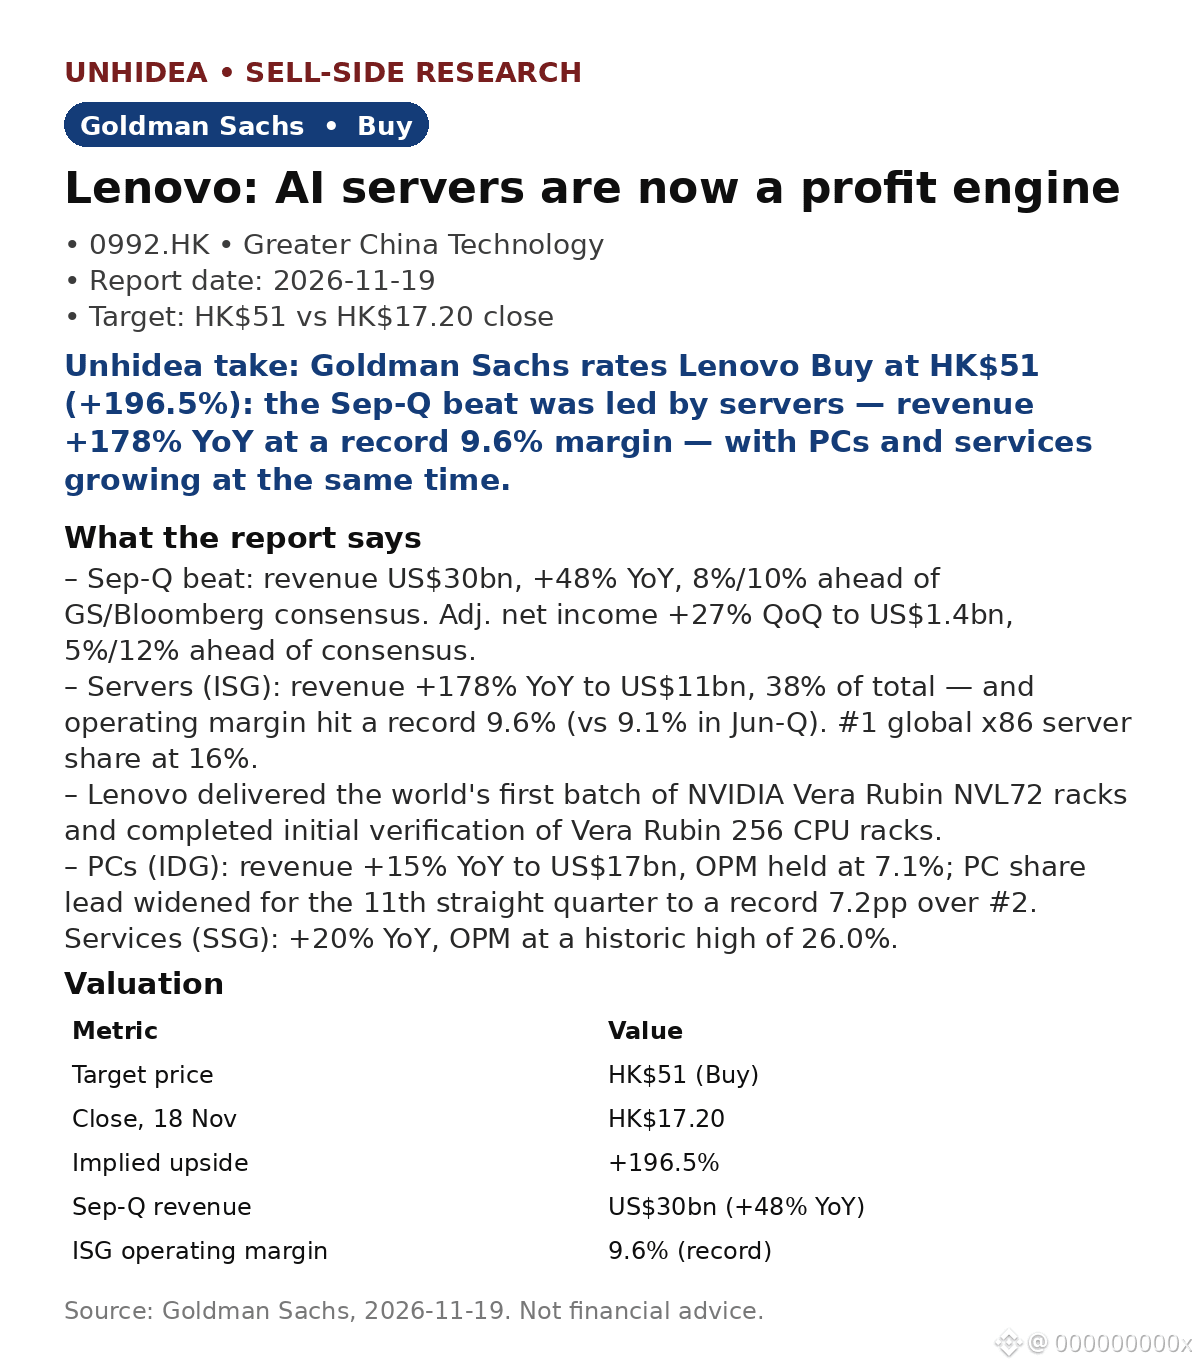
$0992.HK: Goldman Sachs says Lenovo's AI servers just became a profit engine — Buy, HK$51 target, +196.5% vs the HK$17.20 close on 18 Nov.
- Sep-Q beat: revenue US$30bn, +48% YoY, 8%/10% ahead of GS/Bloomberg consensus. Adj. net income +27% QoQ to US$1.4bn.
- Servers (ISG): revenue +178% YoY to US$11bn, 38% of total — operating margin hit a record 9.6% (vs 9.1% in Jun-Q). #1 global x86 server share at 16%.
- Lenovo delivered the world's first NVIDIA Vera Rubin NVL72 racks; PCs (IDG) +15% YoY to US$17bn, OPM 7.1%; services (SSG) +20% YoY, OPM at a historic high of 26.0%.
Unhidea take: the margin is the story — AI servers growing 178% while margins expand is a profit engine, not just volume. Lenovo is priced as a PC cyclical; the numbers say full-stack AI play.
Unhidea take: watch whether the record server margin holds as Rubin ramps — if it does, the 18.5x CY27E multiple behind HK$51 looks conservative.
Valuation: Buy, HK$51 (18.5x CY2027E EPS), +196.5% vs HK$17.20 close 18 Nov.
Risks: slower demand; fiercer AI-server competition; longer inventory digestion.
Source: Goldman Sachs, 19 Nov 2026. Not financial advice.
- Sep-Q beat: revenue US$30bn, +48% YoY, 8%/10% ahead of GS/Bloomberg consensus. Adj. net income +27% QoQ to US$1.4bn.
- Servers (ISG): revenue +178% YoY to US$11bn, 38% of total — operating margin hit a record 9.6% (vs 9.1% in Jun-Q). #1 global x86 server share at 16%.
- Lenovo delivered the world's first NVIDIA Vera Rubin NVL72 racks; PCs (IDG) +15% YoY to US$17bn, OPM 7.1%; services (SSG) +20% YoY, OPM at a historic high of 26.0%.
Unhidea take: the margin is the story — AI servers growing 178% while margins expand is a profit engine, not just volume. Lenovo is priced as a PC cyclical; the numbers say full-stack AI play.
Unhidea take: watch whether the record server margin holds as Rubin ramps — if it does, the 18.5x CY27E multiple behind HK$51 looks conservative.
Valuation: Buy, HK$51 (18.5x CY2027E EPS), +196.5% vs HK$17.20 close 18 Nov.
Risks: slower demand; fiercer AI-server competition; longer inventory digestion.
Source: Goldman Sachs, 19 Nov 2026. Not financial advice.