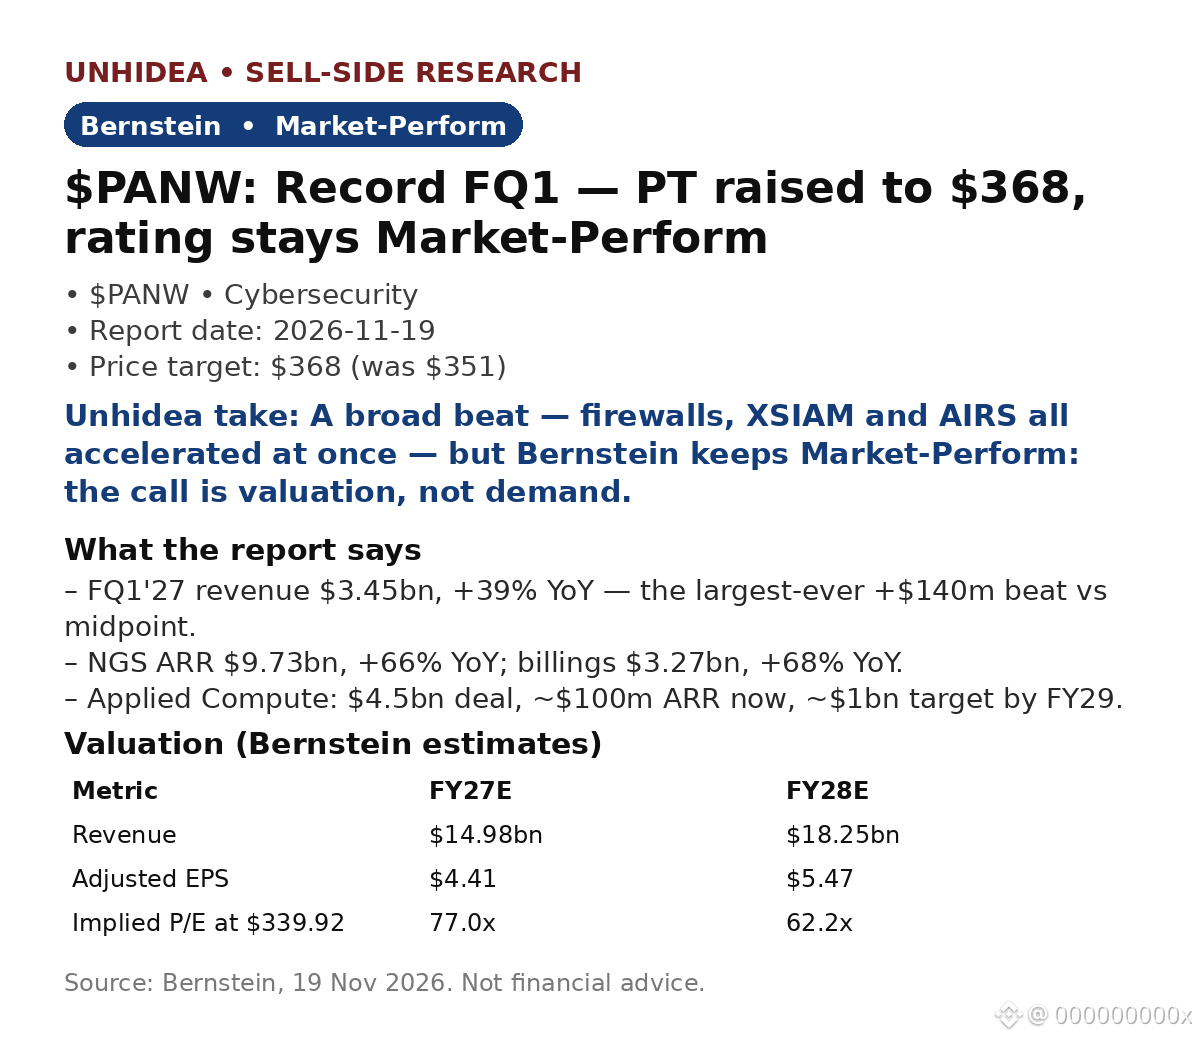
$PANW: Bernstein lifts its target to $368 (+8% vs the $339.92 close on 18 Nov) after a record FQ1'27 — but keeps Market-Perform, purely on extended cyber multiples.
- Revenue $3.45bn, +39% YoY, beat consensus $3.31bn by ~4% — the largest-ever +$140m beat vs midpoint. Non-GAAP EPS $1.05, +13% YoY, vs $0.97 consensus.
- NGS ARR $9.73bn, +66% YoY; billings $3.27bn, +68% YoY, vs $2.67bn consensus.
- Firewall bookings +28%; Prisma AIRS added $50m ARR in the quarter to $170m; XSIAM grew 65%+ at $700m+ ARR.
- Applied Compute: a $4.5bn all-stock deal for ~$100m of ARR today, targeting ~$1bn by FY29 — not in guidance until it closes (hopefully FQ3).
- Palo Alto raised FY27 guidance: revenue $14.52–14.57bn (+26–27%) vs $14.10–14.20bn before; adj. EPS $4.26–4.30. Shares +6.4% on 19 Nov to $361.73. (Post-report market data.)
Unhidea take: the beat was broad — firewalls, XSIAM and AIRS accelerated together. That's platform breadth, not a one-product spike. The test: does 60%+ NGS ARR growth survive Chronosphere rolling into organic numbers in FQ2?
Unhidea take: Applied Compute is the real bet — PANW buying into securing AI model-building itself. But $4.5bn for ~$100m of ARR means execution, not the announcement, decides if it's a second engine or an expensive option.
Risks: FCF missed consensus ($1.84bn vs $1.94bn); margin pressure from hardware/cloud costs; deal execution.
Source: Bernstein, 19 Nov 2026. Not financial advice.
- Revenue $3.45bn, +39% YoY, beat consensus $3.31bn by ~4% — the largest-ever +$140m beat vs midpoint. Non-GAAP EPS $1.05, +13% YoY, vs $0.97 consensus.
- NGS ARR $9.73bn, +66% YoY; billings $3.27bn, +68% YoY, vs $2.67bn consensus.
- Firewall bookings +28%; Prisma AIRS added $50m ARR in the quarter to $170m; XSIAM grew 65%+ at $700m+ ARR.
- Applied Compute: a $4.5bn all-stock deal for ~$100m of ARR today, targeting ~$1bn by FY29 — not in guidance until it closes (hopefully FQ3).
- Palo Alto raised FY27 guidance: revenue $14.52–14.57bn (+26–27%) vs $14.10–14.20bn before; adj. EPS $4.26–4.30. Shares +6.4% on 19 Nov to $361.73. (Post-report market data.)
Unhidea take: the beat was broad — firewalls, XSIAM and AIRS accelerated together. That's platform breadth, not a one-product spike. The test: does 60%+ NGS ARR growth survive Chronosphere rolling into organic numbers in FQ2?
Unhidea take: Applied Compute is the real bet — PANW buying into securing AI model-building itself. But $4.5bn for ~$100m of ARR means execution, not the announcement, decides if it's a second engine or an expensive option.
Risks: FCF missed consensus ($1.84bn vs $1.94bn); margin pressure from hardware/cloud costs; deal execution.
Source: Bernstein, 19 Nov 2026. Not financial advice.