$SQM: J.P. Morgan stays Overweight with a $71 target — +45% vs the $49 close — even after a Q3 miss
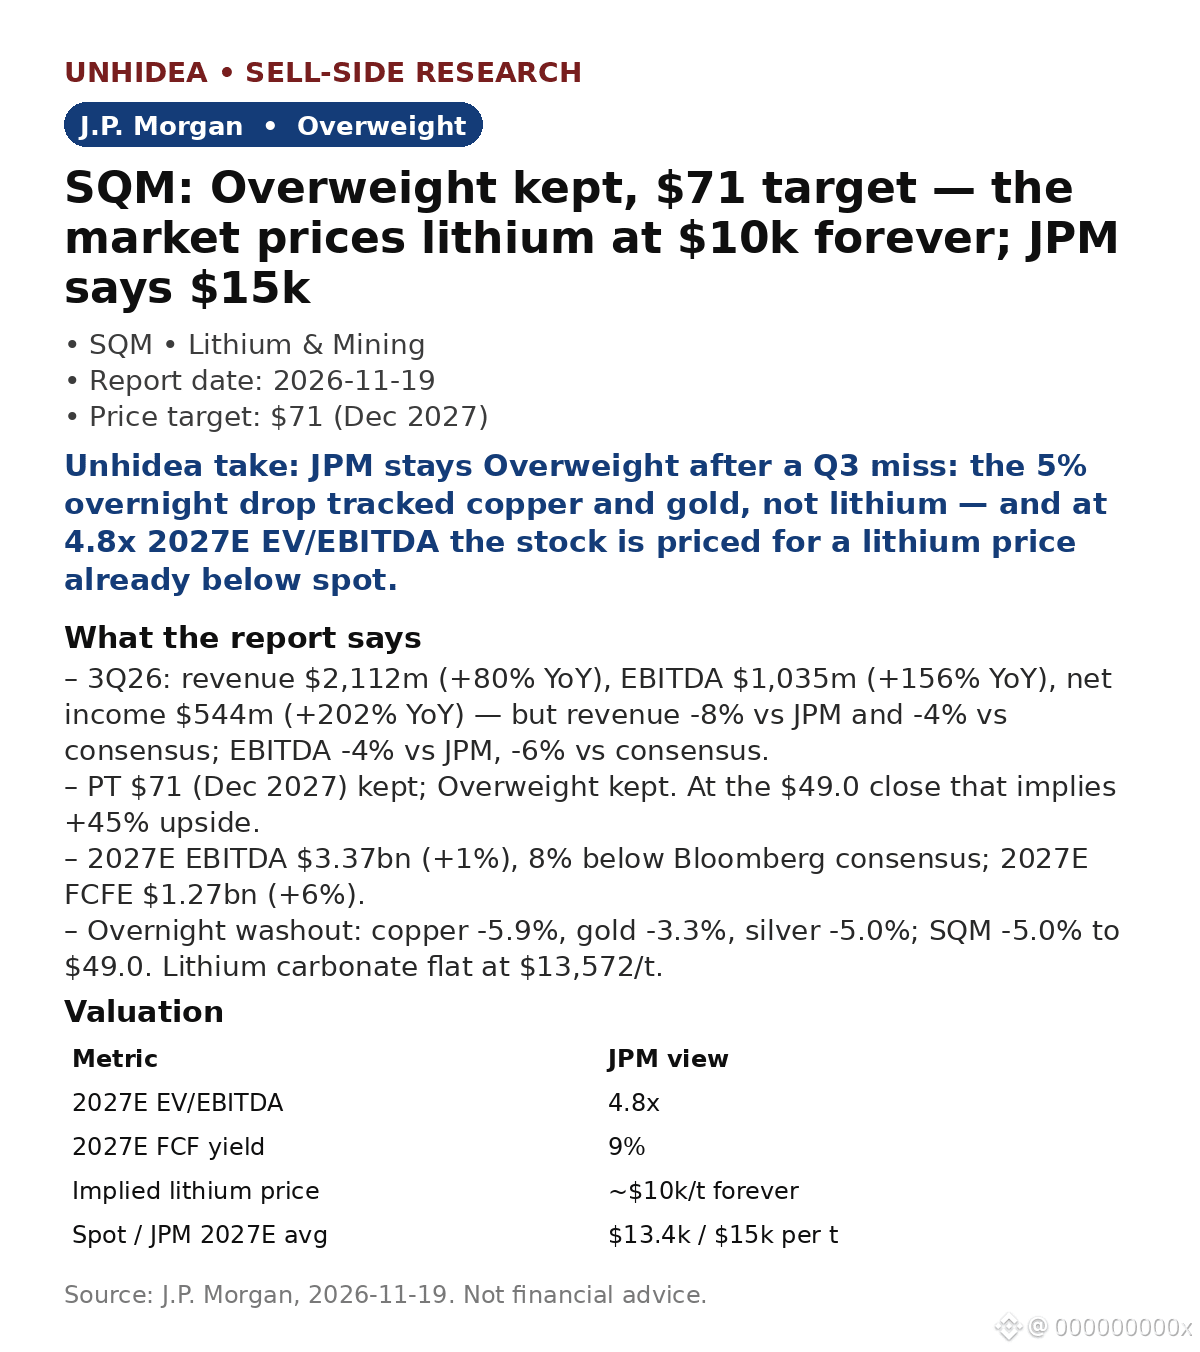
- 3Q26: revenue $2,112m (+80% YoY), EBITDA $1,035m (+156% YoY), net income $544m (+202% YoY). But all three missed: revenue -8% vs JPM, -4% vs consensus; EBITDA -4% / -6%; net income -18% / -2%.
- JPM keeps Overweight and its Dec-2027 $71 PT. 2027E EBITDA nudged up 1% to $3.37bn (8% below Bloomberg consensus); 2027E FCFE +6% to $1.27bn.
- SQM fell 5.0% overnight to $49.0 in a broad metals washout: copper -5.9% to $5.65/lb, gold -3.3% to $3,724/oz, silver -5.0%. Lithium carbonate, though, was flat at $13,572/t.
- Valuation: 4.8x 2027E EV/EBITDA, 9% FCF yield. JPM says the price implies lithium at ~$10k/t forever — vs $13.4k/t spot and a $15k/t 2027E average.
Unhidea take: SQM fell 5% on a night its own product didn't move — lithium carbonate was flat while copper and gold sold off on rate-hike fears. That is a sentiment dislocation, not a lithium call, and it is exactly what JPM's entry-point argument rests on.
Unhidea take: the market prices lithium as if $10k/t lasts forever, but JPM's base case is deficits in 2026–27. If the deficit shows up, the re-rate is in the price, not the volume — but management's own warning that 4Q realized prices could fall "substantially" means the next print, not the thesis, is the near-term risk.
Risks: lower 4Q lithium prices, SPN/iodine volume cuts, rate-hike repricing, China demand.
Source: J.P. Morgan, 19 Nov 2026. Not financial advice.
- 3Q26: revenue $2,112m (+80% YoY), EBITDA $1,035m (+156% YoY), net income $544m (+202% YoY). But all three missed: revenue -8% vs JPM, -4% vs consensus; EBITDA -4% / -6%; net income -18% / -2%.
- JPM keeps Overweight and its Dec-2027 $71 PT. 2027E EBITDA nudged up 1% to $3.37bn (8% below Bloomberg consensus); 2027E FCFE +6% to $1.27bn.
- SQM fell 5.0% overnight to $49.0 in a broad metals washout: copper -5.9% to $5.65/lb, gold -3.3% to $3,724/oz, silver -5.0%. Lithium carbonate, though, was flat at $13,572/t.
- Valuation: 4.8x 2027E EV/EBITDA, 9% FCF yield. JPM says the price implies lithium at ~$10k/t forever — vs $13.4k/t spot and a $15k/t 2027E average.
Unhidea take: SQM fell 5% on a night its own product didn't move — lithium carbonate was flat while copper and gold sold off on rate-hike fears. That is a sentiment dislocation, not a lithium call, and it is exactly what JPM's entry-point argument rests on.
Unhidea take: the market prices lithium as if $10k/t lasts forever, but JPM's base case is deficits in 2026–27. If the deficit shows up, the re-rate is in the price, not the volume — but management's own warning that 4Q realized prices could fall "substantially" means the next print, not the thesis, is the near-term risk.
Risks: lower 4Q lithium prices, SPN/iodine volume cuts, rate-hike repricing, China demand.
Source: J.P. Morgan, 19 Nov 2026. Not financial advice.