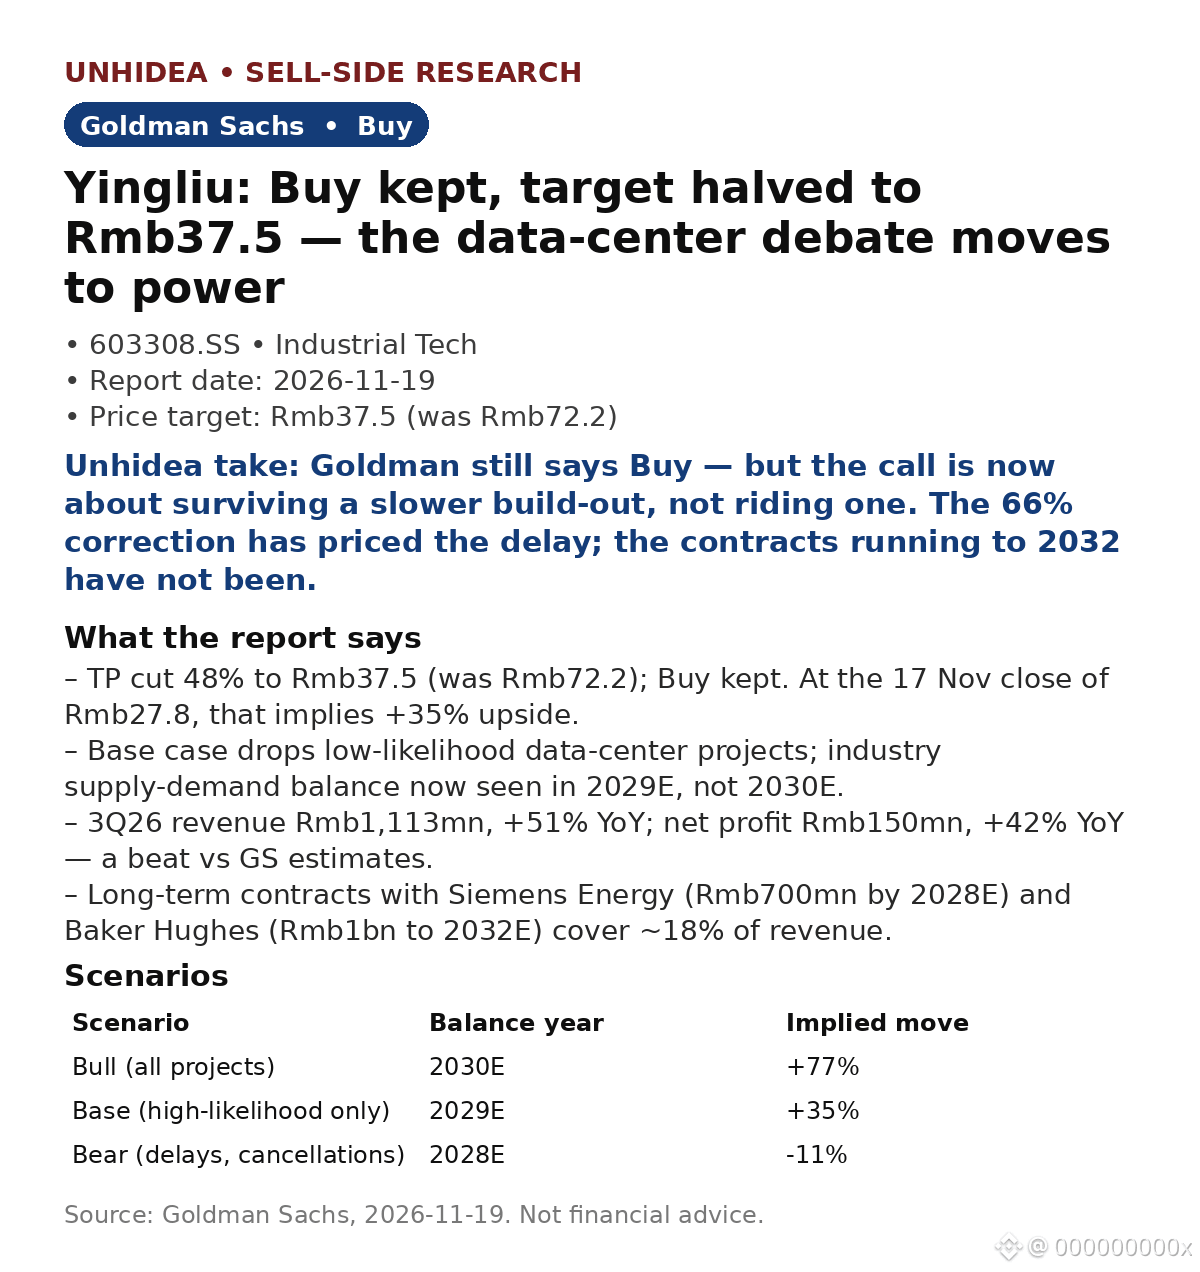
$603308.SS: Goldman halves its target — but keeps the Buy. The data-center debate has moved from chips to power.
- GS cuts Yingliu's TP 48% to Rmb37.5 (was Rmb72.2) and keeps Buy. At the 17 Nov close of Rmb27.8, that implies +35% upside. The cut is a multiple reset — 25x trough P/E on 2029E earnings — not a demand collapse.
- GS splits the US data-center pipeline into under-construction (87 GW by 2030E, 155% of today's 56 GW), announced high-likelihood (148 GW) and low-likelihood (213 GW). The base case drops the last bucket, so industry balance arrives in 2029E, a year earlier.
- The trigger: Democratic gubernatorial wins and state campaigns to tighten data-center rules. Even in GS's bear case — high-likelihood projects delayed a year, 10–40% cancelled — downside is just −11%.
- The cushion: long-term contracts with Siemens Energy and Baker Hughes cover ~18% of revenue and run to 2028–32E. And the business just beat: 3Q26 revenue Rmb1,113mn, +51% YoY; net profit Rmb150mn, +42% YoY.
Unhidea take: the stock has corrected 66% from its peak — the market has priced the delay. What it hasn't priced is that turbine blades are the bottleneck: OEMs are sold out, and Yingliu holds <1% global share with room to take spillover demand.
Unhidea take: watch the power mix, not the chip cycle. GS expects US AI data centers to draw up to ~60% of power from gas turbines — if delays stretch, the question is who keeps the orders.
Risks: US state moratoria, order cancellations, raw-material costs pressuring margins.
Source: Goldman Sachs, 19 Nov 2026. Post-report news: NVIDIA beat FQ3 — revenue $115.8bn vs ~$109bn expected, Q4 guide ~$130bn (CNBC). Not financial advice.
- GS cuts Yingliu's TP 48% to Rmb37.5 (was Rmb72.2) and keeps Buy. At the 17 Nov close of Rmb27.8, that implies +35% upside. The cut is a multiple reset — 25x trough P/E on 2029E earnings — not a demand collapse.
- GS splits the US data-center pipeline into under-construction (87 GW by 2030E, 155% of today's 56 GW), announced high-likelihood (148 GW) and low-likelihood (213 GW). The base case drops the last bucket, so industry balance arrives in 2029E, a year earlier.
- The trigger: Democratic gubernatorial wins and state campaigns to tighten data-center rules. Even in GS's bear case — high-likelihood projects delayed a year, 10–40% cancelled — downside is just −11%.
- The cushion: long-term contracts with Siemens Energy and Baker Hughes cover ~18% of revenue and run to 2028–32E. And the business just beat: 3Q26 revenue Rmb1,113mn, +51% YoY; net profit Rmb150mn, +42% YoY.
Unhidea take: the stock has corrected 66% from its peak — the market has priced the delay. What it hasn't priced is that turbine blades are the bottleneck: OEMs are sold out, and Yingliu holds <1% global share with room to take spillover demand.
Unhidea take: watch the power mix, not the chip cycle. GS expects US AI data centers to draw up to ~60% of power from gas turbines — if delays stretch, the question is who keeps the orders.
Risks: US state moratoria, order cancellations, raw-material costs pressuring margins.
Source: Goldman Sachs, 19 Nov 2026. Post-report news: NVIDIA beat FQ3 — revenue $115.8bn vs ~$109bn expected, Q4 guide ~$130bn (CNBC). Not financial advice.