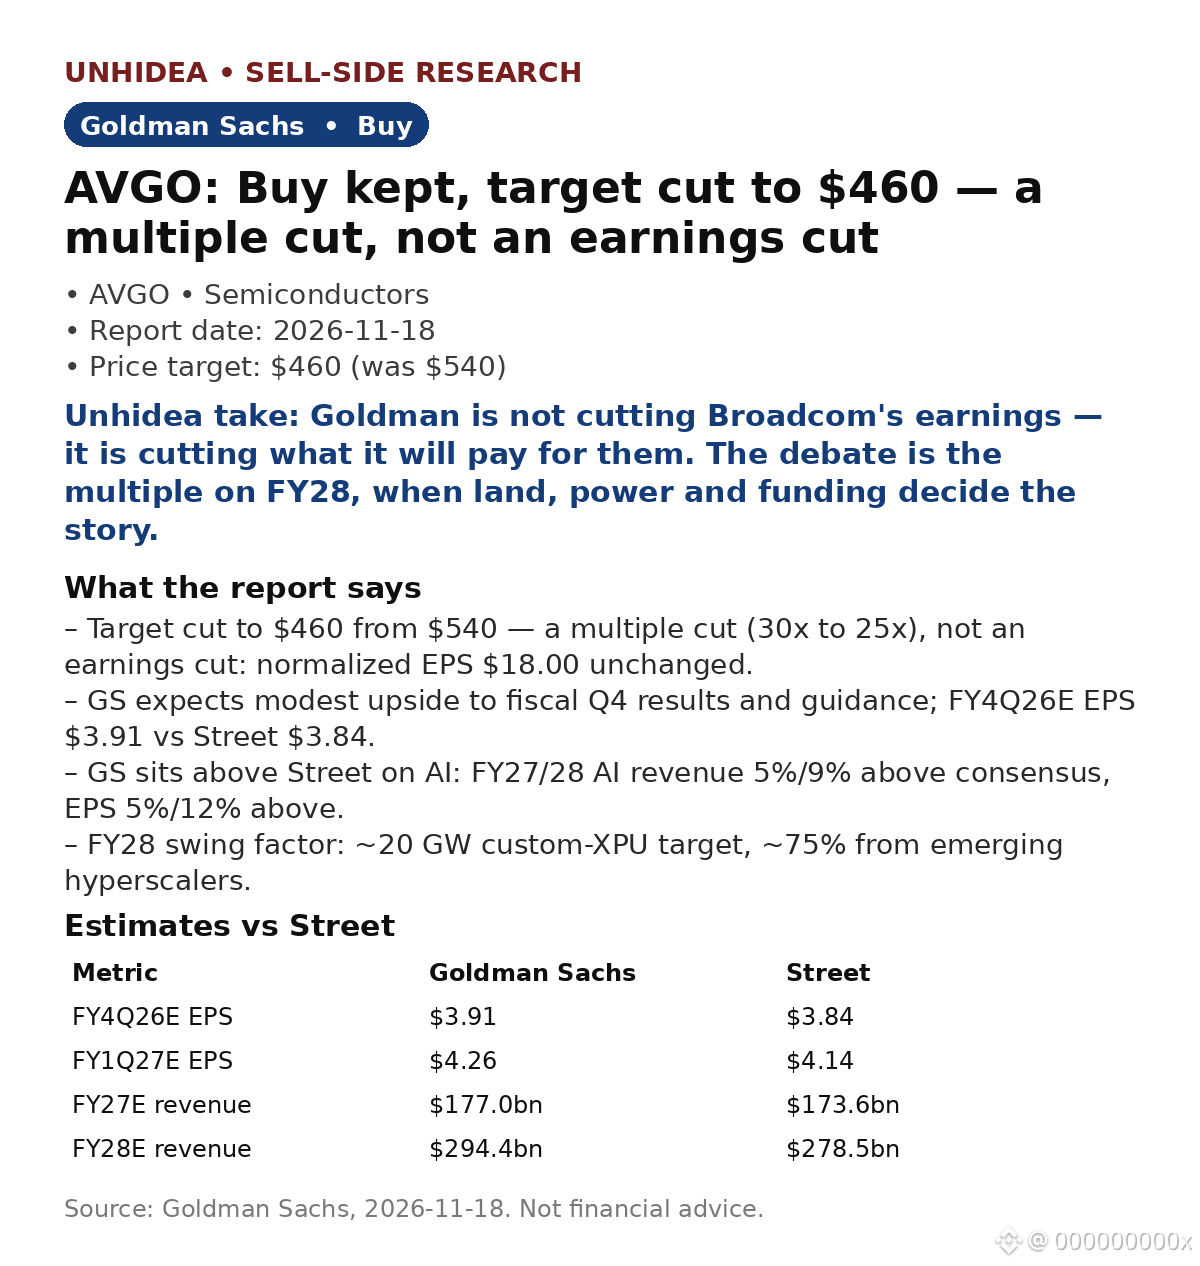$AVGO: Goldman stays Buy but cuts its target to $460 from $540 — the cut is all multiple, not earnings
- GS cuts its 12-month target to $460 (from $540) on 25x (from 30x) normalized EPS of $18.00 — unchanged. At the 17 Nov close of $341.60, that still implies 34.7% upside. Rating: Buy.
- GS expects modest upside to fiscal Q4 results and guidance: FY4Q26E EPS $3.91 vs Street $3.84 (+2%); FY1Q27E $4.26 vs $4.14 (+3%).
- GS sits above Street on AI: FY27/28 AI revenue 5%/9% above consensus, EPS 5%/12% above. FY27E revenue $177.0bn vs Street $173.6bn (+2%); FY28E $294.4bn vs $278.5bn (+6%).
- The swing factor is FY28: a ~20 GW custom-XPU target, with emerging hyperscalers ~75% of it (vs ~6.3 GW of ~10 GW in FY27). GS flags external funding, land, power and shell availability as the gating items — and says de-risking any part of the 20 GW would be a meaningful catalyst.
- Competition watch: MediaTek and others are pushing into custom XPUs; GS wants detail on the durability of Broadcom's engagements at key accounts such as Google.
Unhidea take: a target cut that leaves the Buy and the $18.00 EPS untouched is a verdict on the AI multiple, not on Broadcom's execution — the market is repricing what FY28 growth is worth, not whether FY27 ships.
Unhidea take: concentration is the real risk here — ~75% of the FY28 20 GW target rides on emerging hyperscalers whose funding GS itself questions. The upside case is a financing story as much as a silicon story.
Risks: AI infrastructure spending slowdown, custom-compute share loss, non-AI inventory digestion, VMware competition.
Source: Goldman Sachs, 18 Nov 2026. Not financial advice.
- GS cuts its 12-month target to $460 (from $540) on 25x (from 30x) normalized EPS of $18.00 — unchanged. At the 17 Nov close of $341.60, that still implies 34.7% upside. Rating: Buy.
- GS expects modest upside to fiscal Q4 results and guidance: FY4Q26E EPS $3.91 vs Street $3.84 (+2%); FY1Q27E $4.26 vs $4.14 (+3%).
- GS sits above Street on AI: FY27/28 AI revenue 5%/9% above consensus, EPS 5%/12% above. FY27E revenue $177.0bn vs Street $173.6bn (+2%); FY28E $294.4bn vs $278.5bn (+6%).
- The swing factor is FY28: a ~20 GW custom-XPU target, with emerging hyperscalers ~75% of it (vs ~6.3 GW of ~10 GW in FY27). GS flags external funding, land, power and shell availability as the gating items — and says de-risking any part of the 20 GW would be a meaningful catalyst.
- Competition watch: MediaTek and others are pushing into custom XPUs; GS wants detail on the durability of Broadcom's engagements at key accounts such as Google.
Unhidea take: a target cut that leaves the Buy and the $18.00 EPS untouched is a verdict on the AI multiple, not on Broadcom's execution — the market is repricing what FY28 growth is worth, not whether FY27 ships.
Unhidea take: concentration is the real risk here — ~75% of the FY28 20 GW target rides on emerging hyperscalers whose funding GS itself questions. The upside case is a financing story as much as a silicon story.
Risks: AI infrastructure spending slowdown, custom-compute share loss, non-AI inventory digestion, VMware competition.
Source: Goldman Sachs, 18 Nov 2026. Not financial advice.