

#007
007
1,101 مشاهدات
12 يقومون بالنقاش
رائج
جديد
·
--
مقالة
عرض الترجمة
No Interest on the Coin. A Separate Fund Is HSBC's Next Plan.IKOL Note #007
A coin for paying at more than 100,000 merchants. No interest for holding it. And HSBC's next step is a separate product: a money market fund share class that hasn't launched yet.
On October 23, HSBC launched RedCoin (RCHKD), a Hong Kong dollar stablecoin, on its PayMe app. In the coming days, more than 3.3 million PayMe users will be able to activate a wallet and use it to pay friends and shops. What the coin will never do, under Hong Kong law, is pay its holders interest. The coin, the launch rewards and the planned fund sit close together, but they are not the same thing.
【A coin built for paying】
[Documented] According to HSBC's release (Oct 23):
· RedCoin is "the bank's first stablecoin," denominated in Hong Kong dollars and issued by The Hongkong and Shanghai Banking Corporation under a stablecoin issuer licence granted by the HKMA in April.
· "In the coming days, over 3.3 million PayMe users will be able to activate a stablecoin wallet in-app" for peer-to-peer payments and payments "at more than 100,000 merchants through PayMe."
· "To celebrate the launch, exclusive PayMe transaction discounts, alongside RewardCash, will be offered."
· Later this year, HSBC plans to let customers "subscribe to tokenised investment products via HSBC RedCoin," including "a soon-to-be-launched share class of HSBC's long-running HKD money market fund."
【The rule: no interest at all】
[Documented] The HKMA's Guideline on Supervision of Licensed Stablecoin Issuers (August 2025) puts it under a heading that leaves little doubt: "Non-interest bearing."
「"Section 15 of Schedule 2 to the SO stipulates that a licensee must not pay, or permit to be paid, any interest in relation to the specified stablecoins it issues. A licensee should not pay interest or interest-like incentive in any form to specified stablecoin holders, save that a licensee may offer marketing incentives that do not amount to payment of interest." (para 2.6.1, p. 8)」
Interest is defined by how it arises from holding: any return represented to arise from holding the coins on the basis of "(i) the length of the period during which the holder holds" them, "(ii) the par value," or "(iii) the market value." Income from managing the reserve assets goes to the issuer, not to holders. (paras 2.5.3, 2.6.1, pp. 8–9) In the Guideline, "must" marks a statutory requirement and "should" the HKMA's expectation. (para 1.2)
[Analysis] The US rule in Note #005 bans issuers from paying interest or yield "solely" for holding, using or retaining a stablecoin, and much of the American fight is over that one word. Hong Kong's statute has no "solely." The HKMA then extends the ban to "interest-like" incentives, with one carve-out: marketing incentives that are not interest.
【So what are the launch rewards?】
[Documented] HSBC describes its launch offer in one sentence: "exclusive PayMe transaction discounts, alongside RewardCash." The release gives no further terms.
[Analysis] As described, the offer is tied to transactions and to the launch, not to how long or how much RedCoin someone holds, which are the tests the Guideline uses to define interest. Whether a particular offer stays on the "marketing incentive" side of the line is for the HKMA to judge, and its full terms are not in the release. What the rule does make clear is the direction: rewards for using the coin can exist; returns for holding it cannot.
【Returns live somewhere else】
[Documented] The fund route is a plan, not a product yet: HSBC says customers will be able to use RedCoin to subscribe to tokenized investment products, including the new money market fund share class, later this year.
[Analysis] Note #006 looked at the American version from the other side: SoFi keeps idle money in a tokenized deposit, which can pay interest, and converts it into a stablecoin when it's time to spend. HSBC's plan keeps the stablecoin as the payment tool and points to a fund as a place where money can earn. In both cases the coin itself pays nothing. And a fund is neither a deposit nor interest on the coin: it is an investment with its own terms and risks, and this share class has not launched.
【Before you use it】
· Redemption. The HKMA requires licensees to let holders redeem at par; valid requests must be honored "without charging an unreasonable fee" and, unless otherwise approved, processed "within one (1) business day." Reserves must be worth at least the coins outstanding at all times and kept separate from the issuer's own assets. (Guideline paras 2.2.1, 2.5.1, 3.3.1, 3.3.3) HSBC's release does not describe fees or the redemption path inside PayMe.
· The launch offer. One sentence is all that's public in the release.
· The fund. Timing, minimums, fees and risks are not yet published.
· Which chain. Not named.
· Uptake. 3.3 million is the number of PayMe users who can activate a wallet, not the number who hold RedCoin. We have no usage data.
Would payments alone give you a reason to keep a balance in this wallet? And what would you need to know before using the planned fund alongside it?
—————
Background: the HKMA granted Hong Kong's first two stablecoin issuer licences on April 10, 2026, to Anchorpoint Financial Limited and HSBC, effective that day, and reminded the public to acquire and use stablecoins "only through regulated channels." HSBC's licence number is FRS02; HSBC Digital Assets Custody holds RedCoin's safekeeping; staff pilots with nearly 100 users preceded launch. The Stablecoins Ordinance (Cap. 656) took effect on August 1, 2025.
Evidence: strong for what RedCoin is and how it can be used (HSBC's own release); strong for Hong Kong's no-interest rule and redemption standards (HKMA Guideline, quoting the Stablecoins Ordinance); the statute itself was read through the Guideline's citations, not directly. Nothing on usage, fees or the fund's terms. Not investment or legal advice; no view on the product.
Sources
1. HSBC, "HSBC RedCoin launches today" (Oct 23, 2026) — https://www.about.hsbc.com.hk/news-and-media/hsbc-redcoin-launches-today
2. HKMA, "Granting of stablecoin issuer licences" (Apr 10, 2026) — https://www.hkma.gov.hk/eng/news-and-media/press-releases/2026/04/20260410-4/
3. HKMA, Guideline on Supervision of Licensed Stablecoin Issuers (Aug 2025), paras 1.2, 2.2.1, 2.5.1, 2.5.3, 2.6.1, 3.3.1, 3.3.3 — https://www.hkma.gov.hk/media/eng/doc/key-functions/ifc/stablecoin-issuers/Guideline_on_supervision_of_licensed_stablecoin_issuers_eng.pdf
4. Hong Kong Government, Stablecoins Ordinance (Cap. 656) commencement (press release, Jun 6, 2025) — https://www.info.gov.hk/gia/general/202506/06/P2025060600275.htm
5. IKOL Notes #005 and #006 — https://x.com/2425247/status/2113155622208418105 · https://x.com/2425247/status/2113481960903549169
IKOL · AI-assisted research, human-edited. We label what is documented, reported and analyzed — and publish our corrections.
No Interest on the Coin. A Separate Fund Is HSBC's Next Plan.
IKOL Note #007
A coin for paying at more than 100,000 merchants. No interest for holding it. And HSBC's next step is a separate product: a money market fund share class that hasn't launched yet.
On October 23, HSBC launched RedCoin (RCHKD), a Hong Kong dollar stablecoin, on its PayMe app. In the coming days, more than 3.3 million PayMe users will be able to activate a wallet and use it to pay friends and shops. What the coin will never do, under Hong Kong law, is pay its holders interest. The coin, the launch rewards and the planned fund sit close together, but they are not the same thing.
【A coin built for paying】
[Documented] According to HSBC's release (Oct 23):
· RedCoin is "the bank's first stablecoin," denominated in Hong Kong dollars and issued by The Hongkong and Shanghai Banking Corporation under a stablecoin issuer licence granted by the HKMA in April.
· "In the coming days, over 3.3 million PayMe users will be able to activate a stablecoin wallet in-app" for peer-to-peer payments and payments "at more than 100,000 merchants through PayMe."
· "To celebrate the launch, exclusive PayMe transaction discounts, alongside RewardCash, will be offered."
· Later this year, HSBC plans to let customers "subscribe to tokenised investment products via HSBC RedCoin," including "a soon-to-be-launched share class of HSBC's long-running HKD money market fund."
【The rule: no interest at all】
[Documented] The HKMA's Guideline on Supervision of Licensed Stablecoin Issuers (August 2025) puts it under a heading that leaves little doubt: "Non-interest bearing."
「"Section 15 of Schedule 2 to the SO stipulates that a licensee must not pay, or permit to be paid, any interest in relation to the specified stablecoins it issues. A licensee should not pay interest or interest-like incentive in any form to specified stablecoin holders, save that a licensee may offer marketing incentives that do not amount to payment of interest." (para 2.6.1, p. 8)」
Interest is defined by how it arises from holding: any return represented to arise from holding the coins on the basis of "(i) the length of the period during which the holder holds" them, "(ii) the par value," or "(iii) the market value." Income from managing the reserve assets goes to the issuer, not to holders. (paras 2.5.3, 2.6.1, pp. 8–9) In the Guideline, "must" marks a statutory requirement and "should" the HKMA's expectation. (para 1.2)
[Analysis] The US rule in Note #005 bans issuers from paying interest or yield "solely" for holding, using or retaining a stablecoin, and much of the American fight is over that one word. Hong Kong's statute has no "solely." The HKMA then extends the ban to "interest-like" incentives, with one carve-out: marketing incentives that are not interest.
【So what are the launch rewards?】
[Documented] HSBC describes its launch offer in one sentence: "exclusive PayMe transaction discounts, alongside RewardCash." The release gives no further terms.
[Analysis] As described, the offer is tied to transactions and to the launch, not to how long or how much RedCoin someone holds, which are the tests the Guideline uses to define interest. Whether a particular offer stays on the "marketing incentive" side of the line is for the HKMA to judge, and its full terms are not in the release. What the rule does make clear is the direction: rewards for using the coin can exist; returns for holding it cannot.
【Returns live somewhere else】
[Documented] The fund route is a plan, not a product yet: HSBC says customers will be able to use RedCoin to subscribe to tokenized investment products, including the new money market fund share class, later this year.
[Analysis] Note #006 looked at the American version from the other side: SoFi keeps idle money in a tokenized deposit, which can pay interest, and converts it into a stablecoin when it's time to spend. HSBC's plan keeps the stablecoin as the payment tool and points to a fund as a place where money can earn. In both cases the coin itself pays nothing. And a fund is neither a deposit nor interest on the coin: it is an investment with its own terms and risks, and this share class has not launched.
【Before you use it】
· Redemption. The HKMA requires licensees to let holders redeem at par; valid requests must be honored "without charging an unreasonable fee" and, unless otherwise approved, processed "within one (1) business day." Reserves must be worth at least the coins outstanding at all times and kept separate from the issuer's own assets. (Guideline paras 2.2.1, 2.5.1, 3.3.1, 3.3.3) HSBC's release does not describe fees or the redemption path inside PayMe.
· The launch offer. One sentence is all that's public in the release.
· The fund. Timing, minimums, fees and risks are not yet published.
· Which chain. Not named.
· Uptake. 3.3 million is the number of PayMe users who can activate a wallet, not the number who hold RedCoin. We have no usage data.
Would payments alone give you a reason to keep a balance in this wallet? And what would you need to know before using the planned fund alongside it?
—————
Background: the HKMA granted Hong Kong's first two stablecoin issuer licences on April 10, 2026, to Anchorpoint Financial Limited and HSBC, effective that day, and reminded the public to acquire and use stablecoins "only through regulated channels." HSBC's licence number is FRS02; HSBC Digital Assets Custody holds RedCoin's safekeeping; staff pilots with nearly 100 users preceded launch. The Stablecoins Ordinance (Cap. 656) took effect on August 1, 2025.
Evidence: strong for what RedCoin is and how it can be used (HSBC's own release); strong for Hong Kong's no-interest rule and redemption standards (HKMA Guideline, quoting the Stablecoins Ordinance); the statute itself was read through the Guideline's citations, not directly. Nothing on usage, fees or the fund's terms. Not investment or legal advice; no view on the product.
Sources
1. HSBC, "HSBC RedCoin launches today" (Oct 23, 2026) — https://www.about.hsbc.com.hk/news-and-media/hsbc-redcoin-launches-today
2. HKMA, "Granting of stablecoin issuer licences" (Apr 10, 2026) — https://www.hkma.gov.hk/eng/news-and-media/press-releases/2026/04/20260410-4/
3. HKMA, Guideline on Supervision of Licensed Stablecoin Issuers (Aug 2025), paras 1.2, 2.2.1, 2.5.1, 2.5.3, 2.6.1, 3.3.1, 3.3.3 — https://www.hkma.gov.hk/media/eng/doc/key-functions/ifc/stablecoin-issuers/Guideline_on_supervision_of_licensed_stablecoin_issuers_eng.pdf
4. Hong Kong Government, Stablecoins Ordinance (Cap. 656) commencement (press release, Jun 6, 2025) — https://www.info.gov.hk/gia/general/202506/06/P2025060600275.htm
5. IKOL Notes #005 and #006 — https://x.com/2425247/status/2113155622208418105 · https://x.com/2425247/status/2113481960903549169
IKOL · AI-assisted research, human-edited. We label what is documented, reported and analyzed — and publish our corrections.
A coin for paying at more than 100,000 merchants. No interest for holding it. And HSBC's next step is a separate product: a money market fund share class that hasn't launched yet.
On October 23, HSBC launched RedCoin (RCHKD), a Hong Kong dollar stablecoin, on its PayMe app. In the coming days, more than 3.3 million PayMe users will be able to activate a wallet and use it to pay friends and shops. What the coin will never do, under Hong Kong law, is pay its holders interest. The coin, the launch rewards and the planned fund sit close together, but they are not the same thing.
【A coin built for paying】
[Documented] According to HSBC's release (Oct 23):
· RedCoin is "the bank's first stablecoin," denominated in Hong Kong dollars and issued by The Hongkong and Shanghai Banking Corporation under a stablecoin issuer licence granted by the HKMA in April.
· "In the coming days, over 3.3 million PayMe users will be able to activate a stablecoin wallet in-app" for peer-to-peer payments and payments "at more than 100,000 merchants through PayMe."
· "To celebrate the launch, exclusive PayMe transaction discounts, alongside RewardCash, will be offered."
· Later this year, HSBC plans to let customers "subscribe to tokenised investment products via HSBC RedCoin," including "a soon-to-be-launched share class of HSBC's long-running HKD money market fund."
【The rule: no interest at all】
[Documented] The HKMA's Guideline on Supervision of Licensed Stablecoin Issuers (August 2025) puts it under a heading that leaves little doubt: "Non-interest bearing."
「"Section 15 of Schedule 2 to the SO stipulates that a licensee must not pay, or permit to be paid, any interest in relation to the specified stablecoins it issues. A licensee should not pay interest or interest-like incentive in any form to specified stablecoin holders, save that a licensee may offer marketing incentives that do not amount to payment of interest." (para 2.6.1, p. 8)」
Interest is defined by how it arises from holding: any return represented to arise from holding the coins on the basis of "(i) the length of the period during which the holder holds" them, "(ii) the par value," or "(iii) the market value." Income from managing the reserve assets goes to the issuer, not to holders. (paras 2.5.3, 2.6.1, pp. 8–9) In the Guideline, "must" marks a statutory requirement and "should" the HKMA's expectation. (para 1.2)
[Analysis] The US rule in Note #005 bans issuers from paying interest or yield "solely" for holding, using or retaining a stablecoin, and much of the American fight is over that one word. Hong Kong's statute has no "solely." The HKMA then extends the ban to "interest-like" incentives, with one carve-out: marketing incentives that are not interest.
【So what are the launch rewards?】
[Documented] HSBC describes its launch offer in one sentence: "exclusive PayMe transaction discounts, alongside RewardCash." The release gives no further terms.
[Analysis] As described, the offer is tied to transactions and to the launch, not to how long or how much RedCoin someone holds, which are the tests the Guideline uses to define interest. Whether a particular offer stays on the "marketing incentive" side of the line is for the HKMA to judge, and its full terms are not in the release. What the rule does make clear is the direction: rewards for using the coin can exist; returns for holding it cannot.
【Returns live somewhere else】
[Documented] The fund route is a plan, not a product yet: HSBC says customers will be able to use RedCoin to subscribe to tokenized investment products, including the new money market fund share class, later this year.
[Analysis] Note #006 looked at the American version from the other side: SoFi keeps idle money in a tokenized deposit, which can pay interest, and converts it into a stablecoin when it's time to spend. HSBC's plan keeps the stablecoin as the payment tool and points to a fund as a place where money can earn. In both cases the coin itself pays nothing. And a fund is neither a deposit nor interest on the coin: it is an investment with its own terms and risks, and this share class has not launched.
【Before you use it】
· Redemption. The HKMA requires licensees to let holders redeem at par; valid requests must be honored "without charging an unreasonable fee" and, unless otherwise approved, processed "within one (1) business day." Reserves must be worth at least the coins outstanding at all times and kept separate from the issuer's own assets. (Guideline paras 2.2.1, 2.5.1, 3.3.1, 3.3.3) HSBC's release does not describe fees or the redemption path inside PayMe.
· The launch offer. One sentence is all that's public in the release.
· The fund. Timing, minimums, fees and risks are not yet published.
· Which chain. Not named.
· Uptake. 3.3 million is the number of PayMe users who can activate a wallet, not the number who hold RedCoin. We have no usage data.
Would payments alone give you a reason to keep a balance in this wallet? And what would you need to know before using the planned fund alongside it?
—————
Background: the HKMA granted Hong Kong's first two stablecoin issuer licences on April 10, 2026, to Anchorpoint Financial Limited and HSBC, effective that day, and reminded the public to acquire and use stablecoins "only through regulated channels." HSBC's licence number is FRS02; HSBC Digital Assets Custody holds RedCoin's safekeeping; staff pilots with nearly 100 users preceded launch. The Stablecoins Ordinance (Cap. 656) took effect on August 1, 2025.
Evidence: strong for what RedCoin is and how it can be used (HSBC's own release); strong for Hong Kong's no-interest rule and redemption standards (HKMA Guideline, quoting the Stablecoins Ordinance); the statute itself was read through the Guideline's citations, not directly. Nothing on usage, fees or the fund's terms. Not investment or legal advice; no view on the product.
Sources
1. HSBC, "HSBC RedCoin launches today" (Oct 23, 2026) — https://www.about.hsbc.com.hk/news-and-media/hsbc-redcoin-launches-today
2. HKMA, "Granting of stablecoin issuer licences" (Apr 10, 2026) — https://www.hkma.gov.hk/eng/news-and-media/press-releases/2026/04/20260410-4/
3. HKMA, Guideline on Supervision of Licensed Stablecoin Issuers (Aug 2025), paras 1.2, 2.2.1, 2.5.1, 2.5.3, 2.6.1, 3.3.1, 3.3.3 — https://www.hkma.gov.hk/media/eng/doc/key-functions/ifc/stablecoin-issuers/Guideline_on_supervision_of_licensed_stablecoin_issuers_eng.pdf
4. Hong Kong Government, Stablecoins Ordinance (Cap. 656) commencement (press release, Jun 6, 2025) — https://www.info.gov.hk/gia/general/202506/06/P2025060600275.htm
5. IKOL Notes #005 and #006 — https://x.com/2425247/status/2113155622208418105 · https://x.com/2425247/status/2113481960903549169
IKOL · AI-assisted research, human-edited. We label what is documented, reported and analyzed — and publish our corrections.
22
·
--
【مراقبة البنية #007|BTC، إطار 4 ساعات】اتساع القمم والقيعان معًا، والسعر عالق في النصف السفلي من النطاق
مراجعة ما سبق: نطاق BTC الذي حددته أمس عند 20:00، وهو 81,048–83,390، ما زال السعر الحالي 81,908 داخله، ولم يلامس أيًّا من الحدين.
عند 08:00، السعر الحالي 81,908، والتغير خلال 24 ساعة -0.21%، وحجم التداول 10.562 مليار U، والنطاق اليومي 83,158 / 81,701.
① البنية: خلال آخر 30 شمعة، ارتفعت القمم وانخفضت القيعان، ما يشكل مثلثًا متسعًا. نطاق التداول 80,841–83,961، وعرضه 3.9%، والسعر الحالي عند المئين 34، أي في النصف السفلي من النطاق. يقع MA25 عند 81,810، أسفل السعر الحالي مباشرةً، وميله خلال آخر 5 شموع +0.03%، أي إنه شبه أفقي.
② الحجم والسعر: حجم التداول في آخر 10 شموع يعادل 0.89 من حجم التداول في الشموع الـ30 السابقة، وهو قريب من المستويات السابقة، دون زيادة ملحوظة. أغلقت 5 من آخر 10 شموع على ارتفاع؛ أي إن الشموع الصاعدة والهابطة متساوية، ما يعكس شدًّا وجذبًا.
③ توافق المؤشرات: في المنطقة العلوية 82,033–82,599، يتطابق مستوى فيبوناتشي 0.618 (82,033) مع القمة السابقة (82,599)؛ وفي المنطقة السفلية 81,320–81,810، يتداخل MA25 (81,810) مع القاع السابق (81,320). كلا الجانبين مدعوم بمصدرين، وهذا أكثر موثوقية من الاعتماد على خط واحد.
④ وضع التمويل: معدل التمويل +0.0092%، أي إن مراكز الشراء تدفع؛ تغير حجم المراكز خلال 7 شموع من إطار 4 ساعات +1.69%، ما يعني أن حجم المراكز يتزايد؛ ونسبة حسابات الشراء إلى البيع 1.62. السعر لم يتحرك كثيرًا، بينما تتراكم المراكز.
نطاق المراقبة: أعلى 82,033–83,017، وأسفل 80,829–81,810.
منظور إطار الساعة: تحرك السعر خلال آخر 12 ساعة بين 81,701–82,744، وكان الإغلاق الأخير عند المئين 20، قريبًا من الحد الأدنى لهذه الحركة.
شرط إبطال التحليل: إذا أغلق إطار 4 ساعات فوق 83,017 أو دون 80,829، يُلغى هذا التقييم.
برأيي، في المثلث المتسع، الأجدر بالمراقبة ليس الجزء الأوسط، بل عدد مرات ملامسة الحدين العلوي والسفلي فعليًا. هل حددت مستوى فيبوناتشي 82,033 في الأعلى وMA25 عند 81,810 في الأسفل في الموضعين نفسيهما؟
هذا رصد للبنية استنادًا إلى بيانات عامة، ولا يشكل توصية بالتداول. الأرباح والخسائر على مسؤوليتك.
$BTC
#技术分析 #合约交易 #بيتكوين
【مراقبة البنية #007|BTC، إطار 4 ساعات】اتساع القمم والقيعان معًا، والسعر عالق في النصف السفلي من النطاق
مراجعة ما سبق: نطاق BTC الذي حددته أمس عند 20:00، وهو 81,048–83,390، ما زال السعر الحالي 81,908 داخله، ولم يلامس أيًّا من الحدين.
عند 08:00، السعر الحالي 81,908، والتغير خلال 24 ساعة -0.21%، وحجم التداول 10.562 مليار U، والنطاق اليومي 83,158 / 81,701.
① البنية: خلال آخر 30 شمعة، ارتفعت القمم وانخفضت القيعان، ما يشكل مثلثًا متسعًا. نطاق التداول 80,841–83,961، وعرضه 3.9%، والسعر الحالي عند المئين 34، أي في النصف السفلي من النطاق. يقع MA25 عند 81,810، أسفل السعر الحالي مباشرةً، وميله خلال آخر 5 شموع +0.03%، أي إنه شبه أفقي.
② الحجم والسعر: حجم التداول في آخر 10 شموع يعادل 0.89 من حجم التداول في الشموع الـ30 السابقة، وهو قريب من المستويات السابقة، دون زيادة ملحوظة. أغلقت 5 من آخر 10 شموع على ارتفاع؛ أي إن الشموع الصاعدة والهابطة متساوية، ما يعكس شدًّا وجذبًا.
③ توافق المؤشرات: في المنطقة العلوية 82,033–82,599، يتطابق مستوى فيبوناتشي 0.618 (82,033) مع القمة السابقة (82,599)؛ وفي المنطقة السفلية 81,320–81,810، يتداخل MA25 (81,810) مع القاع السابق (81,320). كلا الجانبين مدعوم بمصدرين، وهذا أكثر موثوقية من الاعتماد على خط واحد.
④ وضع التمويل: معدل التمويل +0.0092%، أي إن مراكز الشراء تدفع؛ تغير حجم المراكز خلال 7 شموع من إطار 4 ساعات +1.69%، ما يعني أن حجم المراكز يتزايد؛ ونسبة حسابات الشراء إلى البيع 1.62. السعر لم يتحرك كثيرًا، بينما تتراكم المراكز.
نطاق المراقبة: أعلى 82,033–83,017، وأسفل 80,829–81,810.
منظور إطار الساعة: تحرك السعر خلال آخر 12 ساعة بين 81,701–82,744، وكان الإغلاق الأخير عند المئين 20، قريبًا من الحد الأدنى لهذه الحركة.
شرط إبطال التحليل: إذا أغلق إطار 4 ساعات فوق 83,017 أو دون 80,829، يُلغى هذا التقييم.
برأيي، في المثلث المتسع، الأجدر بالمراقبة ليس الجزء الأوسط، بل عدد مرات ملامسة الحدين العلوي والسفلي فعليًا. هل حددت مستوى فيبوناتشي 82,033 في الأعلى وMA25 عند 81,810 في الأسفل في الموضعين نفسيهما؟
هذا رصد للبنية استنادًا إلى بيانات عامة، ولا يشكل توصية بالتداول. الأرباح والخسائر على مسؤوليتك.
$BTC
#技术分析 #合约交易 #بيتكوين
مراجعة ما سبق: نطاق BTC الذي حددته أمس عند 20:00، وهو 81,048–83,390، ما زال السعر الحالي 81,908 داخله، ولم يلامس أيًّا من الحدين.
عند 08:00، السعر الحالي 81,908، والتغير خلال 24 ساعة -0.21%، وحجم التداول 10.562 مليار U، والنطاق اليومي 83,158 / 81,701.
① البنية: خلال آخر 30 شمعة، ارتفعت القمم وانخفضت القيعان، ما يشكل مثلثًا متسعًا. نطاق التداول 80,841–83,961، وعرضه 3.9%، والسعر الحالي عند المئين 34، أي في النصف السفلي من النطاق. يقع MA25 عند 81,810، أسفل السعر الحالي مباشرةً، وميله خلال آخر 5 شموع +0.03%، أي إنه شبه أفقي.
② الحجم والسعر: حجم التداول في آخر 10 شموع يعادل 0.89 من حجم التداول في الشموع الـ30 السابقة، وهو قريب من المستويات السابقة، دون زيادة ملحوظة. أغلقت 5 من آخر 10 شموع على ارتفاع؛ أي إن الشموع الصاعدة والهابطة متساوية، ما يعكس شدًّا وجذبًا.
③ توافق المؤشرات: في المنطقة العلوية 82,033–82,599، يتطابق مستوى فيبوناتشي 0.618 (82,033) مع القمة السابقة (82,599)؛ وفي المنطقة السفلية 81,320–81,810، يتداخل MA25 (81,810) مع القاع السابق (81,320). كلا الجانبين مدعوم بمصدرين، وهذا أكثر موثوقية من الاعتماد على خط واحد.
④ وضع التمويل: معدل التمويل +0.0092%، أي إن مراكز الشراء تدفع؛ تغير حجم المراكز خلال 7 شموع من إطار 4 ساعات +1.69%، ما يعني أن حجم المراكز يتزايد؛ ونسبة حسابات الشراء إلى البيع 1.62. السعر لم يتحرك كثيرًا، بينما تتراكم المراكز.
نطاق المراقبة: أعلى 82,033–83,017، وأسفل 80,829–81,810.
منظور إطار الساعة: تحرك السعر خلال آخر 12 ساعة بين 81,701–82,744، وكان الإغلاق الأخير عند المئين 20، قريبًا من الحد الأدنى لهذه الحركة.
شرط إبطال التحليل: إذا أغلق إطار 4 ساعات فوق 83,017 أو دون 80,829، يُلغى هذا التقييم.
برأيي، في المثلث المتسع، الأجدر بالمراقبة ليس الجزء الأوسط، بل عدد مرات ملامسة الحدين العلوي والسفلي فعليًا. هل حددت مستوى فيبوناتشي 82,033 في الأعلى وMA25 عند 81,810 في الأسفل في الموضعين نفسيهما؟
هذا رصد للبنية استنادًا إلى بيانات عامة، ولا يشكل توصية بالتداول. الأرباح والخسائر على مسؤوليتك.
$BTC
#技术分析 #合约交易 #بيتكوين
90
·
--
#广场运营手记 #007: خلاصة الأسبوع الأول — النمط الوحيد الذي أثبت فعاليته بالأرقام
اليوم هو اليوم السابع من هذه السلسلة، وقد أكملت أسبوعًا من النشر المتواصل. دخلت للتو إلى صفحتي وسحبت أحدث البيانات، وبعد أسبوع من النشر اكتشفت بعض الأمور التي لا بد من تدوينها.
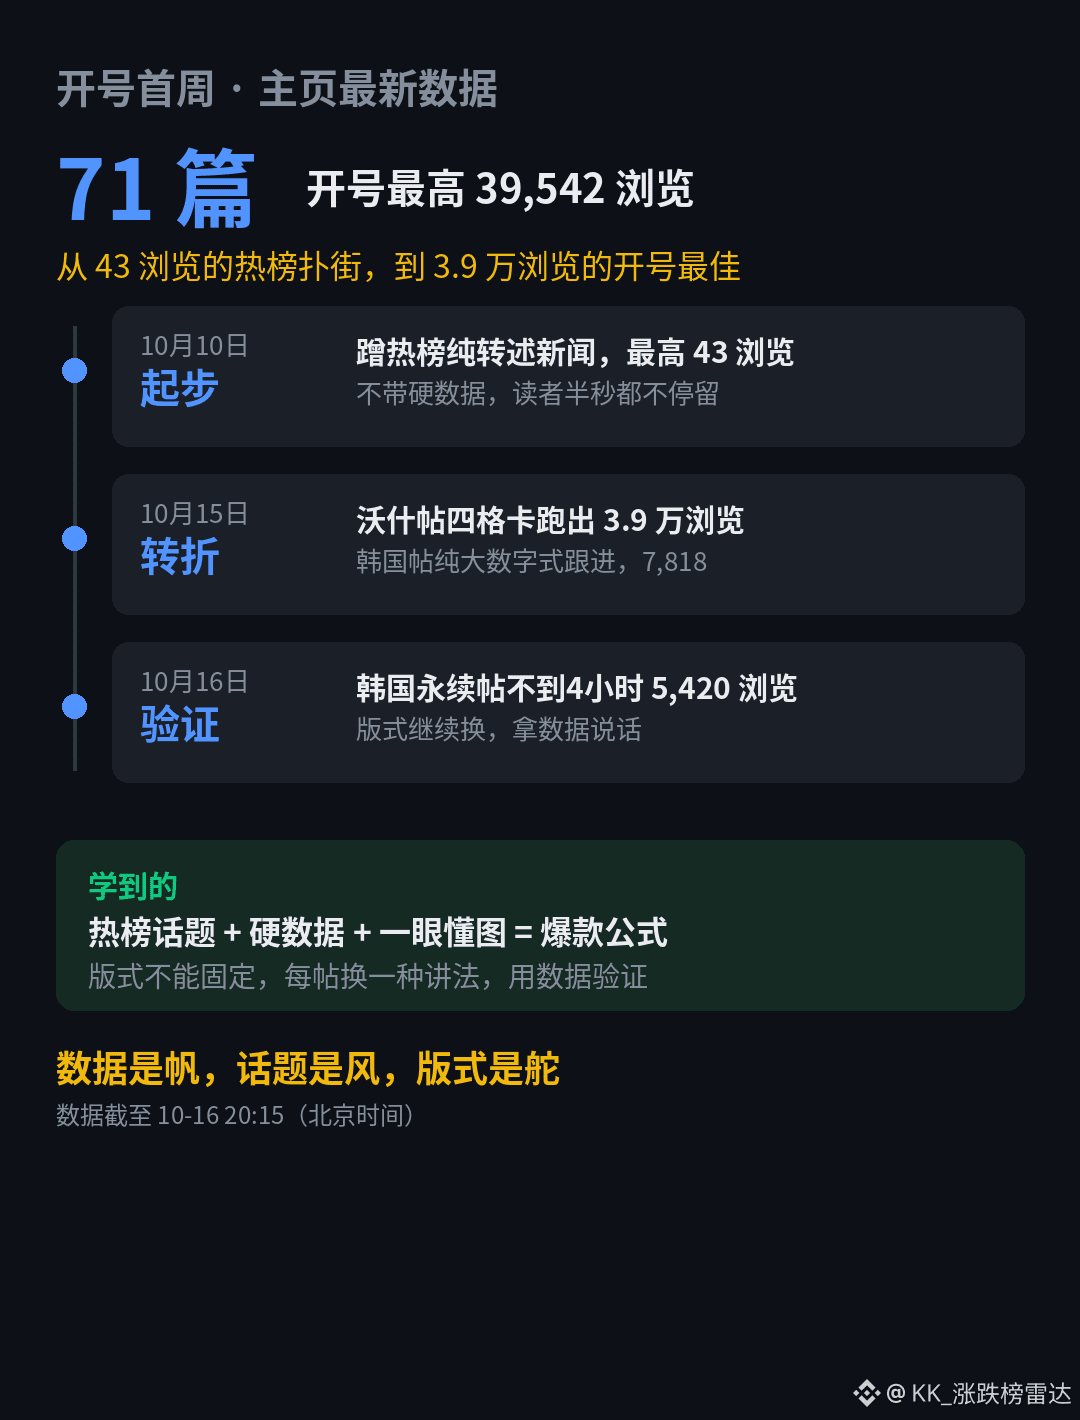
لنبدأ بالأمر الأكثر وضوحًا: المنشور الأعلى مشاهدة منذ أن أطلقت حسابي ليس المنشور الكوري الذي كنت فخورًا به بالأمس، بل منشور كدت أتجاهله — منشور ووش بتاريخ 15 أكتوبر (هل سيتم تمزيق «سيناريو» الاحتياطي الفيدرالي؟)، وقد حقق 39,542 مشاهدة و12 إعجابًا و5 تعليقات. أما المنشور عن حجب كوريا مواقع 27 منصة تداول، فحقق 7,818 مشاهدة و3 إعجابات، وجاء في المركز الثاني. ومنشور العقود الدائمة الكورية الذي نشرته بعد ظهر اليوم حقق 5,420 مشاهدة في أقل من 4 ساعات، وما زال يكتسب زخمًا تدريجيًا. أما الملخص الصباحي، فما زال ثابتًا عند نحو 1,000 مشاهدة يوميًا.
عندما أضع هذه المنشورات جنبًا إلى جنب، تتضح الخلاصة أكثر. استخدم منشور ووش تصميمًا من أربع خانات: الماضي/الحاضر/المستقبل/الأثر، يلخص الفكرة كلها في صورة واحدة. كنت متحمسًا جدًا حين حقق هذا المنشور انتشارًا واسعًا، لكنني تعلمت اليوم درسًا إضافيًا: لا تحوّل أي تصميم إلى قالب ثابت. انتشر منشور ووش بتصميم الخانات الأربع، فغيّرت أسلوبي في المنشور التالي إلى أرقام كبيرة فقط (منشور حجب المواقع الكورية، 7,818 مشاهدة)، واليوم استخدمت مزيجًا من الأرقام الكبيرة والتفاصيل (منشور العقود الدائمة الكورية، وقد بدأ يكتسب زخمًا عند 5,420 مشاهدة). القراء يملّون؛ فهناك حسابات كثيرة في الساحة تكرر التصميم نفسه حتى تستهلكه، ويعرف المستخدم من النظرة الأولى ما الذي سيظهر في الإطار التالي، فيمرر المنشور مباشرة. استراتيجيتي هي تغيير الأسلوب في كل منشور، واستخدام البيانات لاختبار ما ينجح فعلًا، بدلًا من استخلاص حكم من منشور واحد واسع الانتشار.
ولنتحدث عن التجارب والمحاولات خلال الأيام السبعة الماضية. في الأيام الأولى، أردت أنا أيضًا ركوب موجة المواضيع الرائجة. نشرت 3 منشورات، ولم يتجاوز أفضلها 43 مشاهدة — كانت مجرد إعادة سرد للأخبار، بلا بيانات خاصة بي ولا زاوية مختلفة، ففشلت فشلًا ذريعًا. كانت هذه الأيام السبعة في الواقع دورة كاملة من التجربة والخطأ: بدأت معتقدًا أن متابعة الموضوع الرائج تكفي، لكن اتضح أن القراء لا يتوقفون حتى لنصف ثانية إن لم يتضمن المنشور بيانات قوية؛ وفي المنتصف، تكرر فشلي حتى كدت أشك في أن هذا المسار لا يجدي، لكن الملخص الصباحي ظل ثابتًا، ومنحني الثقة لمواصلة التجربة؛ أما نقطة التحول فكانت في 15 أكتوبر، حين جمعت المنشورات الكورية بين «موضوع رائج + بيانات قوية + رسم يسهل فهمه من النظرة الأولى»، فحققت 7,818 مشاهدة، بينما دفع منشور ووش الرقم مباشرة إلى 39 ألفًا.
وهناك درس آخر تعلمته بعد إخفاق: الإفراط العشوائي في إضافة الوسوم قد يؤدي إلى معاقبتك من حيث الوصول. يجب أن يكون المحتوى والوسوم عن الموضوع نفسه؛ لا تضع وسمًا إلا إذا كان مناسبًا فعلًا.
الأسبوع المقبل سأركز على 3 أمور: مواصلة متابعة المواضيع الرائجة وإرفاق الصور بها، وتغيير الأسلوب في كل منشور واختباره طوال الأسبوع؛ الاستمرار في نشر الملخص الصباحي يوميًا دون تراجع، فهو أكثر ركائز الحساب ثباتًا كل يوم؛ والامتناع عن نشر المواضيع الرائجة التي لا تتضمن بيانات قوية — فتكلفة المنشور الرديء ليست إهدار فرصة نشر واحدة، بل تآكل ثقة القراء بهذا الحساب.
7 أيام، 71 منشورًا، من إخفاق عند 43 مشاهدة إلى أفضل منشور منذ إطلاق الحساب، محققًا 39 ألف مشاهدة. ما زلت مدونًا صغيرًا، لكن الطريق يتضح أمامي أكثر فأكثر: البيانات هي الشراع، والموضوع هو الريح، والتصميم هو الدفة.
هل جربتم في الساحة أن تستخدموا «تصميمًا مختلفًا لكل منشور»؟ شاركونا في التعليقات.
$BTC $ETH
#广场运营手记 #007: خلاصة الأسبوع الأول — النمط الوحيد الذي أثبت فعاليته بالأرقام
اليوم هو اليوم السابع من هذه السلسلة، وقد أكملت أسبوعًا من النشر المتواصل. دخلت للتو إلى صفحتي وسحبت أحدث البيانات، وبعد أسبوع من النشر اكتشفت بعض الأمور التي لا بد من تدوينها.
لنبدأ بالأمر الأكثر وضوحًا: المنشور الأعلى مشاهدة منذ أن أطلقت حسابي ليس المنشور الكوري الذي كنت فخورًا به بالأمس، بل منشور كدت أتجاهله — منشور ووش بتاريخ 15 أكتوبر (هل سيتم تمزيق «سيناريو» الاحتياطي الفيدرالي؟)، وقد حقق 39,542 مشاهدة و12 إعجابًا و5 تعليقات. أما المنشور عن حجب كوريا مواقع 27 منصة تداول، فحقق 7,818 مشاهدة و3 إعجابات، وجاء في المركز الثاني. ومنشور العقود الدائمة الكورية الذي نشرته بعد ظهر اليوم حقق 5,420 مشاهدة في أقل من 4 ساعات، وما زال يكتسب زخمًا تدريجيًا. أما الملخص الصباحي، فما زال ثابتًا عند نحو 1,000 مشاهدة يوميًا.
عندما أضع هذه المنشورات جنبًا إلى جنب، تتضح الخلاصة أكثر. استخدم منشور ووش تصميمًا من أربع خانات: الماضي/الحاضر/المستقبل/الأثر، يلخص الفكرة كلها في صورة واحدة. كنت متحمسًا جدًا حين حقق هذا المنشور انتشارًا واسعًا، لكنني تعلمت اليوم درسًا إضافيًا: لا تحوّل أي تصميم إلى قالب ثابت. انتشر منشور ووش بتصميم الخانات الأربع، فغيّرت أسلوبي في المنشور التالي إلى أرقام كبيرة فقط (منشور حجب المواقع الكورية، 7,818 مشاهدة)، واليوم استخدمت مزيجًا من الأرقام الكبيرة والتفاصيل (منشور العقود الدائمة الكورية، وقد بدأ يكتسب زخمًا عند 5,420 مشاهدة). القراء يملّون؛ فهناك حسابات كثيرة في الساحة تكرر التصميم نفسه حتى تستهلكه، ويعرف المستخدم من النظرة الأولى ما الذي سيظهر في الإطار التالي، فيمرر المنشور مباشرة. استراتيجيتي هي تغيير الأسلوب في كل منشور، واستخدام البيانات لاختبار ما ينجح فعلًا، بدلًا من استخلاص حكم من منشور واحد واسع الانتشار.
ولنتحدث عن التجارب والمحاولات خلال الأيام السبعة الماضية. في الأيام الأولى، أردت أنا أيضًا ركوب موجة المواضيع الرائجة. نشرت 3 منشورات، ولم يتجاوز أفضلها 43 مشاهدة — كانت مجرد إعادة سرد للأخبار، بلا بيانات خاصة بي ولا زاوية مختلفة، ففشلت فشلًا ذريعًا. كانت هذه الأيام السبعة في الواقع دورة كاملة من التجربة والخطأ: بدأت معتقدًا أن متابعة الموضوع الرائج تكفي، لكن اتضح أن القراء لا يتوقفون حتى لنصف ثانية إن لم يتضمن المنشور بيانات قوية؛ وفي المنتصف، تكرر فشلي حتى كدت أشك في أن هذا المسار لا يجدي، لكن الملخص الصباحي ظل ثابتًا، ومنحني الثقة لمواصلة التجربة؛ أما نقطة التحول فكانت في 15 أكتوبر، حين جمعت المنشورات الكورية بين «موضوع رائج + بيانات قوية + رسم يسهل فهمه من النظرة الأولى»، فحققت 7,818 مشاهدة، بينما دفع منشور ووش الرقم مباشرة إلى 39 ألفًا.
وهناك درس آخر تعلمته بعد إخفاق: الإفراط العشوائي في إضافة الوسوم قد يؤدي إلى معاقبتك من حيث الوصول. يجب أن يكون المحتوى والوسوم عن الموضوع نفسه؛ لا تضع وسمًا إلا إذا كان مناسبًا فعلًا.
الأسبوع المقبل سأركز على 3 أمور: مواصلة متابعة المواضيع الرائجة وإرفاق الصور بها، وتغيير الأسلوب في كل منشور واختباره طوال الأسبوع؛ الاستمرار في نشر الملخص الصباحي يوميًا دون تراجع، فهو أكثر ركائز الحساب ثباتًا كل يوم؛ والامتناع عن نشر المواضيع الرائجة التي لا تتضمن بيانات قوية — فتكلفة المنشور الرديء ليست إهدار فرصة نشر واحدة، بل تآكل ثقة القراء بهذا الحساب.
7 أيام، 71 منشورًا، من إخفاق عند 43 مشاهدة إلى أفضل منشور منذ إطلاق الحساب، محققًا 39 ألف مشاهدة. ما زلت مدونًا صغيرًا، لكن الطريق يتضح أمامي أكثر فأكثر: البيانات هي الشراع، والموضوع هو الريح، والتصميم هو الدفة.
هل جربتم في الساحة أن تستخدموا «تصميمًا مختلفًا لكل منشور»؟ شاركونا في التعليقات.
$BTC $ETH
اليوم هو اليوم السابع من هذه السلسلة، وقد أكملت أسبوعًا من النشر المتواصل. دخلت للتو إلى صفحتي وسحبت أحدث البيانات، وبعد أسبوع من النشر اكتشفت بعض الأمور التي لا بد من تدوينها.
لنبدأ بالأمر الأكثر وضوحًا: المنشور الأعلى مشاهدة منذ أن أطلقت حسابي ليس المنشور الكوري الذي كنت فخورًا به بالأمس، بل منشور كدت أتجاهله — منشور ووش بتاريخ 15 أكتوبر (هل سيتم تمزيق «سيناريو» الاحتياطي الفيدرالي؟)، وقد حقق 39,542 مشاهدة و12 إعجابًا و5 تعليقات. أما المنشور عن حجب كوريا مواقع 27 منصة تداول، فحقق 7,818 مشاهدة و3 إعجابات، وجاء في المركز الثاني. ومنشور العقود الدائمة الكورية الذي نشرته بعد ظهر اليوم حقق 5,420 مشاهدة في أقل من 4 ساعات، وما زال يكتسب زخمًا تدريجيًا. أما الملخص الصباحي، فما زال ثابتًا عند نحو 1,000 مشاهدة يوميًا.
عندما أضع هذه المنشورات جنبًا إلى جنب، تتضح الخلاصة أكثر. استخدم منشور ووش تصميمًا من أربع خانات: الماضي/الحاضر/المستقبل/الأثر، يلخص الفكرة كلها في صورة واحدة. كنت متحمسًا جدًا حين حقق هذا المنشور انتشارًا واسعًا، لكنني تعلمت اليوم درسًا إضافيًا: لا تحوّل أي تصميم إلى قالب ثابت. انتشر منشور ووش بتصميم الخانات الأربع، فغيّرت أسلوبي في المنشور التالي إلى أرقام كبيرة فقط (منشور حجب المواقع الكورية، 7,818 مشاهدة)، واليوم استخدمت مزيجًا من الأرقام الكبيرة والتفاصيل (منشور العقود الدائمة الكورية، وقد بدأ يكتسب زخمًا عند 5,420 مشاهدة). القراء يملّون؛ فهناك حسابات كثيرة في الساحة تكرر التصميم نفسه حتى تستهلكه، ويعرف المستخدم من النظرة الأولى ما الذي سيظهر في الإطار التالي، فيمرر المنشور مباشرة. استراتيجيتي هي تغيير الأسلوب في كل منشور، واستخدام البيانات لاختبار ما ينجح فعلًا، بدلًا من استخلاص حكم من منشور واحد واسع الانتشار.
ولنتحدث عن التجارب والمحاولات خلال الأيام السبعة الماضية. في الأيام الأولى، أردت أنا أيضًا ركوب موجة المواضيع الرائجة. نشرت 3 منشورات، ولم يتجاوز أفضلها 43 مشاهدة — كانت مجرد إعادة سرد للأخبار، بلا بيانات خاصة بي ولا زاوية مختلفة، ففشلت فشلًا ذريعًا. كانت هذه الأيام السبعة في الواقع دورة كاملة من التجربة والخطأ: بدأت معتقدًا أن متابعة الموضوع الرائج تكفي، لكن اتضح أن القراء لا يتوقفون حتى لنصف ثانية إن لم يتضمن المنشور بيانات قوية؛ وفي المنتصف، تكرر فشلي حتى كدت أشك في أن هذا المسار لا يجدي، لكن الملخص الصباحي ظل ثابتًا، ومنحني الثقة لمواصلة التجربة؛ أما نقطة التحول فكانت في 15 أكتوبر، حين جمعت المنشورات الكورية بين «موضوع رائج + بيانات قوية + رسم يسهل فهمه من النظرة الأولى»، فحققت 7,818 مشاهدة، بينما دفع منشور ووش الرقم مباشرة إلى 39 ألفًا.
وهناك درس آخر تعلمته بعد إخفاق: الإفراط العشوائي في إضافة الوسوم قد يؤدي إلى معاقبتك من حيث الوصول. يجب أن يكون المحتوى والوسوم عن الموضوع نفسه؛ لا تضع وسمًا إلا إذا كان مناسبًا فعلًا.
الأسبوع المقبل سأركز على 3 أمور: مواصلة متابعة المواضيع الرائجة وإرفاق الصور بها، وتغيير الأسلوب في كل منشور واختباره طوال الأسبوع؛ الاستمرار في نشر الملخص الصباحي يوميًا دون تراجع، فهو أكثر ركائز الحساب ثباتًا كل يوم؛ والامتناع عن نشر المواضيع الرائجة التي لا تتضمن بيانات قوية — فتكلفة المنشور الرديء ليست إهدار فرصة نشر واحدة، بل تآكل ثقة القراء بهذا الحساب.
7 أيام، 71 منشورًا، من إخفاق عند 43 مشاهدة إلى أفضل منشور منذ إطلاق الحساب، محققًا 39 ألف مشاهدة. ما زلت مدونًا صغيرًا، لكن الطريق يتضح أمامي أكثر فأكثر: البيانات هي الشراع، والموضوع هو الريح، والتصميم هو الدفة.
هل جربتم في الساحة أن تستخدموا «تصميمًا مختلفًا لكل منشور»؟ شاركونا في التعليقات.
$BTC $ETH
175
·
--
#007
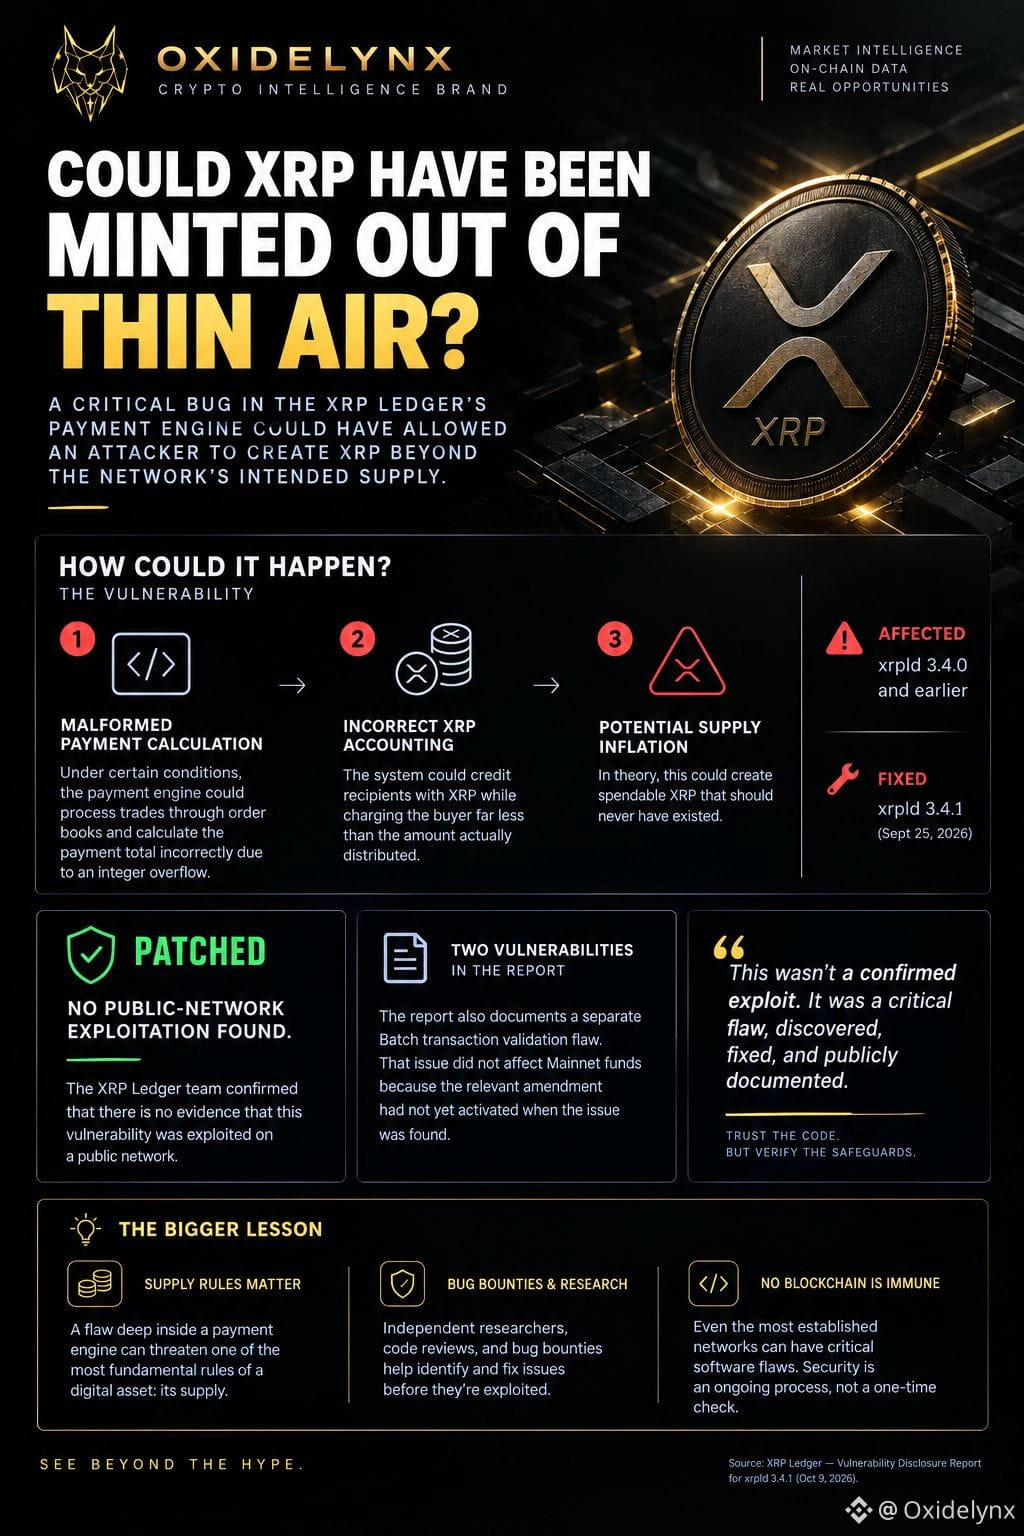
هل كان من الممكن إنشاء XRP من العدم؟
كان من الممكن نظريًا أن يسمح خلل خطير في محرك المدفوعات في XRP Ledger للمهاجمين بإنشاء XRP قابل للإنفاق يتجاوز المعروض المحدد.
🔎 ماذا حدث؟
ربما كان هذا الخلل موجودًا منذ عام 2015. وصدر إصلاح له في xrpld 3.4.1 بتاريخ 25 سبتمبر 2026. وأفاد الفريق بعدم وجود أي دليل على استغلاله على شبكة عامة.
⚠️ النقطة الأساسية: اكتُشفت ثغرة خطيرة، لكن لا يوجد استغلال مؤكد.
حتى سلاسل الكتل الراسخة تحتاج إلى مراجعات أمنية مستمرة.
ثق بالكود. وتحقق من إجراءات الحماية.
انظر إلى ما وراء الضجة.
#XRP #CryptoSecurity #Blockchain #OXIDELYNX
#007
هل كان من الممكن إنشاء XRP من العدم؟
كان من الممكن نظريًا أن يسمح خلل خطير في محرك المدفوعات في XRP Ledger للمهاجمين بإنشاء XRP قابل للإنفاق يتجاوز المعروض المحدد.
🔎 ماذا حدث؟
ربما كان هذا الخلل موجودًا منذ عام 2015. وصدر إصلاح له في xrpld 3.4.1 بتاريخ 25 سبتمبر 2026. وأفاد الفريق بعدم وجود أي دليل على استغلاله على شبكة عامة.
⚠️ النقطة الأساسية: اكتُشفت ثغرة خطيرة، لكن لا يوجد استغلال مؤكد.
حتى سلاسل الكتل الراسخة تحتاج إلى مراجعات أمنية مستمرة.
ثق بالكود. وتحقق من إجراءات الحماية.
انظر إلى ما وراء الضجة.
#XRP #CryptoSecurity #Blockchain #OXIDELYNX
هل كان من الممكن إنشاء XRP من العدم؟
كان من الممكن نظريًا أن يسمح خلل خطير في محرك المدفوعات في XRP Ledger للمهاجمين بإنشاء XRP قابل للإنفاق يتجاوز المعروض المحدد.
🔎 ماذا حدث؟
ربما كان هذا الخلل موجودًا منذ عام 2015. وصدر إصلاح له في xrpld 3.4.1 بتاريخ 25 سبتمبر 2026. وأفاد الفريق بعدم وجود أي دليل على استغلاله على شبكة عامة.
⚠️ النقطة الأساسية: اكتُشفت ثغرة خطيرة، لكن لا يوجد استغلال مؤكد.
حتى سلاسل الكتل الراسخة تحتاج إلى مراجعات أمنية مستمرة.
ثق بالكود. وتحقق من إجراءات الحماية.
انظر إلى ما وراء الضجة.
#XRP #CryptoSecurity #Blockchain #OXIDELYNX
103
·
--
$WLD /USDT | رادار الزخم #007
{future}(WLDUSDT)
الحالة: إعداد استمرارية صاعدة
WLD تتداول فوق جميع المتوسطات المتحركة الرئيسية على الرسم البياني 4 ساعات، مع MA7 وMA25 تعمل كدعم ديناميكي. المشترون يدافعون عن منطقة $0.62، وكسر فوق $0.66 قد يؤدي إلى حركة توسعية أخرى.
اتجاه خطة المال الذكي: LONG
منطقة الدخول: $0.638 – $0.648
الرافعة: 5x–8x معزولة
وقف الخسارة: $0.612
خريطة الأهداف
الهدف 1: $0.670
الهدف 2: $0.695
الهدف 3: $0.725
محفز السوق
إغلاق شمعة 4 ساعات فوق $0.66 مع زيادة في الحجم يمكن أن يسرع الزخم نحو منطقة $0.70+
إدارة الصفقة
خذ 30% من الأرباح عند TP1، انقل وقف الخسارة إلى نقطة الدخول، واترك المركز المتبقي يعمل.
درجة الميزة: 8/10
إبطال: خسارة دعم $0.612 وضعف الهيكل الصاعد.
الرسم البياني يتحسن، لكن الدخول بالقرب من الدعم دائماً أفضل من مطاردة الشموع الخضراء.
#FedProposesCIPForStablecoinIssuers #GoldETFInflowsBiggestSinceApril17 #OilHeadsForDeepWeeklyLoss
$WLD /USDT | رادار الزخم #007
الحالة: إعداد استمرارية صاعدة
WLD تتداول فوق جميع المتوسطات المتحركة الرئيسية على الرسم البياني 4 ساعات، مع MA7 وMA25 تعمل كدعم ديناميكي. المشترون يدافعون عن منطقة $0.62، وكسر فوق $0.66 قد يؤدي إلى حركة توسعية أخرى.
اتجاه خطة المال الذكي: LONG
منطقة الدخول: $0.638 – $0.648
الرافعة: 5x–8x معزولة
وقف الخسارة: $0.612
خريطة الأهداف
الهدف 1: $0.670
الهدف 2: $0.695
الهدف 3: $0.725
محفز السوق
إغلاق شمعة 4 ساعات فوق $0.66 مع زيادة في الحجم يمكن أن يسرع الزخم نحو منطقة $0.70+
إدارة الصفقة
خذ 30% من الأرباح عند TP1، انقل وقف الخسارة إلى نقطة الدخول، واترك المركز المتبقي يعمل.
درجة الميزة: 8/10
إبطال: خسارة دعم $0.612 وضعف الهيكل الصاعد.
الرسم البياني يتحسن، لكن الدخول بالقرب من الدعم دائماً أفضل من مطاردة الشموع الخضراء.
#FedProposesCIPForStablecoinIssuers #GoldETFInflowsBiggestSinceApril17 #OilHeadsForDeepWeeklyLoss
الحالة: إعداد استمرارية صاعدة
WLD تتداول فوق جميع المتوسطات المتحركة الرئيسية على الرسم البياني 4 ساعات، مع MA7 وMA25 تعمل كدعم ديناميكي. المشترون يدافعون عن منطقة $0.62، وكسر فوق $0.66 قد يؤدي إلى حركة توسعية أخرى.
اتجاه خطة المال الذكي: LONG
منطقة الدخول: $0.638 – $0.648
الرافعة: 5x–8x معزولة
وقف الخسارة: $0.612
خريطة الأهداف
الهدف 1: $0.670
الهدف 2: $0.695
الهدف 3: $0.725
محفز السوق
إغلاق شمعة 4 ساعات فوق $0.66 مع زيادة في الحجم يمكن أن يسرع الزخم نحو منطقة $0.70+
إدارة الصفقة
خذ 30% من الأرباح عند TP1، انقل وقف الخسارة إلى نقطة الدخول، واترك المركز المتبقي يعمل.
درجة الميزة: 8/10
إبطال: خسارة دعم $0.612 وضعف الهيكل الصاعد.
الرسم البياني يتحسن، لكن الدخول بالقرب من الدعم دائماً أفضل من مطاردة الشموع الخضراء.
#FedProposesCIPForStablecoinIssuers #GoldETFInflowsBiggestSinceApril17 #OilHeadsForDeepWeeklyLoss
1
183
سجّل الدخول لاستكشاف المزيد من المُحتوى
انضم إلى مُستخدمي العملات الرقمية حول العالم على Binance Square
⚡️ احصل على أحدث المعلومات المفيدة عن العملات الرقمية.
💬 موثوقة من قبل أكبر منصّة لتداول العملات الرقمية في العالم.
👍 اكتشف الرؤى الحقيقية من صنّاع المُحتوى الموثوقين.
البريد الإلكتروني / رقم الهاتف
المواضيع الرائجة
1
#BinanceProcesses$4.65BWithdrawals
54,690 مشاهدات
233 يقومون بالنقاش
2
#WithdrawalsBack: 15 networks live
12,259 مشاهدات
178 يقومون بالنقاش
3
#EthereumSurpasses$2300
1,510 مشاهدات
46 يقومون بالنقاش
4
#BitcoinSpotETFsPost$203MWeeklyOutflow
1,944 مشاهدات
29 يقومون بالنقاش
5
#SouthKoreanLawmakerProposesReviewOfAllListedDigitalAssets
793 مشاهدات
31 يقومون بالنقاش
6
#BrazilVirtualAssetLicenseDeadlineDrawsAbout40Firms
19,956 مشاهدات
355 يقومون بالنقاش
7
#BTCPayServerUrgesOperatorsToShutDownInstances
15,839 مشاهدات
298 يقومون بالنقاش
8
#BankOfKoreaSurveysFinancialFirmsOnVirtualAssetRisks
541 مشاهدات
18 يقومون بالنقاش
9
#StudyFindsCircleAIAgentWalletLimitsCanBeBypassed
10,056 مشاهدات
182 يقومون بالنقاش
10
#BinanceHadAlreadyCovered$6BofHackLoss
14,296 مشاهدات
146 يقومون بالنقاش