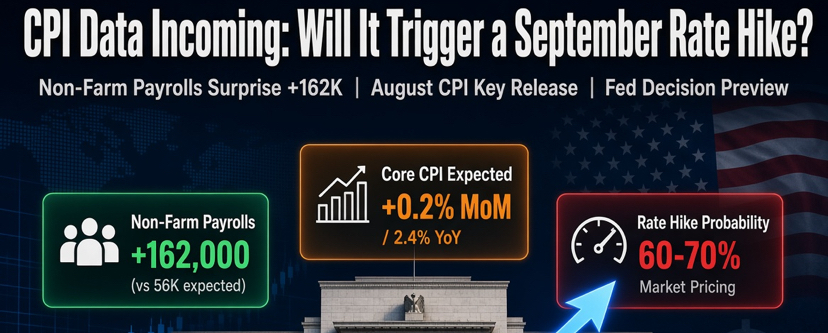
The August non-farm payrolls data has already raised market expectations: actual job growth was 162,000—far exceeding the consensus forecast of around 56,000—while the unemployment rate held steady at 4.1%. Significant contributions came from the leisure and hospitality sector (particularly food services) and local government education, with the private sector also recording an increase of 127,000 jobs. The labor market has shown greater resilience than most had previously anticipated.
Against this backdrop, the August CPI data released today (September 11) serves as the final key piece of the puzzle ahead of the September FOMC meeting (scheduled for the 15th–16th). Current market consensus generally anticipates:
Headline CPI: +0.4% month-over-month (vs. +0.1% previously), with the year-over-year rate remaining near 3.4%;
Core CPI: +0.2% month-over-month (unchanged from the previous reading), with the year-over-year rate potentially easing to 2.4% (down from 2.5%).
A rebound in gasoline prices is a primary driver of the headline CPI increase, whereas the core component depends largely on whether rents, airfares, and service costs remain under upward pressure. If the core month-over-month figure comes in strictly at or below 0.2%, the case for standing pat remains plausible; however, should it approach or hit 0.3%—combined with the strong non-farm payrolls and recent hot PPI data—the probability of a 25-basis-point rate hike would rise significantly. Futures markets currently price in a 60%–70% implied probability of a September rate hike.
My assessment is that while a September rate hike is not a certainty, the probability remains high. The employment data has eliminated the argument that the economy is too weak for a hike, and inflation continues to run above the 2% target. Under the influence of Warsh, the Fed has adopted stricter criteria regarding "sustained data improvement." If today’s core CPI fails to signal a clear cooling trend, it will be difficult for policymakers to simply opt for a wait-and-see approach.
I remain cautious regarding the market outlook. Should expectations for a rate hike intensify further, high-valuation growth stocks and interest-rate-sensitive sectors will likely face continued pressure, and yields on short-term U.S. Treasuries may see further upside. Conversely, if core data comes in significantly below expectations, it could offer short-term relief; however, given persistent medium-term inflation stickiness, the scope for such relief remains limited.
The data speaks for itself. Today’s CPI figures will directly determine whether the market continues to price in interest rate hikes or shifts to a "wait-and-see" stance.