

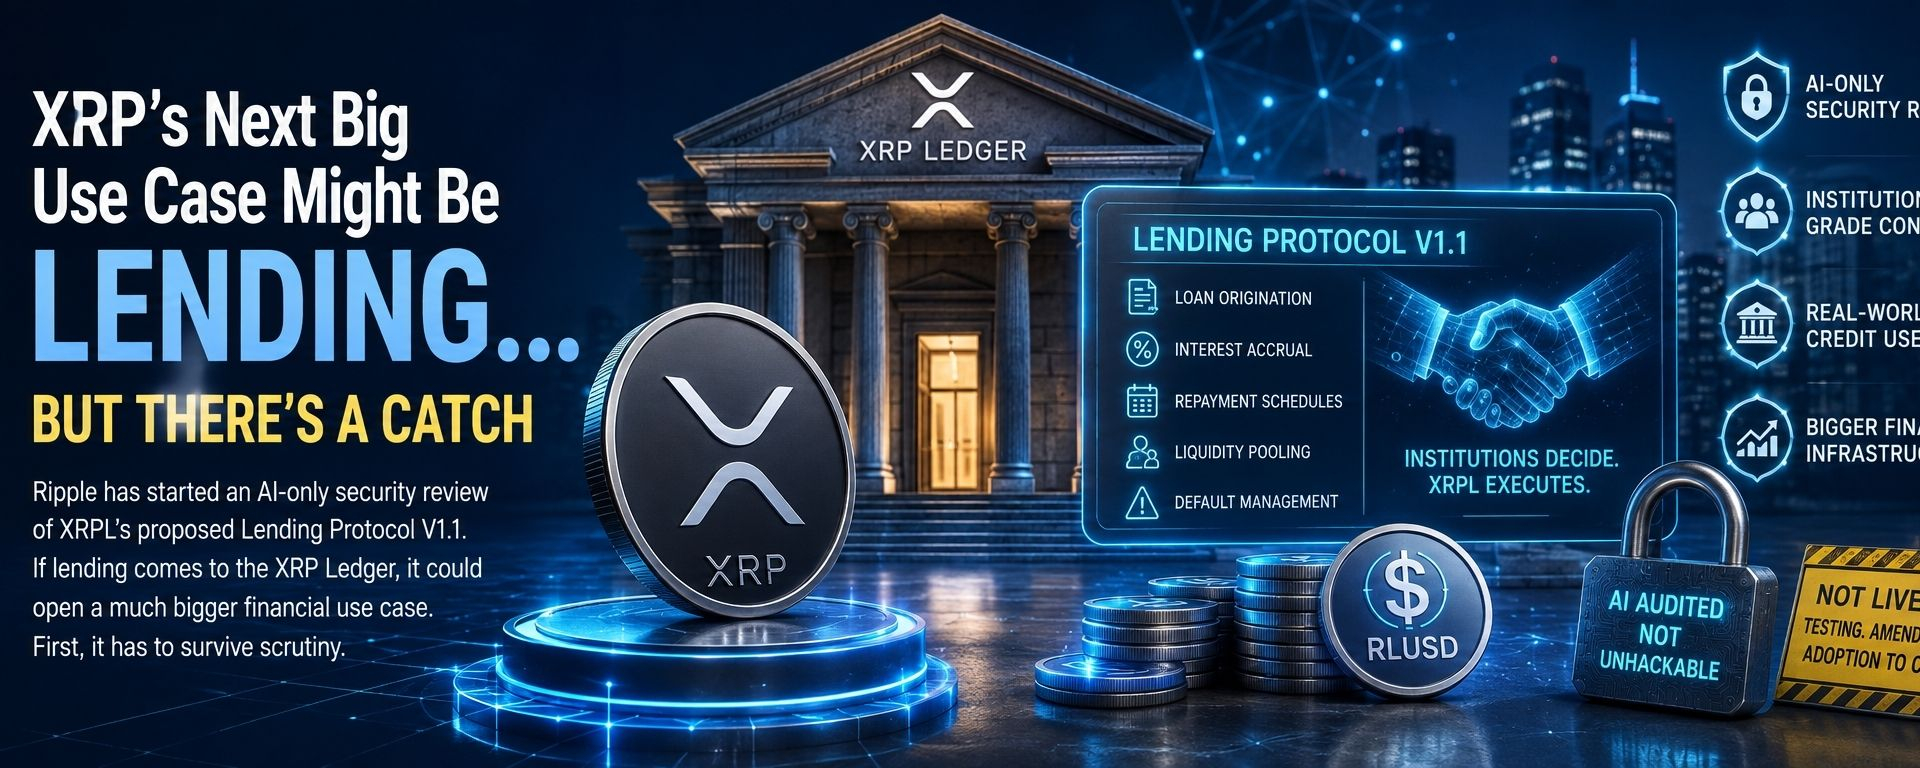
Ripple has started an AI-only security review of XRPL’s proposed Lending Protocol V1.1. If lending comes to the XRP Ledger, it could open a much bigger financial use case. First, it has to survive scrutiny.
Ripple has begun an AI-only security review of one of the XRP Ledger’s most interesting proposed upgrades.
That sounds bad.
It’s probably exactly what you want.
Security platform Sherlock has announced that Ripple is using its Audit Engine to review Lending Protocol V1.1 for the XRP Ledger.
The system brings together multiple AI auditors and frontier models with specialised security capabilities, essentially throwing different automated approaches at the protocol to see what they can find.
For this particular review, Sherlock describes the process as AI-only: multiple AI auditors and frontier models analysing the code for vulnerabilities.
And considering the code in question could eventually help move actual loans and institutional capital around XRPL…
Breaking it before it goes live seems preferable to discovering the problem afterwards.
But the AI angle is actually only half the story.
The much bigger question is:
What exactly is XRPL trying to build?
Because if the Lending Protocol works as intended, XRP Ledger could move further beyond:
Payments.
Transfers.
Trading.
Tokenization.
…and into something considerably bigger.
Credit.
That deserves some attention.
🤔 First: what is the XRPL Lending Protocol?
Let’s strip away the jargon.
Imagine a business needs money for three months.
Normally, it might go to:
A bank.
A private-credit fund.
A lender.
Another financial institution.
They assess the borrower.
Decide whether they’re comfortable lending.
Agree on the interest rate.
Set repayment terms.
Then provide the capital.
XRPL’s proposed Lending Protocol is trying to put part of that process on-chain.
Importantly, it is not trying to make the blockchain decide whether Dave’s logistics company deserves a £2 million loan.
That decision remains off-chain.
The basic model is:
Institutions make the credit decision.
↓
XRPL handles the execution.
Once lending terms have been agreed, the protocol can standardise things including:
Loan origination.
Interest accrual.
Repayment schedules.
Loan servicing.
Defaults.
Liquidity pooling.
In other words:
Humans decide who deserves the loan.
The blockchain helps execute what happens after that decision.
That distinction matters.
Because this isn’t trying to recreate every part of a bank inside a smart contract.
It’s trying to put the financial plumbing on-chain.
💰 And these aren’t necessarily crypto-style overcollateralised loans
This is where the proposal gets considerably more interesting.
A lot of DeFi lending works something like this:
You want to borrow $70,000.
Great.
Please deposit $100,000 worth of crypto first.
Useful?
Sure.
But that’s not exactly how most real-world business lending works.
XRPL’s proposed Lending Protocol is designed to enable fixed-term, uncollateralized loans using pooled funds from a Single Asset Vault.
Creditworthiness would be assessed through off-chain underwriting and risk management.
The protocol then handles the agreed loan on-chain.
XRPL documentation also describes first-loss capital protection, which is designed to help absorb losses if borrowers default.
That sounds much closer to traditional credit markets.
Which is deliberate.
The intended use cases include things like:
Inventory financing for market makers
Working-capital facilities
Underwritten loans
Institutional credit
That is a very different proposition from:
“Borrow $500 of USDC against your meme coins.”
🏦 Why would institutions actually want this?
Because lending is enormous.
Financial markets don’t just move assets around.
They finance them.
Companies borrow money.
Market makers borrow inventory.
Funds use leverage.
Dealers finance positions.
Businesses bridge gaps between payments.
Assets get pledged.
Capital gets recycled.
Credit sits underneath a ridiculous amount of economic activity.
And this is where tokenization starts becoming much more interesting.
Imagine tokenizing a Treasury fund.
Great.
Now what?
Can somebody borrow against it?
Can it help finance another position?
Can it become collateral?
Can it provide liquidity?
Can businesses actually do useful financial things with it?
That’s where tokenization starts becoming a financial system rather than an expensive digital filing cabinet.
The missing layer between tokenized assets and functioning on-chain capital markets is increasingly credit infrastructure.
And that’s exactly what XRPL is trying to build.
🧩 There are actually two important pieces
The proposed lending system relies on two complementary components.
1. Single Asset Vaults
Think of these as pools of one particular asset.
Capital can be deposited into the vault and then made available for lending.
2. The Lending Protocol
This is the machinery that allows pooled liquidity to be originated into fixed-term loans with agreed terms, servicing and repayment logic.
Together:
Vault provides capital.
↓
Borrower is approved off-chain.
↓
Loan terms are agreed.
↓
XRPL executes the loan.
↓
Interest and repayments follow the predetermined terms.
That is the basic idea.
And if you’re thinking:
“That sounds suspiciously like normal finance.”
Exactly.
That’s probably the point.
🔐 Institutions still get compliance controls
There’s another important difference between this and the Wild West version of DeFi.
XRPL also has compliance-oriented infrastructure for restricting access. Permissioned Domains can be used by features such as lending protocols to limit participation to approved entities, with Verifiable Credentials helping establish whether an account meets the required conditions.
That matters enormously if XRPL wants:
Banks.
Funds.
Payment companies.
Market makers.
Asset managers.
Other regulated financial institutions.
to actually use this infrastructure.
Institutions generally don’t wake up in the morning thinking:
“I wish today’s counterparty was completely anonymous.”
They want to know who they’re dealing with.
They have KYC rules.
AML requirements.
Risk departments.
Compliance teams.
Regulators.
Lawyers.
Lots and lots of lawyers.
So XRPL increasingly appears to be trying to combine:
Blockchain settlement
with:
traditional financial controls.
That’s a much more realistic institutional proposition than pretending regulated finance is suddenly going to abandon every compliance requirement it has.
🤖 So why is AI trying to break it?
Because lending protocols are exactly the sort of infrastructure you really, really don’t want breaking.
A bug in a social app?
Annoying.
A bug in software controlling pools of financial assets and loans?
Different afternoon.
Crypto has repeatedly learned this lesson the expensive way.
Smart contracts and DeFi protocols have lost billions of dollars over the years through:
Code vulnerabilities.
Economic exploits.
Oracle manipulation.
Access-control failures.
Bad assumptions.
Unexpected interactions between protocols.
And occasionally:
Someone noticing that a developer forgot something rather important.
So Sherlock’s Audit Engine is now reviewing Lending Protocol V1.1.
The system uses multiple AI auditing agents and frontier models with specialised security skills, adjusting the testing depending on the complexity and attack surface of the code.
That’s genuinely interesting.
But there’s an important warning.
⚠️ “AI audited” does NOT mean “unhackable”
Please tattoo this onto every crypto protocol.
An audit is not a guarantee.
A human audit isn’t.
An AI audit isn’t.
Seven audits aren’t.
They reduce risk.
They can identify vulnerabilities.
They can catch assumptions developers missed.
They can make software considerably safer.
But they cannot prove:
“Nobody will ever find a way to exploit this.”
Security doesn’t work like that.
That doesn’t make audits pointless.
Quite the opposite.
It demonstrates why security has to be continuous.
Audit.
Test.
Fix.
Audit again.
Monitor.
Respond.
Upgrade.
Repeat forever.
Welcome to financial infrastructure.
🚧 And here’s the biggest catch: lending still isn’t live on mainnet
This is the part I expect to disappear from plenty of XRP posts.
XRPL’s native lending infrastructure is still moving through testing and the amendment process.
The underlying Single Asset Vault and Lending Protocol proposals, XLS-65 and XLS-66, remain subject to validator approval, while developers can already integrate and test the system on devnet.
Meanwhile, the newer LendingProtocolV1_1 revision is officially listed by XRPL as:
In Development.
Recent development work has moved support for V1.1 forward, but that does not mean native lending is operating as a production market on XRPL mainnet today.
So:
Development progress ≠ activation.
Audit ≠ launch.
Launch ≠ adoption.
Adoption ≠ billions in loans.
There’s a sequence here.
Crypto headlines occasionally like to skip approximately four of those steps.
We won’t.
💵 Where does RLUSD fit?
Now things get even more interesting.
RLUSD has crossed the $2 billion milestone.
And RLUSD supply on XRPL itself is now approaching the $1 billion mark, with roughly $963 million circulating on the network around the latest reported milestone.
That creates an obvious possibility.
Stablecoins are natural assets for lending.
A business generally doesn’t want to borrow:
“$500,000 worth of something that might be worth $410,000 by Tuesday.”
It wants dollars.
Or something representing dollars.
That means RLUSD could eventually become one of the more natural assets used inside an XRPL lending ecosystem.
That makes sense.
But it also creates another XRP question.
🤔 If the loans use RLUSD, why should XRP holders care?
Excellent question.
And this is where I don’t want to manufacture an answer.
If somebody borrows:
$1 million of RLUSD
on XRP Ledger…
they are not borrowing $1 million of XRP.
That matters.
The bullish XRP argument therefore cannot simply be:
“XRPL lending launches = everybody needs XRP.”
That’s too easy.
The more realistic potential benefit is broader.
Successful lending could create:
More capital on XRPL.
More institutional users.
More liquidity.
More stablecoin usage.
More transactions.
More financial applications.
More tokenized collateral.
More reasons to keep assets on the network.
And potentially greater utility for XRP within the wider XRPL liquidity ecosystem.
XRP is still the native asset of the network.
It is used for fees and reserves and can play liquidity and bridging roles.
But whether a lending boom would create material additional XRP demand is something we would need to observe.
Not assume.
Same rule as always:
XRPL usage can be positive for the ecosystem without every transaction requiring somebody to buy a large amount of XRP.
🏗️ Now connect this to what Ripple has been doing
This is where the week’s stories start fitting together.
Ripple is beginning to look less like a traditional crypto company.
Look at the stack being assembled:
Payments
↓
Custody
↓
RLUSD
↓
Prime brokerage
↓
Tokenization
↓
Collateral infrastructure
↓
Lending
↓
Settlement
That’s interesting.
Because these things can potentially interact.
Imagine an institutional market where:
A fund is tokenized.
The asset sits on XRPL.
RLUSD provides a dollar settlement asset.
A lending pool provides credit.
An institution borrows against or finances activity.
Ripple Prime provides institutional market access elsewhere in the stack.
Custody protects assets.
Settlement happens on-chain.
That starts resembling an actual financial system.
Not just a blockchain with tokens on it.
Now, we’re not there yet.
That sentence is important enough to repeat.
We’re not there yet.
But the pieces being developed increasingly point in that direction.
Ripple’s recent investments in ZILO and Licuido are also aimed at bringing transfer agency, issuance and collateral mobility infrastructure onto XRPL.
Add lending to that picture and the strategy becomes much easier to see.
🐂 The bullish scenario
Let’s build the strongest case.
Lending Protocol V1.1 completes security review successfully.
Any vulnerabilities are fixed.
The relevant amendments eventually move through the XRPL governance process and become enabled.
Single Asset Vaults and lending infrastructure launch.
Institutional lenders supply meaningful capital.
Businesses and financial institutions actually borrow.
RLUSD becomes heavily used within credit markets.
Tokenized assets increasingly interact with lending and collateral markets.
Liquidity deepens.
New financial products appear.
And XRP becomes more useful inside a much larger XRPL economy.
If all of that happens?
Then lending could become one of the most significant expansions of XRP Ledger’s utility in years.
Not because loans automatically pump XRP.
Because XRPL would be doing something economically important that it wasn’t doing before.
That’s the bullish case.
And I think it’s worth taking seriously.
😐 The base case
The protocol eventually launches.
It works.
Developers build around it.
A handful of institutional or crypto-native lending products appear.
Usage grows slowly.
RLUSD becomes a common lending asset.
But volume remains relatively modest for a while.
XRP benefits more from the broader growth of XRPL than from direct lending demand.
Honestly?
This wouldn’t surprise me.
Financial infrastructure takes time.
Banks don’t normally see a Tuesday press release and move $10 billion onto a new system by Wednesday afternoon.
There will be pilots.
Testing.
Compliance work.
Integrations.
Risk reviews.
And probably many meetings that should have been emails.
That’s normal.
🐻 The bearish scenario
The security review identifies significant problems.
Development gets delayed.
Validator support remains insufficient.
The amendments don’t activate.
Or perhaps the protocol eventually launches but nobody meaningfully uses it.
That’s the other risk people forget.
You can build technically excellent infrastructure…
and still have no customers.
Crypto has plenty of beautifully engineered ghost towns.
So even if Lending Protocol V1.1 eventually clears every technical hurdle, we still need to ask:
Who is actually lending?
Who is borrowing?
How much capital is involved?
What assets are being used?
Are institutions participating?
Does activity keep growing?
The ultimate audit isn’t Sherlock.
It’s usage.
👀 The six things I’m watching
Here’s my checklist from here.
1. 🔐 What does the security review find?
The review should eventually give us a better idea of what vulnerabilities, if any, were identified.
If vulnerabilities are found?
That isn’t automatically bad news.
Finding bugs before launch is exactly what an audit is supposed to do.
What matters is how serious they are and how they’re addressed.
2. 🗳️ Does LendingProtocolV1_1 progress toward activation?
Right now:
In Development.
That’s the status that matters.
When that changes, we’ll pay attention.
3. 💰 How much capital enters Single Asset Vaults?
Once infrastructure actually becomes usable, deposits become far more interesting than announcements.
Show me the money.
Literally.
4. 💵 What role does RLUSD play?
RLUSD is already becoming one of Ripple’s most important products.
If it becomes a significant borrowing, lending or settlement asset on XRPL, we’ll be able to measure that.
That’s considerably more useful than guessing.
5. 🏦 Do institutions actually participate?
This is the big one.
Not:
“Protocol designed for institutions.”
Actual institutions.
Actual loans.
Actual capital.
Actual usage.
That’s the standard.
6. ⚡ Does XRP gain meaningful utility from it?
And finally:
Does greater lending activity create more demand for XRP?
Does XRP become more useful for liquidity?
Does it connect different assets and markets?
Does deeper XRPL activity actually matter economically for XRP?
We shouldn’t decide the answer in advance.
We should watch the data.
☕ My take
I think lending could eventually become one of the more important XRPL developments we’ve covered.
Not because “lending” sounds exciting.
It really doesn’t.
Try putting:
“FIXED-TERM UNCOLLATERALIZED CREDIT INFRASTRUCTURE!!!”
on a YouTube thumbnail.
Good luck.
It matters because credit is one of the fundamental building blocks of finance.
Tokenization lets assets exist on-chain.
Stablecoins give markets a stable settlement asset.
Trading creates liquidity.
But lending allows capital to become productive.
That’s a much bigger step.
And Ripple’s broader strategy increasingly seems to be moving toward exactly that kind of financial infrastructure.
The encouraging part?
The protocol is being tested.
The code is being scrutinised.
The supporting infrastructure is being built.
The less exciting part?
It isn’t live yet.
And even when it is, we still need adoption.
That’s the catch.
There is a huge difference between:
“XRPL can support institutional lending.”
and:
“Institutions are borrowing billions through XRPL.”
Today, we’re much closer to the first sentence.
The investment thesis becomes considerably more interesting if we eventually reach the second.
So I’m not marking this:
🚀 BULLISH XRP
and moving on.
I’m putting it on the watchlist.
First:
Can they secure it?
Then:
Can they launch it?
Then:
Will anyone use it?
And finally:
Does XRP actually benefit?
Those four questions matter far more than whatever price target somebody attaches to the announcement.
For now, Ripple is putting the protocol through an AI-only security review.
Good.
If XRPL is serious about becoming infrastructure for institutional finance…
I’d rather somebody tried very hard to break it before the institutions arrive.


