
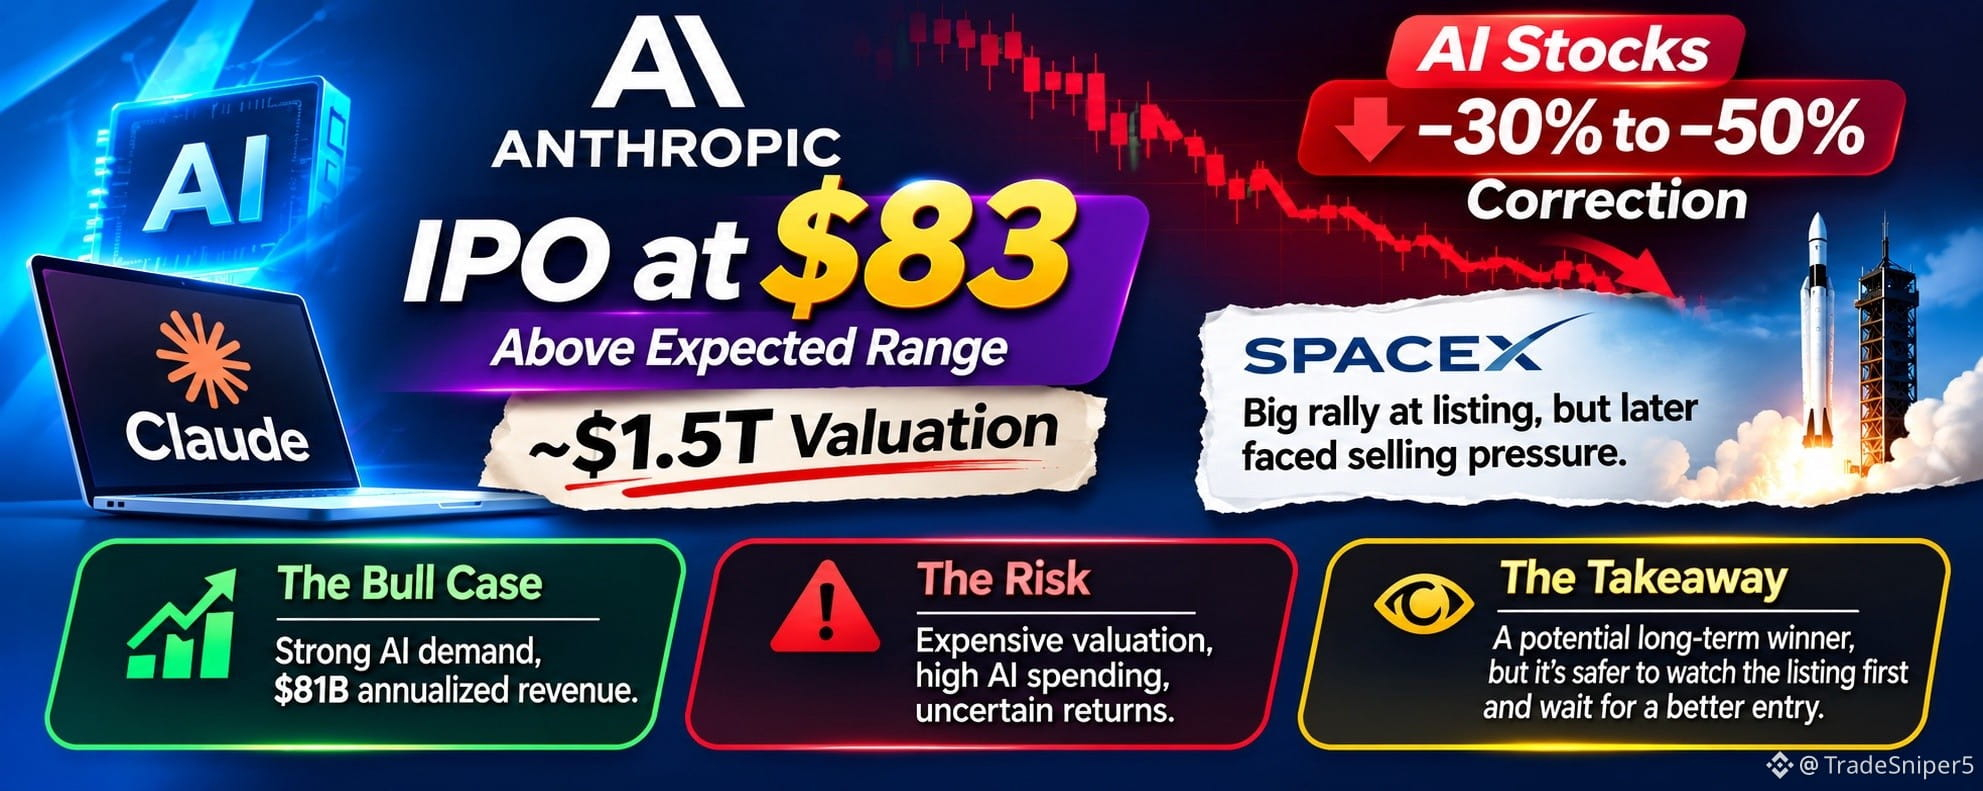
Anthropic has reportedly priced its IPO at $83 a share—above expectations—putting its valuation near $1.5 trillion. The timing, though, is tricky.
Many AI stocks have already pulled back by 30% to 50% as investors push back on steep valuations, heavy infrastructure spending, and questions around near-term returns. Against that backdrop, it is fair to ask why demand for Anthropic is still holding up so well.
Here are three things worth keeping in mind:
Strong AI demand: Rapid enterprise adoption of Claude has kept Anthropic near the center of the AI conversation, backed by a reported $81 billion annualized revenue run rate that shows how fast the business has scaled.
Valuation risk: A $1.5 trillion price tag already bakes in years of strong execution. Even solid growth may not protect the stock if broader market sentiment stays weak.
The SpaceX lesson: SpaceX drew huge excitement at its IPO before running into selling pressure later on. A strong debut does not automatically mean smooth gains afterward.
My Take
Anthropic could easily turn out to be a long-term winner in AI, but buying right when other AI names are correcting 30% to 50% carries real risk. Rather than chasing the initial IPO hype, I would rather see how it trades out of the gate and wait for a more reasonable entry.
Where do you stand—is Anthropic set to become the next AI giant, or could it slide 30% after listing?