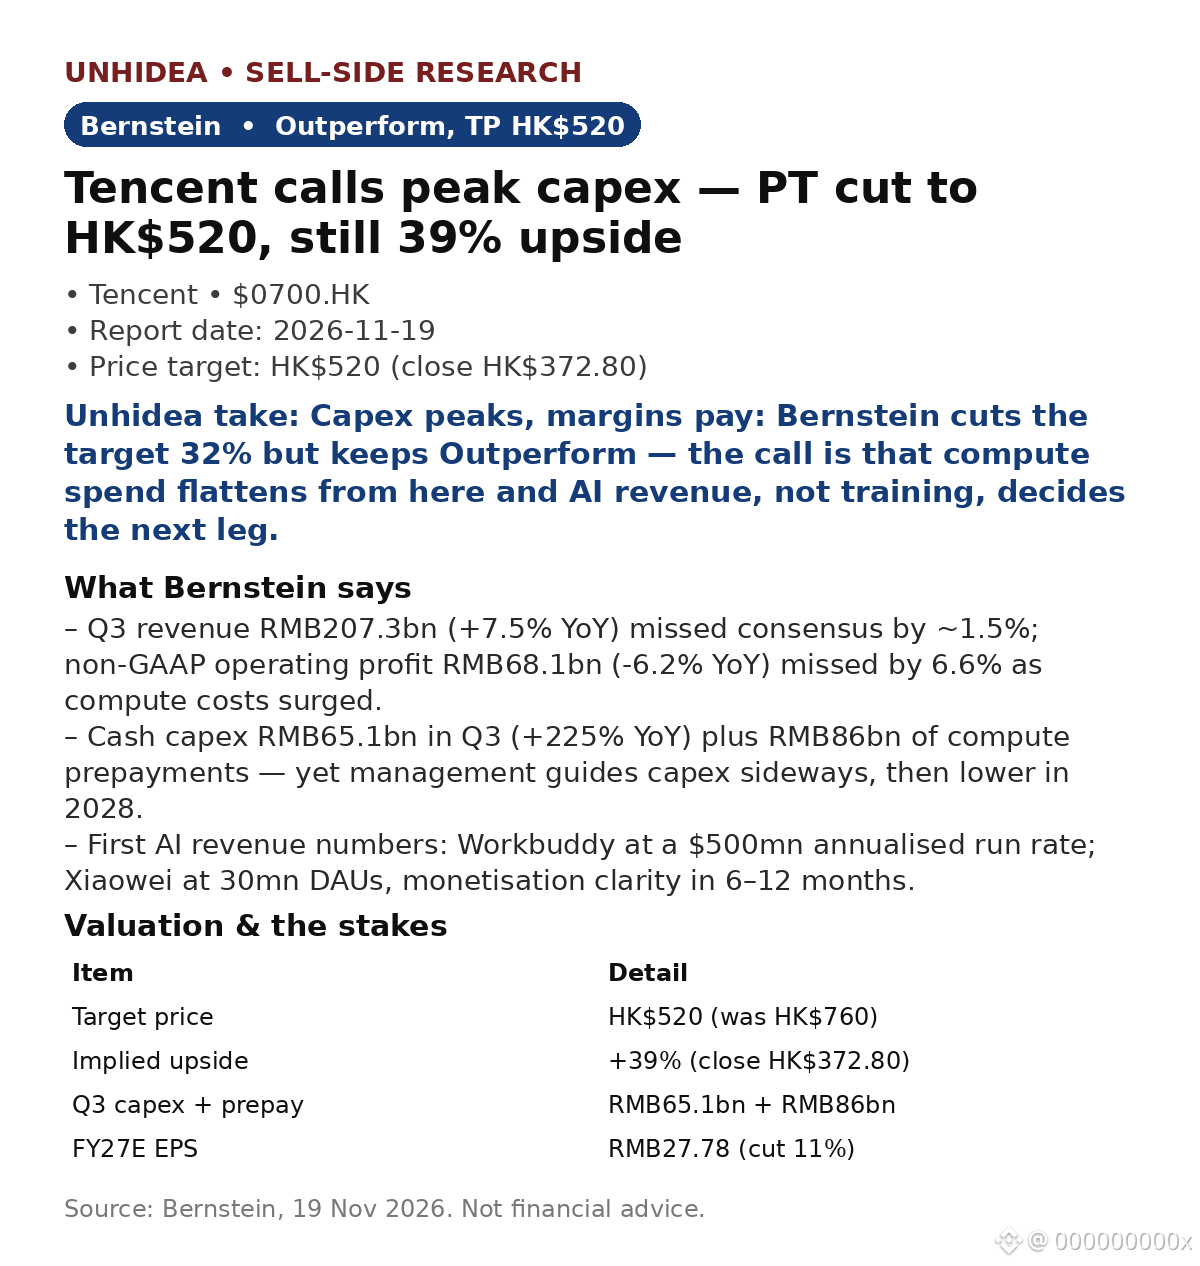
$0700.HK: Tencent calls peak capex — Bernstein keeps Outperform, PT HK$520 (cut from HK$760)
- Q3 revenue RMB207.3bn (+7.5% YoY), ~1.5% below consensus; non-GAAP operating profit RMB68.1bn (-6.2% YoY), 6.6% below consensus — compute costs did the damage.
- Capex is the story: RMB65.1bn in Q3 (+225% YoY) plus RMB86bn of compute prepayments — yet management says capex tracks sideways, then falls in 2028. Bernstein: the second name after Sony to call hardware costs unsustainable.
- The bill: bandwidth & server costs +132% YoY, non-staff R&D +152%. Ads still +18.8% to RMB43.0bn, gaming +4.6% to RMB66.5bn, FBS +9.4% to RMB63.7bn. Core operating profit ex-AI spend +8% to RMB83.3bn.
- First AI revenue numbers: Workbuddy at a $500mn annualised run rate; Xiaowei at 30mn DAUs, monetisation in 6–12 months. US chip curbs delay training, not inference revenue, Bernstein says.
- Valuation: PT HK$520 is +39% vs the HK$372.80 close (18 Nov), near the HK$370 52-week low, on ~11x trailing earnings after a 38% YTD slide; FY27E EPS cut 11% to RMB27.78.
Unhidea take: peak capex is the debate beyond Tencent — if a buyer of this scale flattens spend, the AI hardware cycle's duration is the question.
Unhidea take: Tencent trades at ~11x while the AI option is unpriced — Workbuddy and Xiaowei are the first hard numbers; if monetisation lands, Bernstein's 16x FY+1 multiple is the re-rating path.
Risks: US chip curbs, China macro, gaming comps, AI monetisation timing.
Source: Bernstein, 19 Nov 2026. Not financial advice.
- Q3 revenue RMB207.3bn (+7.5% YoY), ~1.5% below consensus; non-GAAP operating profit RMB68.1bn (-6.2% YoY), 6.6% below consensus — compute costs did the damage.
- Capex is the story: RMB65.1bn in Q3 (+225% YoY) plus RMB86bn of compute prepayments — yet management says capex tracks sideways, then falls in 2028. Bernstein: the second name after Sony to call hardware costs unsustainable.
- The bill: bandwidth & server costs +132% YoY, non-staff R&D +152%. Ads still +18.8% to RMB43.0bn, gaming +4.6% to RMB66.5bn, FBS +9.4% to RMB63.7bn. Core operating profit ex-AI spend +8% to RMB83.3bn.
- First AI revenue numbers: Workbuddy at a $500mn annualised run rate; Xiaowei at 30mn DAUs, monetisation in 6–12 months. US chip curbs delay training, not inference revenue, Bernstein says.
- Valuation: PT HK$520 is +39% vs the HK$372.80 close (18 Nov), near the HK$370 52-week low, on ~11x trailing earnings after a 38% YTD slide; FY27E EPS cut 11% to RMB27.78.
Unhidea take: peak capex is the debate beyond Tencent — if a buyer of this scale flattens spend, the AI hardware cycle's duration is the question.
Unhidea take: Tencent trades at ~11x while the AI option is unpriced — Workbuddy and Xiaowei are the first hard numbers; if monetisation lands, Bernstein's 16x FY+1 multiple is the re-rating path.
Risks: US chip curbs, China macro, gaming comps, AI monetisation timing.
Source: Bernstein, 19 Nov 2026. Not financial advice.