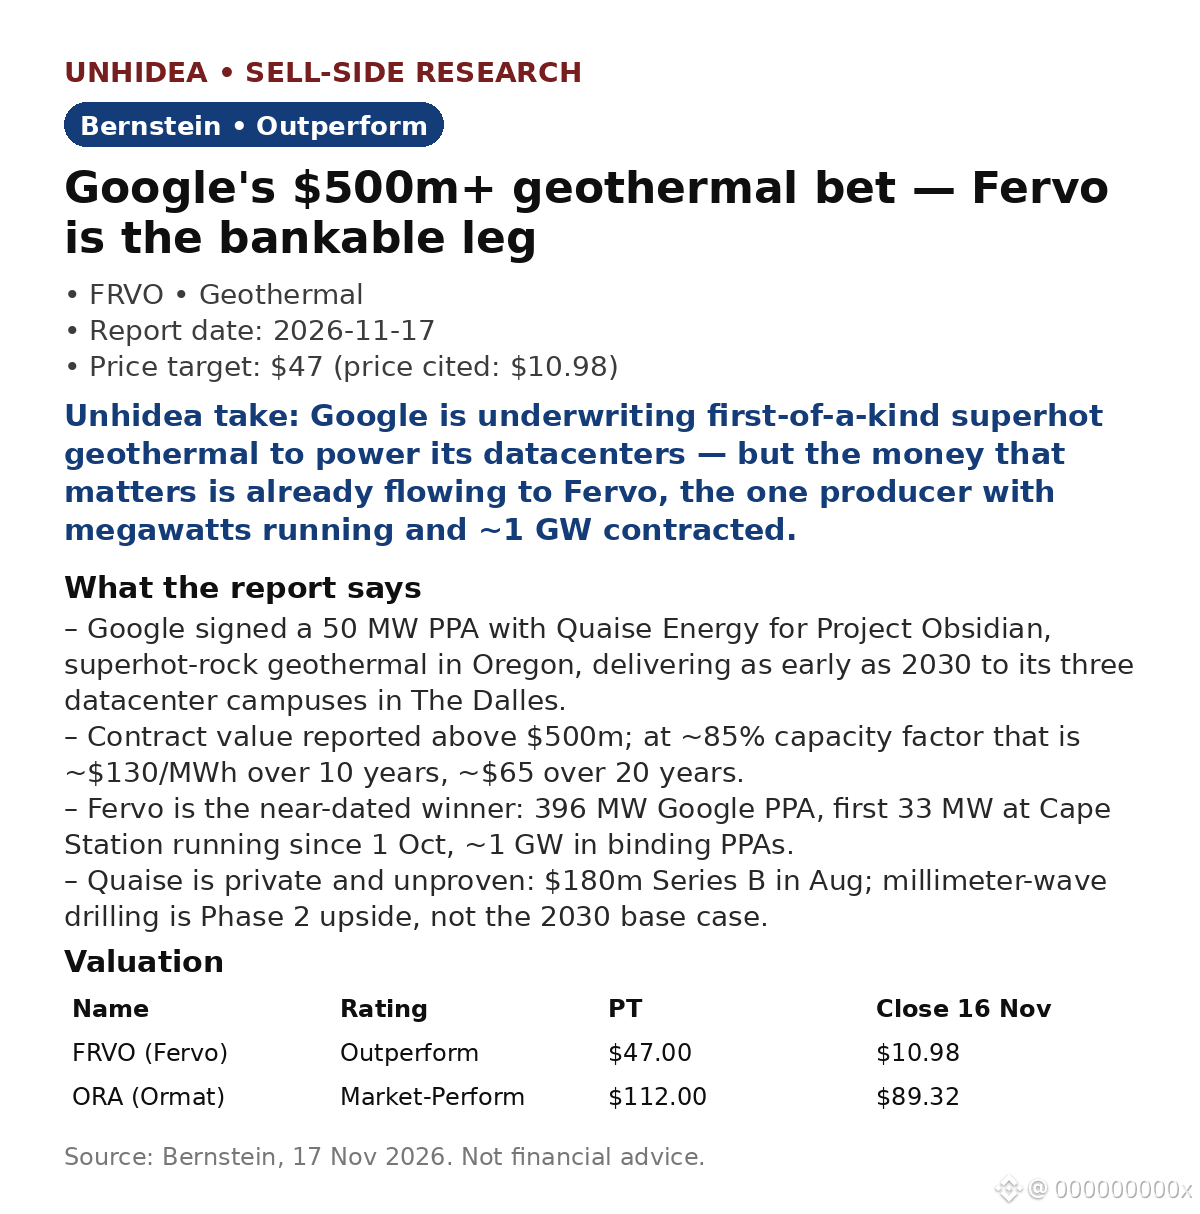
$FRVO: Google signed a 50 MW geothermal PPA worth $500m+ — and Bernstein says Fervo is the real winner. Outperform, $47 PT — ~4.3x the $10.98 close cited (16 Nov).
The deal is with Quaise Energy for Project Obsidian, a first-of-a-kind superhot-rock project in Oregon, delivering as early as 2030. At ~85% capacity factor, $500m is ~$130/MWh over 10 years, ~$65 over 20 (Bernstein math).
Why Fervo, not Quaise: Quaise is private and unproven — millimeter-wave drilling is Phase 2 upside, not the 2030 base case. Fervo has 396 MW contracted with Google, first 33 MW at Cape Station running since 1 Oct, ~1 GW in binding PPAs — "the near-dated, more bankable leg."
Valuation: FRVO is pre-profit (2026E EPS -$0.10), so the $47 PT rests on 2035 EBITDA at 10.5x EV/EBITDA, discounted back — a long-dated bet, not a near-term multiple.
Unhidea take: hyperscalers now underwrite tech risk to lock in firm 24/7 clean power — scarcity value accrues to assets already producing, not to options on unproven wells.
Unhidea take: watch who carries COD-slip risk — 2030 delivery for a first-of-a-kind well is a promise, not a pipeline.
Risks: subsurface productivity, millimeter-wave drilling at scale, transmission to The Dalles. Source: Bernstein, 17 Nov 2026. Not financial advice.
The deal is with Quaise Energy for Project Obsidian, a first-of-a-kind superhot-rock project in Oregon, delivering as early as 2030. At ~85% capacity factor, $500m is ~$130/MWh over 10 years, ~$65 over 20 (Bernstein math).
Why Fervo, not Quaise: Quaise is private and unproven — millimeter-wave drilling is Phase 2 upside, not the 2030 base case. Fervo has 396 MW contracted with Google, first 33 MW at Cape Station running since 1 Oct, ~1 GW in binding PPAs — "the near-dated, more bankable leg."
Valuation: FRVO is pre-profit (2026E EPS -$0.10), so the $47 PT rests on 2035 EBITDA at 10.5x EV/EBITDA, discounted back — a long-dated bet, not a near-term multiple.
Unhidea take: hyperscalers now underwrite tech risk to lock in firm 24/7 clean power — scarcity value accrues to assets already producing, not to options on unproven wells.
Unhidea take: watch who carries COD-slip risk — 2030 delivery for a first-of-a-kind well is a promise, not a pipeline.
Risks: subsurface productivity, millimeter-wave drilling at scale, transmission to The Dalles. Source: Bernstein, 17 Nov 2026. Not financial advice.