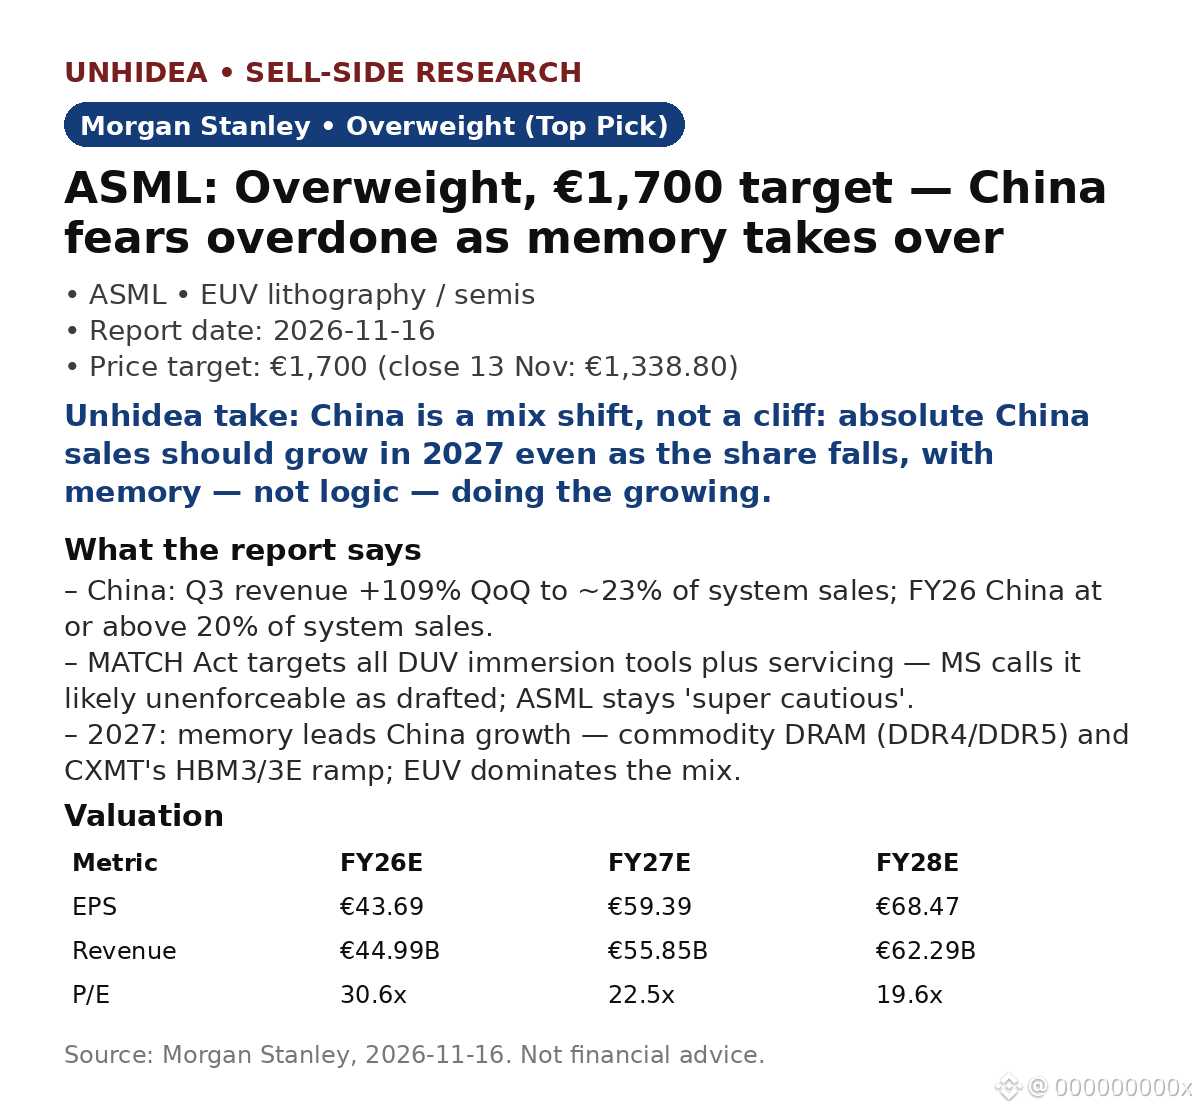
$ASML: Morgan Stanley keeps Overweight (Top Pick), €1,700 target — ~27% above the €1,338.80 close on 13 Nov. The China overhang looks overdone; memory is set to drive 2027.
China: Q3 revenue jumped ~109% QoQ to ~23% of system sales; FY26 China is tracking at or above 20% of system sales, with some pull-in ahead of the MATCH Act.
MATCH Act: the draft US bill targets all DUV immersion tools plus servicing at covered Chinese fabs. MS calls the absolute language likely unenforceable as drafted — but expects ASML to stay "super cautious".
2027: memory takes over from logic as the China growth driver — commodity DRAM (DDR4/DDR5) and CXMT's HBM3/3E ramp. Absolute China sales should still grow even as the share falls, with EUV dominating the mix.
Valuation: €1,700 = 25x MS's FY28E EPS of €68.47. FY27E EPS €59.39 (+36% YoY) on revenue €55.85B (+24%); P/E 22.5x FY27E vs 30.6x FY26E.
Unhidea take: the market is pricing the wrong risk — China is a mix shift, not a cliff. MS expects steady order-momentum signals at its Barcelona TMT conference this week; the tell is whether orders are backed by clean-room space.
Unhidea take: the real 2027 driver is memory, not logic — HBM and DRAM build-outs decide whether ASML's China line grows, and MS flags rising memory prices as upside.
Risks: weaker foundry/DRAM demand; China push-outs; High NA adoption slipping past 2028.
Source: Morgan Stanley, 16 Nov 2026. Not financial advice.
China: Q3 revenue jumped ~109% QoQ to ~23% of system sales; FY26 China is tracking at or above 20% of system sales, with some pull-in ahead of the MATCH Act.
MATCH Act: the draft US bill targets all DUV immersion tools plus servicing at covered Chinese fabs. MS calls the absolute language likely unenforceable as drafted — but expects ASML to stay "super cautious".
2027: memory takes over from logic as the China growth driver — commodity DRAM (DDR4/DDR5) and CXMT's HBM3/3E ramp. Absolute China sales should still grow even as the share falls, with EUV dominating the mix.
Valuation: €1,700 = 25x MS's FY28E EPS of €68.47. FY27E EPS €59.39 (+36% YoY) on revenue €55.85B (+24%); P/E 22.5x FY27E vs 30.6x FY26E.
Unhidea take: the market is pricing the wrong risk — China is a mix shift, not a cliff. MS expects steady order-momentum signals at its Barcelona TMT conference this week; the tell is whether orders are backed by clean-room space.
Unhidea take: the real 2027 driver is memory, not logic — HBM and DRAM build-outs decide whether ASML's China line grows, and MS flags rising memory prices as upside.
Risks: weaker foundry/DRAM demand; China push-outs; High NA adoption slipping past 2028.
Source: Morgan Stanley, 16 Nov 2026. Not financial advice.