

Palo Alto Networks approaches its fiscal first-quarter earnings announcement on November 18 amid broad market volatility driven by artificial intelligence earnings and economic releases. While expanding cloud adoption and security automation support elevated demand, enterprise software buyers face ongoing operational questions as organizations evaluate whether near-term procurement translates into immediate leverage or extended deployment cycles.
The upcoming earnings date marks a critical checkpoint for the cybersecurity provider after sustained expansion across its subscription base. Historical operational tracking highlights rising recurring revenue fueled by artificial intelligence and security adoption, yet market participants must weigh the reliance on continuous subscription expansion against broader corporate spending discipline across major enterprise accounts.
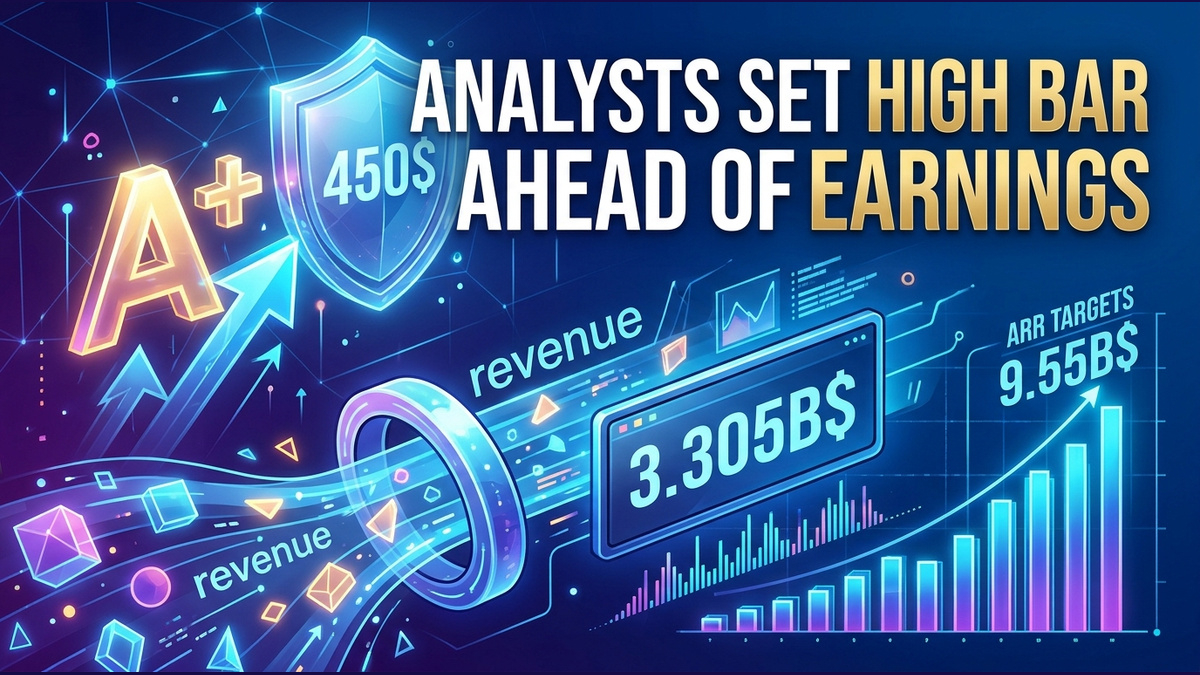
Wall Street estimates reflect high operational benchmarks ahead of the reporting date. Analyst projections that carry a buy rating and a 450 dollar price target anticipate next-generation security annualized recurring revenue to exceed guidance midpoints by roughly two percentage points, targeting 9.55 billion dollars alongside total quarterly revenue near 3.305 billion dollars.
Despite these optimistic benchmarks, conservative limitations may govern management forecasting discipline. Historical patterns indicate executive leadership may remain conservative with fiscal 2027 targets, restricting guidance updates strictly to the size of realized quarterly outperformance. This approach underscores the possibility that reported upside may not trigger larger guidance revisions.
Channel checks also reveal specific deployment timelines across key security products. Although Prisma AIRS reached 100 million dollars in annualized recurring revenue last quarter to mark the fastest product ramp in corporate history, partner evaluations still view calendar 2027 as the first real revenue year, showing that substantial commercial benefits require time to unfold fully across customer accounts.
Operational upside also hinges on integration and expansion across recent acquisitions. Growth expectations point to cross-selling from CyberArk and Chronosphere, including workload transitions as OpenAI completes migration milestones. Ongoing performance across firewall-attached subscriptions, Prisma SASE, and XSIAM offerings remains essential to maintaining projected expansion trajectories.
Analyst forecasting track records further illustrate the statistical variability inherent in enterprise software calls. Evaluated performance records indicate the analyst holds a 55 percent historical success rate across past recommendations, generating an average return of 10.5 percent. Such historical metrics demonstrate that even prominent market research carries measurable risk during changing conditions.