

The hawkish repricing of Wall Street’s Fed funds forecasts directly impacts benchmark borrowing costs. Because long-term yields and 30-year fixed mortgage rates depend on long-run inflation expectations, term premiums, and government borrowing volumes rather than Fed target rates alone, hawkish policy signals are keeping structural yields higher for longer.
1. Transmission Mechanism: How Fed Expectations Move Long Rates
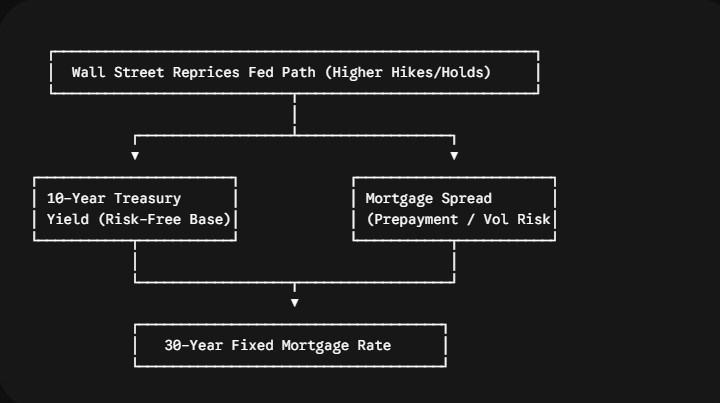
Fed Funds $\neq$ Mortgage Rates directly: The Federal Reserve sets short-term overnight bank rates. Mortgage rates benchmark against 10-Year Treasury Yields, which reflect investor expectations for average inflation and economic growth over a 10-year horizon.
Mortgage Spread: The 30-year fixed mortgage rate equals the 10-Year Treasury Yield + Mortgage Spread (historically 1.50%–2.00%, but widening to ~2.00%–2.50% during periods of high rate volatility).
2. Projected Trajectory: 10-Year Treasuries & Mortgage Rates
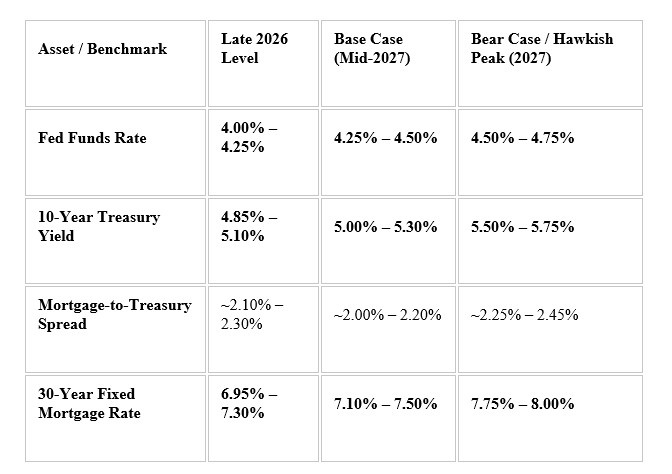
With Wall Street consensus calling for 2 to 3 additional 25 bps Fed hikes pushing rates toward 4.25%–4.75% by early 2027, long-term bond yields are re-anchoring near multi-decade high channels.
3. Key Catalysts Driving Yields Higher Through 2027
Sticky Inflation Premiums: With headline CPI hovering above 3.5%, bond investors demand higher nominal yields to protect real purchasing power over 10-year holding periods.
Massive Treasury Issuance: With federal deficits remaining structurally high, the U.S. Treasury continues issuing large volumes of long-dated bonds. Increased supply requires higher yields to attract sufficient institutional buyer demand.
Persistently Wide Spreads: Elevated rate volatility prevents the mortgage spread from narrowing back to its historical 1.50% average, adding an extra 50 to 80 basis points of borrowing cost onto prospective homebuyers.
#cpi #USJoblessClaimsRise #BinanceSquareTalks #SupportCreators