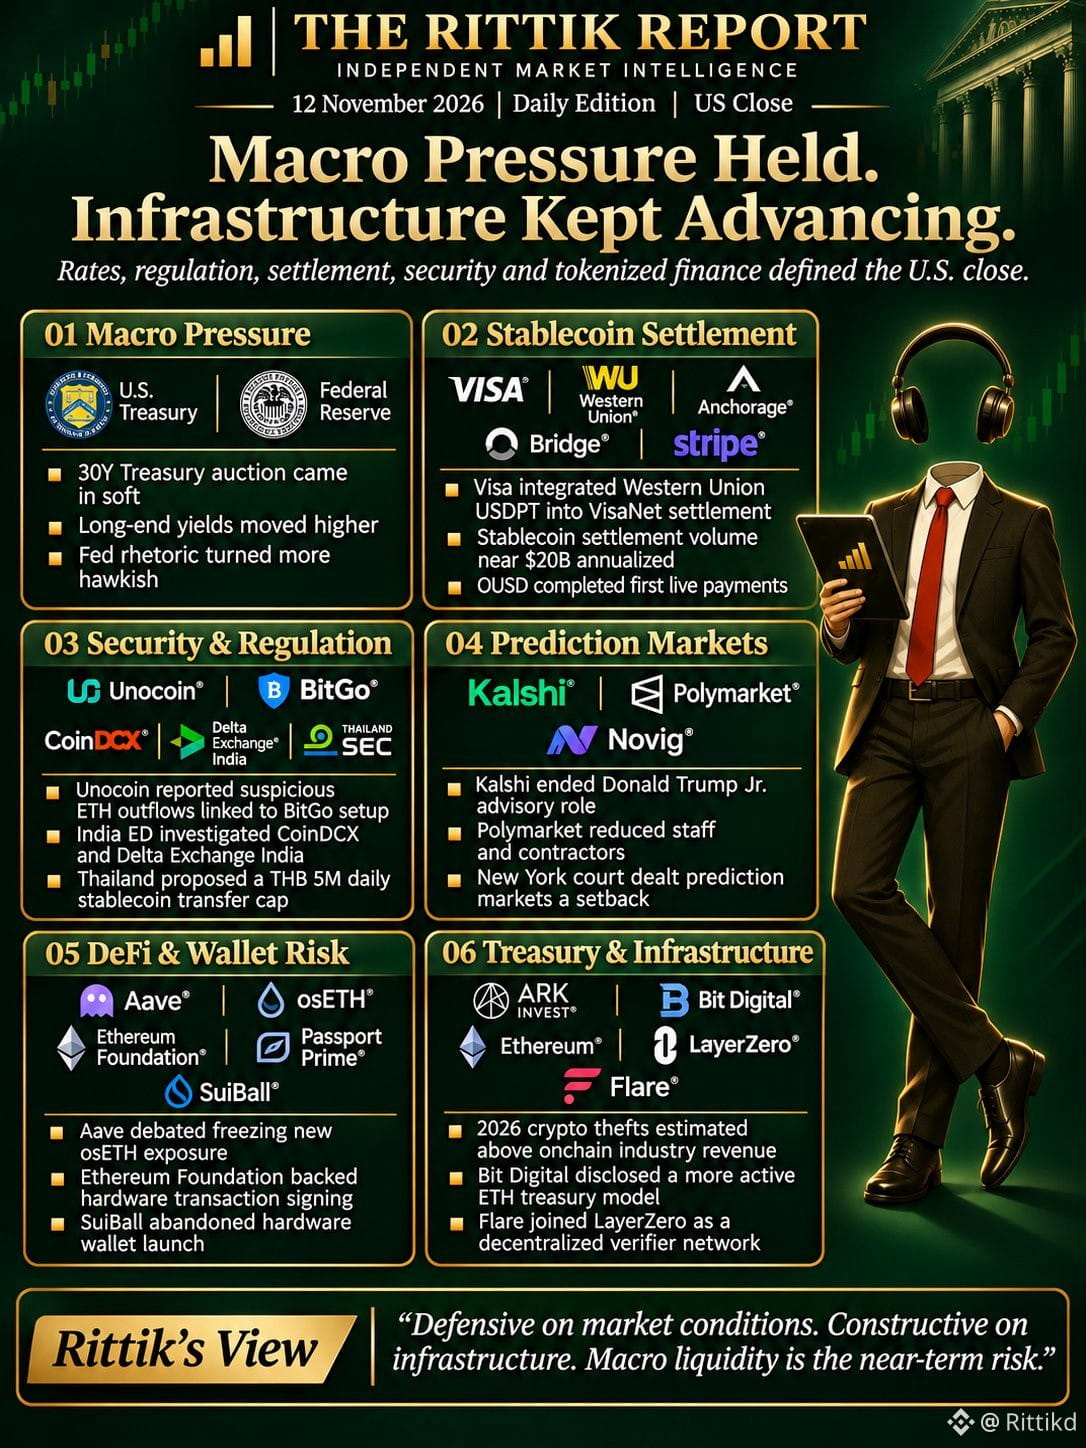
The US session reinforced the macro pressure already visible in the morning. The 30-year Treasury auction was weak, long-end yields remained elevated and Fed officials continued leaning toward tighter policy, leaving crypto without meaningful monetary support.
At the same time, the structural side of the market continued advancing through Visa stablecoin settlement, live OUSD payments, institutional Ethereum treasury strategies and cross-chain infrastructure.
My view remains defensive on market conditions but constructive on infrastructure. The immediate risk is still macro liquidity; the longer-term opportunity remains the gradual integration of stablecoins, tokenization and blockchain settlement into conventional finance.
At the same time, the structural side of the market continued advancing through Visa stablecoin settlement, live OUSD payments, institutional Ethereum treasury strategies and cross-chain infrastructure.
My view remains defensive on market conditions but constructive on infrastructure. The immediate risk is still macro liquidity; the longer-term opportunity remains the gradual integration of stablecoins, tokenization and blockchain settlement into conventional finance.