🏦 $SYRUP: THE REAL BUSINESS BEHIND ONE OF CRYPTO'S STRONGEST RWA PLAYS
While much of DeFi competes for attention, Maple Finance is building something different: institutional on-chain lending backed by real credit activity.
And the numbers deserve attention.
🔍 WHY MAPLE STANDS OUT
1. Institutional lending Maple reported approximately $4.7 billion in assets under management at the end of Q3 2026.
2. Real business activity
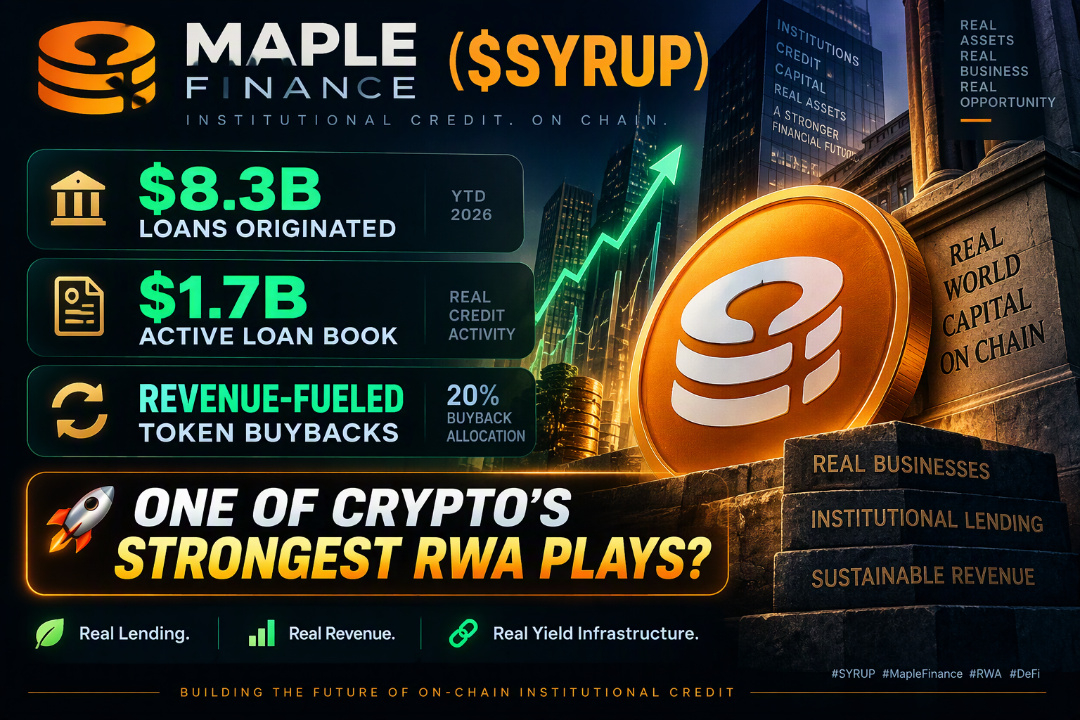
$1.7 billion in outstanding loans.
$8.3 billion in year-to-date loan originations.
$4.4 million Q3 revenue.
Loan book growth while the broader DeFi lending market contracted.
3. Revenue-linked token buybacks Maple introduced MIP-021, connecting SYRUP buybacks to protocol revenue.
September 2026:
1.37 million SYRUP repurchased.
Approximately $314,116 spent.
Buyback allocation increased to 20%.
4. Expanding distribution Maple is expanding its lending infrastructure through partnerships and new strategies, including fintech receivables and lending against rated securities.
🚀 THE BIGGER OPPORTUNITY
The RWA sector is about more than tokenizing government bonds and real estate.
Institutional credit is another enormous opportunity.
Maple is targeting this market with actual lending infrastructure, institutional borrowers and revenue-generating activity.
⚠️ WHAT INVESTORS MUST WATCH
Loan defaults and credit risk.
Sustainable revenue growth.
Token supply and dilution.
Whether buybacks create meaningful long-term value for holders.
Whether SYRUP captures value as the protocol expands.
Buybacks are not dividends or guaranteed returns.
MY TAKE
SYRUP deserves serious consideration among RWA and DeFi investments.
Its strongest advantage is that Maple is building a functioning lending business rather than relying entirely on future adoption promises.
The question isn't simply whether RWA will grow. It's which protocols will generate sustainable revenue from it.
$SYRUP is one project worth watching.
#SYRUP #MapleFinance #RWA #DeFi #InstitutionalFinance #Crypto
While much of DeFi competes for attention, Maple Finance is building something different: institutional on-chain lending backed by real credit activity.
And the numbers deserve attention.
🔍 WHY MAPLE STANDS OUT
1. Institutional lending Maple reported approximately $4.7 billion in assets under management at the end of Q3 2026.
2. Real business activity
$1.7 billion in outstanding loans.
$8.3 billion in year-to-date loan originations.
$4.4 million Q3 revenue.
Loan book growth while the broader DeFi lending market contracted.
3. Revenue-linked token buybacks Maple introduced MIP-021, connecting SYRUP buybacks to protocol revenue.
September 2026:
1.37 million SYRUP repurchased.
Approximately $314,116 spent.
Buyback allocation increased to 20%.
4. Expanding distribution Maple is expanding its lending infrastructure through partnerships and new strategies, including fintech receivables and lending against rated securities.
🚀 THE BIGGER OPPORTUNITY
The RWA sector is about more than tokenizing government bonds and real estate.
Institutional credit is another enormous opportunity.
Maple is targeting this market with actual lending infrastructure, institutional borrowers and revenue-generating activity.
⚠️ WHAT INVESTORS MUST WATCH
Loan defaults and credit risk.
Sustainable revenue growth.
Token supply and dilution.
Whether buybacks create meaningful long-term value for holders.
Whether SYRUP captures value as the protocol expands.
Buybacks are not dividends or guaranteed returns.
MY TAKE
SYRUP deserves serious consideration among RWA and DeFi investments.
Its strongest advantage is that Maple is building a functioning lending business rather than relying entirely on future adoption promises.
The question isn't simply whether RWA will grow. It's which protocols will generate sustainable revenue from it.
$SYRUP is one project worth watching.
#SYRUP #MapleFinance #RWA #DeFi #InstitutionalFinance #Crypto