$GOOGL just printed its worst day ever — and it's still not cheap.
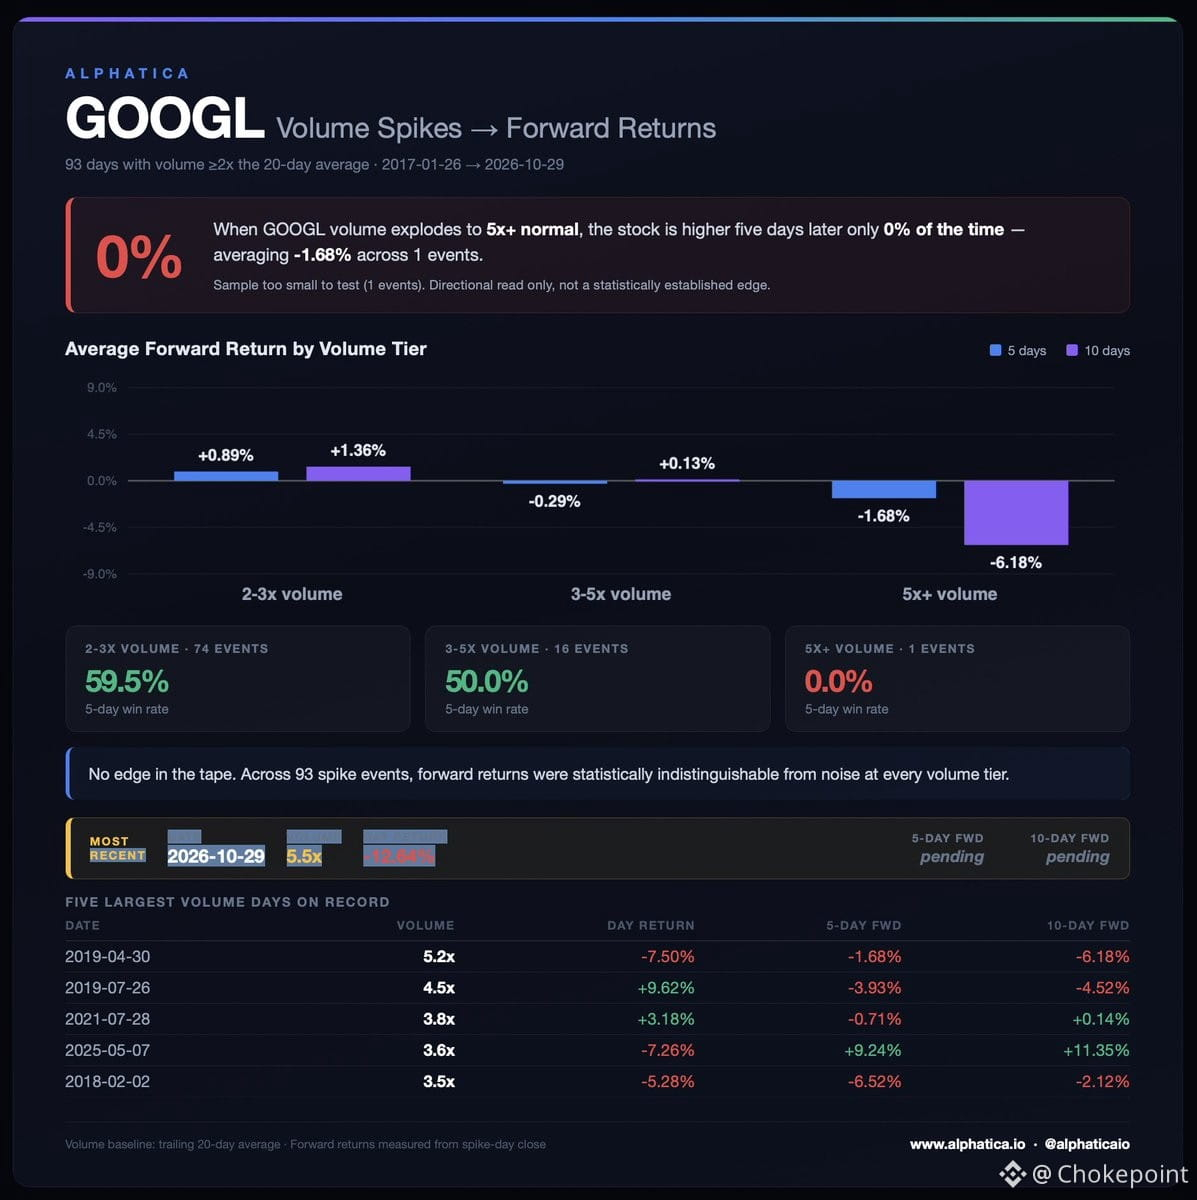
Down 12.6% today, the heaviest single-session loss since the 2014 class listing. Volume ran 5.5x the 20-day average, the most violent selling day on record. Worse than March 2020.
Yet the valuation hasn't cratered:
Trailing P/E sits at 25.6x, right at the six-year median of 25x. Forward P/E is 18.7x on FY27 estimates — historically that's been closer to 17x. And that 18.7x assumes EPS grows 31% into FY27. Meanwhile Q3 normalized EPS actually fell 7% year over year.
The real story is in the post-earnings revision wave:
FY27 capex estimates just jumped to $315B, the fastest pace of upward revisions yet. FY27 free cash flow forecast now sits at negative $38B — compare that to the $60-73B this company used to print annually. EPS revisions flipped from net +31% upgrades to net -15% downgrades in one cycle. Revenue estimates are still rising. 27 analysts cut targets, two raised.
The market isn't doubting AI demand. It's doubting whether Google can earn a return on the spend.
So what's next? The historical playbook is thin. In ten years, $GOOGL has had exactly one other 5x+ volume day: April 2019, which bled another 6.2% over the next ten sessions. Broaden it to every 7%+ drop with heavy volume and the sample splits evenly — two bounced hard (+10%, +4% a month out), two kept falling (-7%, -7%).
On ordinary 2-3x volume spikes, $GOOGL has averaged +1.4% over the next ten sessions (n=74, statistically significant). But today isn't ordinary.
What matters now is whether volume normalizes while price holds — the classic sign forced selling is done — or whether tomorrow brings another 3x+ session and confirms distribution is still live.
$GOOGL $SPY