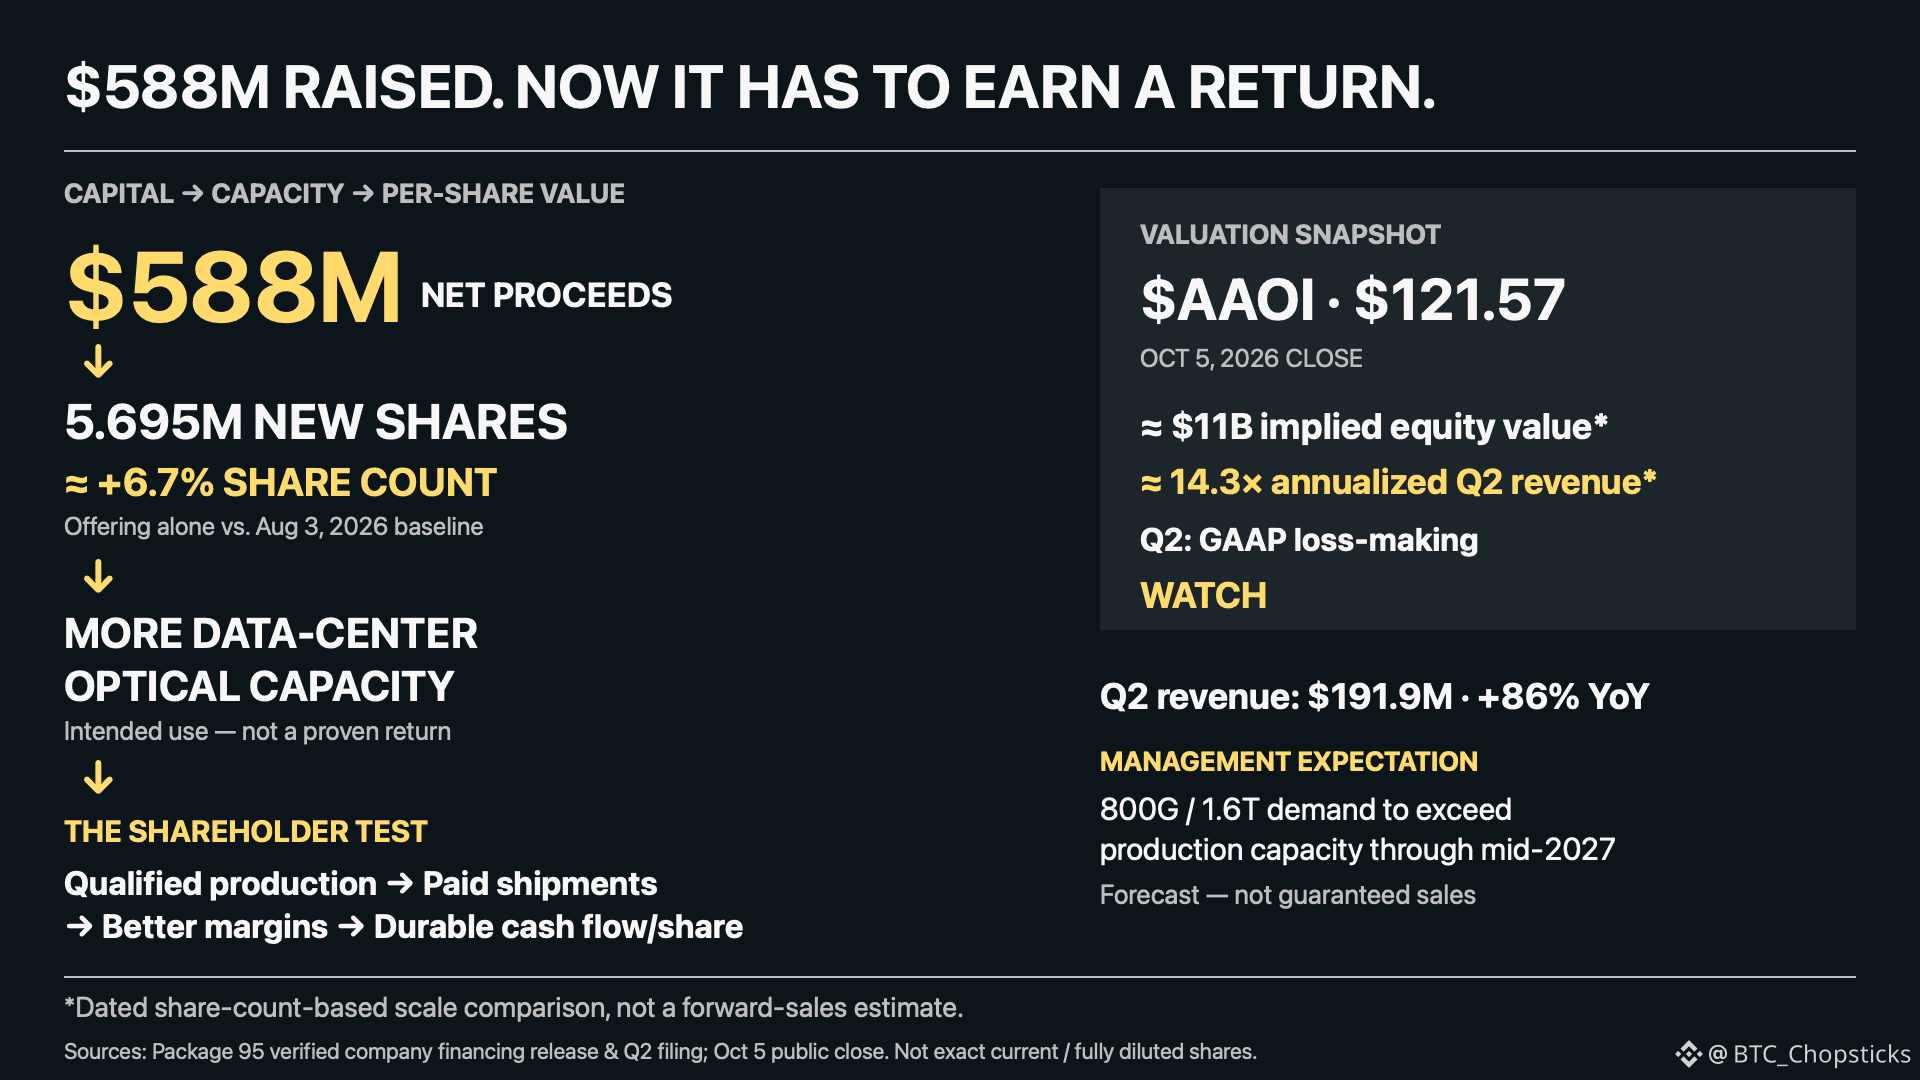
$AAOI raised $588M for its next phase of growth. Shareholders need more than a bigger factory in return.
Applied Optoelectronics issued 5.695M new shares.
The company intends to use the proceeds primarily for data-center optical manufacturing expansion, alongside working capital and possible debt repayment.
There is a real demand case: Q2 revenue reached $191.9M, +86% YoY, and management expects demand for 800G and 1.6T optics to exceed production capacity through mid-2027.
But that's a forecast, not guaranteed sales.
Against the August 3 share-count baseline, this issuance alone adds roughly 6.7% more shares.
Once earnings are positive, total earnings would need to grow by roughly that amount just to keep EPS unchanged, all else equal. Creating value requires more than preserving EPS.
At the Oct. 5 close of $121.57, the dated share-count reference adjusted for this offering implies roughly $11B of equity value, or about 14.3× Q2 revenue annualized.
That's a scale comparison, not a forward-sales estimate. AAOI was still GAAP loss-making in Q2.
My decision: WATCH.
What I want to see:
New equipment → qualified production → paid shipments → better margins → durable cash flow per share.
Delayed ramps, pricing pressure or repeated issuance without improving cash economics would weaken the thesis.
AI optics demand can be real while the stock already prices in too much execution. The financing is complete. The return shareholders get for it isn't.