The $SPY looks cheap only if you believe in a margin expansion that's never happened before.
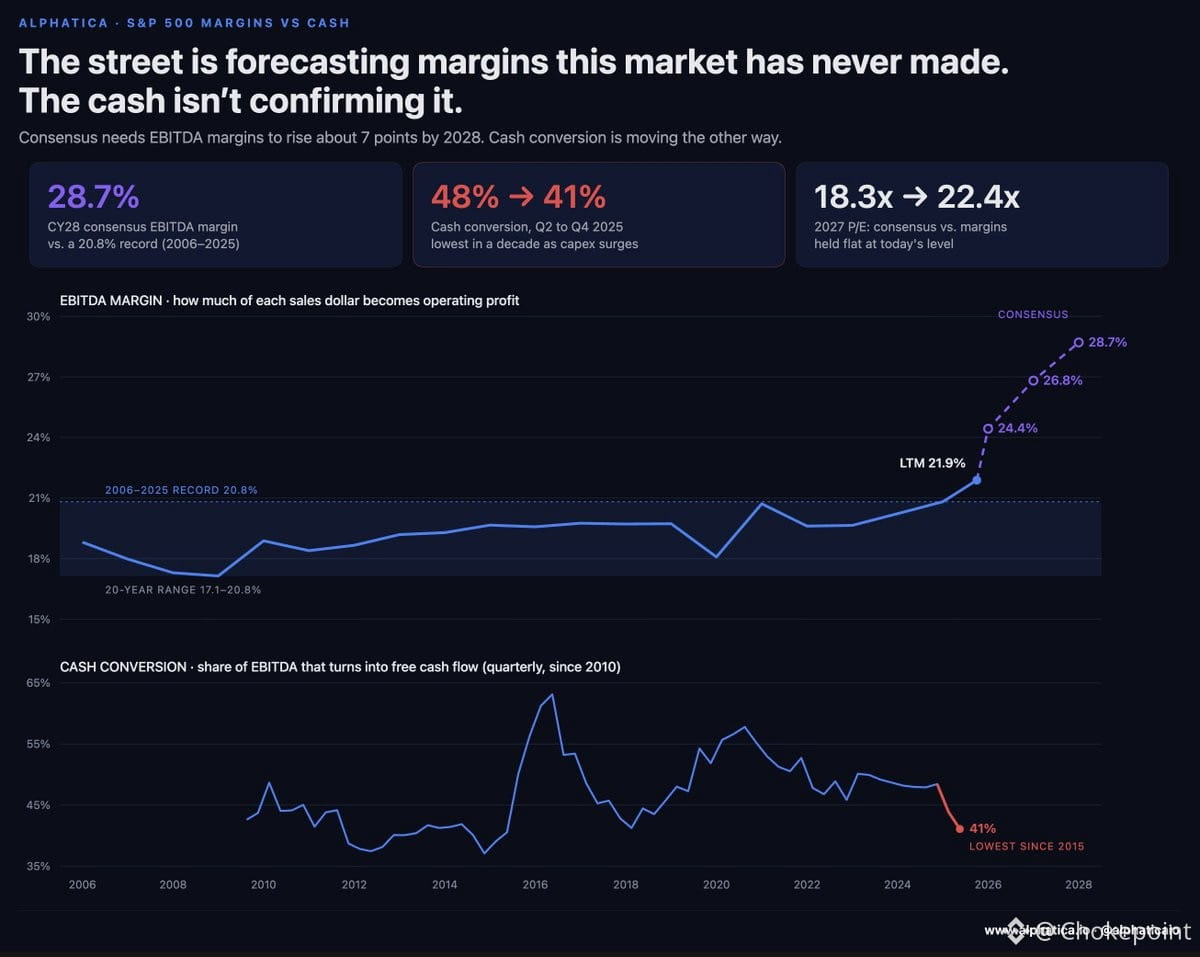
Consensus is modeling 28.7% EBITDA margins by 2028. The 20-year high? 20.8%. That's not a stretch — it's a fantasy.
Meanwhile, free cash flow as a percentage of EBITDA just dropped from 48% to 41% in two quarters. Lowest since 2015. That's the capex bill coming due — AI buildout, data centers, infrastructure. And here's the thing: capex doesn't vanish. It rolls back through the P&L as depreciation, eating straight into the margins Wall Street is pricing in.
On consensus numbers, the S&P trades at 18.3x 2027 earnings. But if margins just stay flat — forget compression — that multiple jumps to 22.4x. Not exactly a bargain.
The market isn't pricing growth. It's pricing a margin miracle that requires record profitability while capex intensity is rising and cash conversion is falling. Something has to give.
What breaks first — earnings estimates or the multiple?