
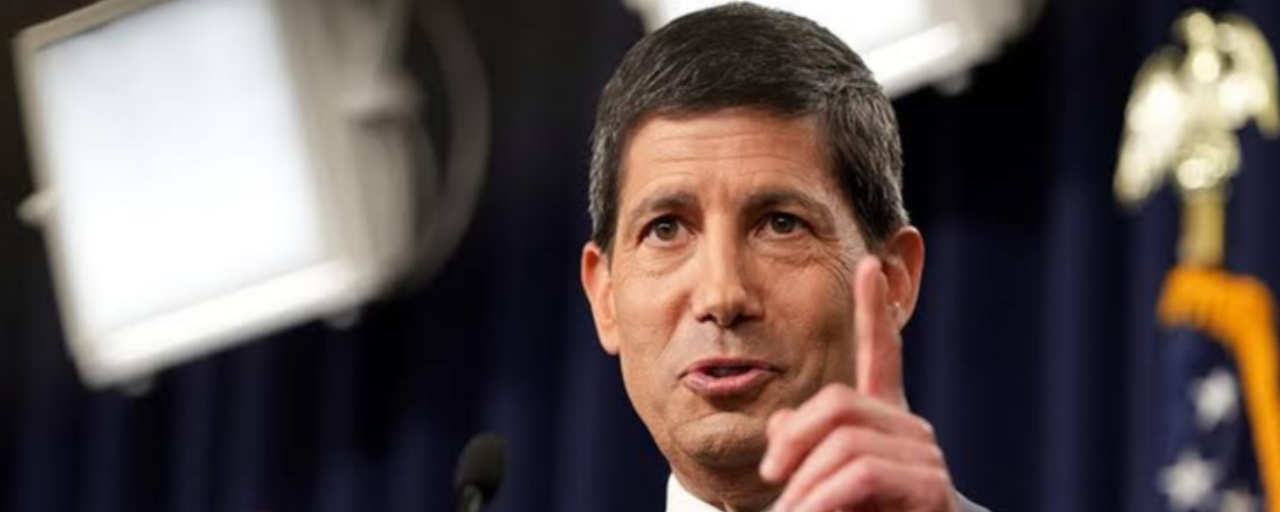
Kevin Warsh, Chairman of the Federal Reserve and a voting member of the Federal Open Market Committee (FOMC) in 2026 through his permanent seat on the Board of Governors, took questions at the post-meeting press conference in Washington after the FOMC raised the federal funds rate by 25 basis points to a target range of 3.75%-4%, the first increase since 2023. Sixteen of 18 policymakers penciled in another quarter-point hike before year-end.
Warsh set the tone immediately: inflation risks are to the upside, he said, while labor risks are balanced. Too many categories are posting increases above 3% on both a six- and twelve-month basis, he added, and the summer data hasn't shown him that the inflation situation has improved. Trends matter, he stressed; data points are noisy.
He called the decision itself a sober one. Today's action, he told reporters, stands to show the committee is serious about the fight, and the Fed decided to remove a dose of accommodation. He broke from convention on one point, revealing he did not submit a dot this round, declining to lay out his own rate path while refusing to rule anything out for future meetings.
Turning to the labor market, Warsh struck a calmer note, saying the labor market is more or less at full employment in aggregate and that he doesn't believe the Fed needs to do harm to the job market to achieve its objective.
He credited the broader backdrop for giving the Fed room to move: seven weeks of data since the last meeting show the economy has strengthened, and that underlying strength lets policymakers afford to focus on price stability.
On bond yields, Warsh pointed to three drivers: economic strength, competition for capital tied to a real surge in CAPEX, and geopolitics. He kept his comments on AI brief, noting the Fed cares very much about what's happening in the space and that its internal task force should report back by year-end.
Warsh closed by keeping a tight lid on politics, saying he had nothing for reporters on any discussion with the President and declining to comment on the ECB or other central banks' policy.
Key Quotes:
Monetary Policy
Today's action stands to show that we are serious about delivering price stability.
We decided to remove a dose of accommodation to the economy.
In July, we expressed a joint readiness to act.
The decision we made today was a sober decision.
I am not in the forward guidance business.
I did not submit a dot.
I am not going to prejudge any future decision we may make.
I have always been interested in a neutral rate academically, but I don't see it having an operational effect on decisions today.
Inflation
Inflation risks are to the upside, labor risks are balanced.
We must be confident that underlying inflation must be moving to 2% on a timely basis, and the FOMC decided this has not been met.
There are too many categories that are posting increases above 3% on both 6 and 12 month basis.
The summer data does not tell me that the inflation situation has improved.
Trends matter, data points are noisy.
I was not waiting breathlessly on any one data point, including CPI.
nflation trends were not passing the test, and I have seen little to no change there.
We will ensure any changes in prices won't broaden out.
Other advanced economies are suffering from price pressures, too.
Labor Market
In aggregate, we're more or less at full employment.
I don't believe we need to do harm to the job market to achieve our objective."
Growth & Economy
What happened in the 7 weeks since we last met, data has shown that the economy has strengthened.
Because of the underlying strength of the economy, we can afford to focus on price stability.
Financial Conditions
My colleagues are hard-pressed to describe financial conditions as restrictive, so we decided to remove a dose of accommodation.
I see 3 reasons bond yields have risen: the first is economic strength, the second is competition for capital, the surge in CAPEX is real, and the third is geopolitics.
AI & Productivity
We care very much about what's happening in AI.
The taskforce should report to us about AI by the year-end.
Fed Transparency & Accountability
I have nothing for you about a discussion with the President.
Declined to comment on ECB and other central banks' policy.