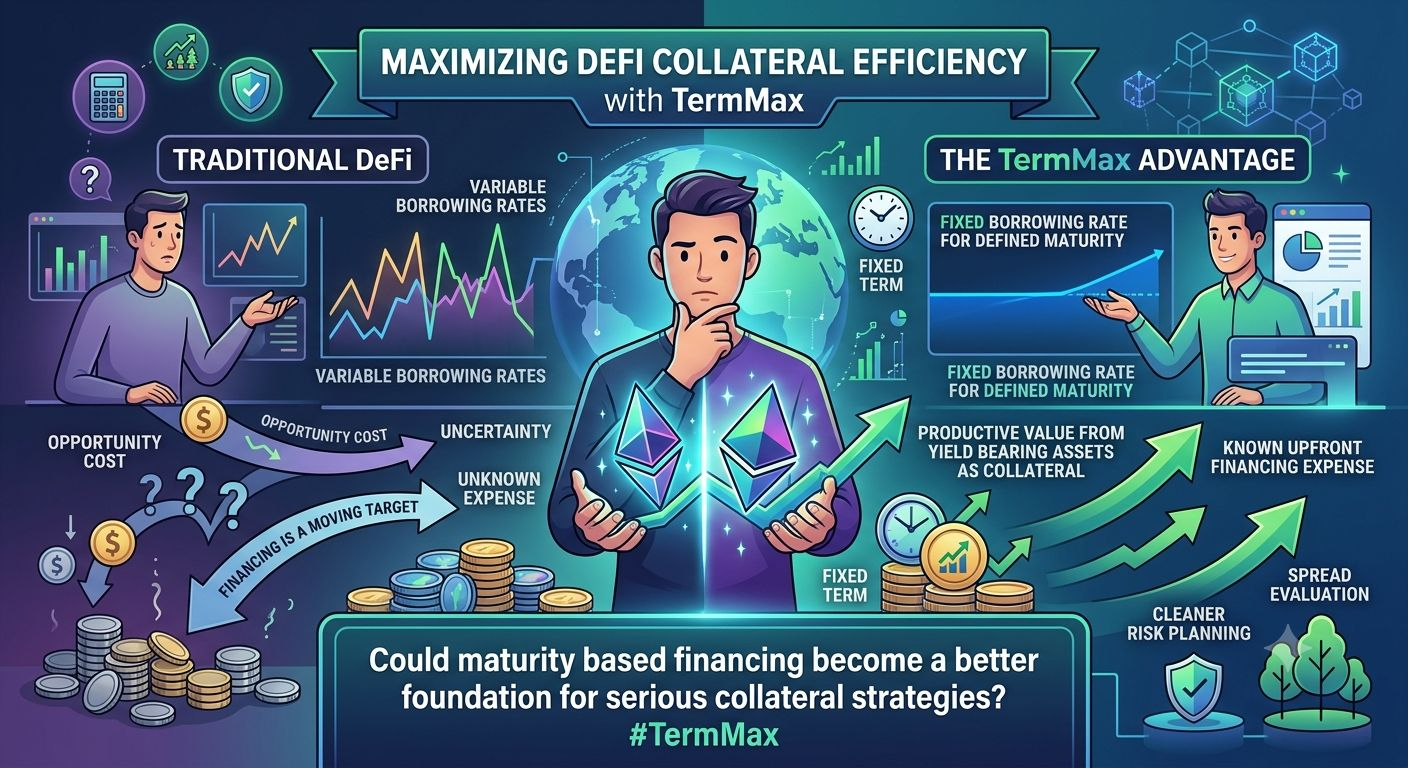
What stands out to me about @TermMax is the possibility of making collateral work harder without turning financing into a moving target. In many DeFi strategies, capital sitting as collateral can still have an opportunity cost, while borrowing costs can change as market conditions shift. TermMax approaches this differently by supporting yield bearing assets as collateral while keeping borrowing rates fixed for a defined maturity. For me, that creates a more interesting question around capital efficiency: how much productive value can I get from the same pool of capital when the financing expense is known upfront? #TermMax
The trade off is that fixed term financing requires me to think about maturity instead of treating liquidity as permanently available. I have to match the borrowing period with my strategy and understand what happens when the position reaches maturity. But that constraint can also make risk planning much cleaner. If my collateral is generating yield while my borrowing cost stays fixed, I can evaluate the spread with clearer assumptions rather than relying on a rate that may move against me. I see that as a useful structure for traders who care about capital efficiency without wanting interest rate changes to constantly rewrite the economics of a position. The question is whether maturity based financing could become a better foundation for serious collateral strategies.
The trade off is that fixed term financing requires me to think about maturity instead of treating liquidity as permanently available. I have to match the borrowing period with my strategy and understand what happens when the position reaches maturity. But that constraint can also make risk planning much cleaner. If my collateral is generating yield while my borrowing cost stays fixed, I can evaluate the spread with clearer assumptions rather than relying on a rate that may move against me. I see that as a useful structure for traders who care about capital efficiency without wanting interest rate changes to constantly rewrite the economics of a position. The question is whether maturity based financing could become a better foundation for serious collateral strategies.