
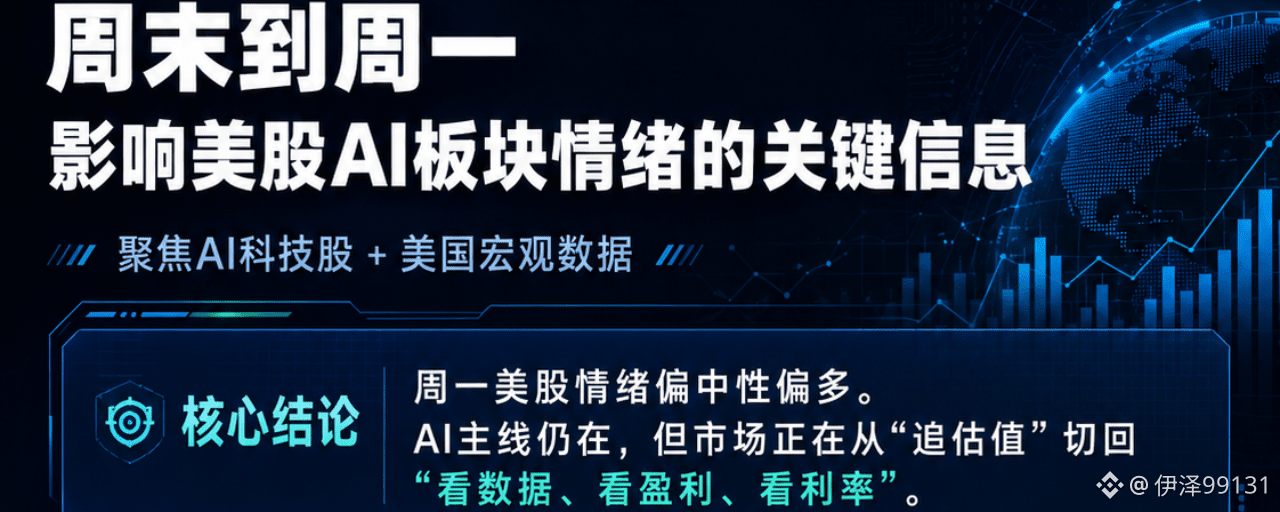

Weekend → Monday U.S. Market Brief
🟢 Bullish developments
Middle East tensions eased, supporting risk assets
The biggest macro driver into Monday is a reported de-escalation between the U.S. and Iran after weekend military exchanges. Markets interpreted the latest developments as reducing the probability of a prolonged disruption to oil shipping. U.S. equity futures, especially Nasdaq futures, moved higher before the open as investors rotated back toward growth assets. (Reuters)
Most positive for
$NVDA $AMD $AVGO $MRVL $ARM
Oil remains well below panic levels
Despite geopolitical headlines, oil has remained relatively contained instead of spiking dramatically.
Lower energy prices generally:
reduce inflation pressure
improve expectations for future Fed policy benefit long-duration growth stocks This is particularly supportive for AI infrastructure names whose valuations are sensitive to interest rates. (Reuters)
AI infrastructure spending remains the dominant long-term theme
Although investors have become more selective, reports continue to highlight that semiconductor and memory companies have been the strongest-performing segment of 2026.
Companies still benefiting from AI capex include:
NVDA MU WDC STX SK Hynix Samsung
The market narrative remains centered on AI infrastructure rather than consumer AI software. (The Guardian)
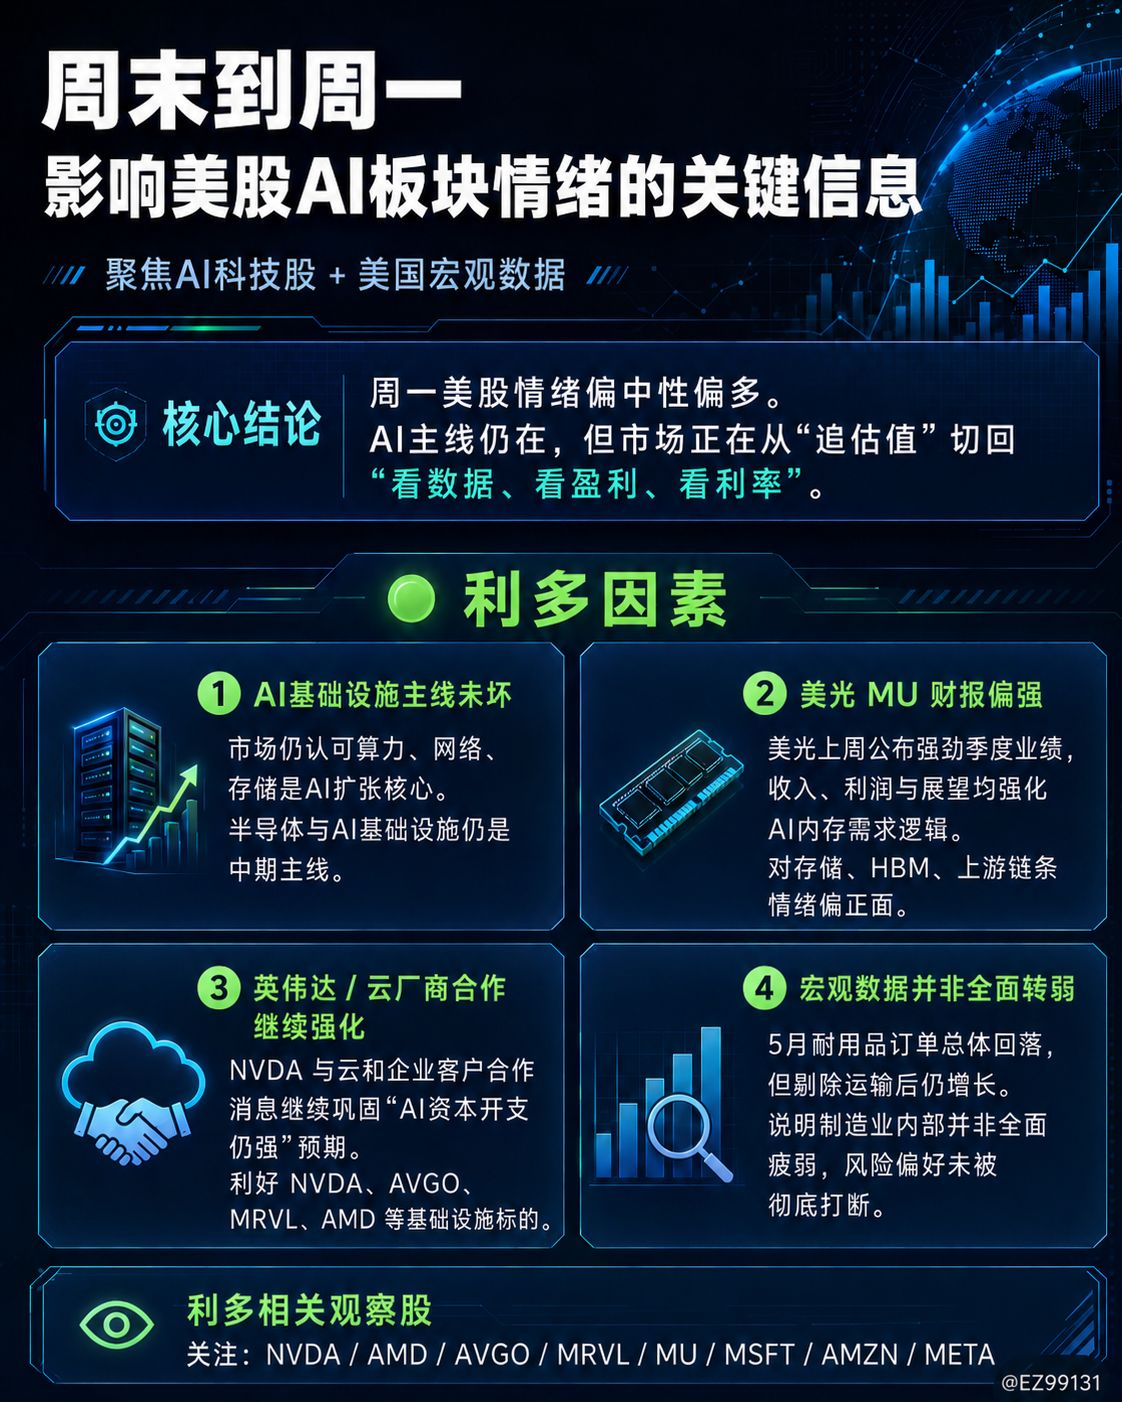
🔴 Bearish developments
AI valuation concerns continue
The largest headwind remains valuation.
Investors continue questioning:
whether hyperscalers can maintain AI spending
when AI investments generate meaningful cash flow
whether current semiconductor multiples are sustainable
Profit-taking has continued across many AI leaders after an exceptional first half of the year. (Reuters) 2. Rising-rate concerns remain Although geopolitical risks eased, markets are still focused on inflation and Fed policy.
Recent commentary has kept alive expectations that rates could stay higher for longer if inflation proves persistent.
Higher real yields are generally negative for:
NVDA MSFT AMZN GOOGL META other long-duration AI names.
Rotation away from mega-cap AI Several reports note that: semiconductor stocks have significantly outperformed investors have started rotating into other sectors
software and mega-cap AI names have underperformed recently
This does not necessarily imply the AI cycle is ending, but it increases short-term volatility. (The Guardian)
AI company-specific updates
NVIDIA (NVDA) No major company announcement over the weekend. Remains highly sensitive to macro sentiment and AI capex expectations.
Likely to trade with Nasdaq direction and Treasury yields.
Marvell (MRVL)
No significant company-specific news.
Continues trading primarily on AI networking and custom silicon sentiment.
Broadcom (AVGO) No major weekend developments. AMD
No significant company-specific catalyst.
Micron (MU) No new guidance since last week's earnings.
Still viewed as one of the strongest beneficiaries of AI memory demand despite recent profit-taking. (Reuters)
Nokia (NOK)
No meaningful AI-related news over the weekend.
SHAZ
No significant new company announcement over the weekend.
Earnings / Guidance No major AI-company earnings or guidance updates over the weekend.
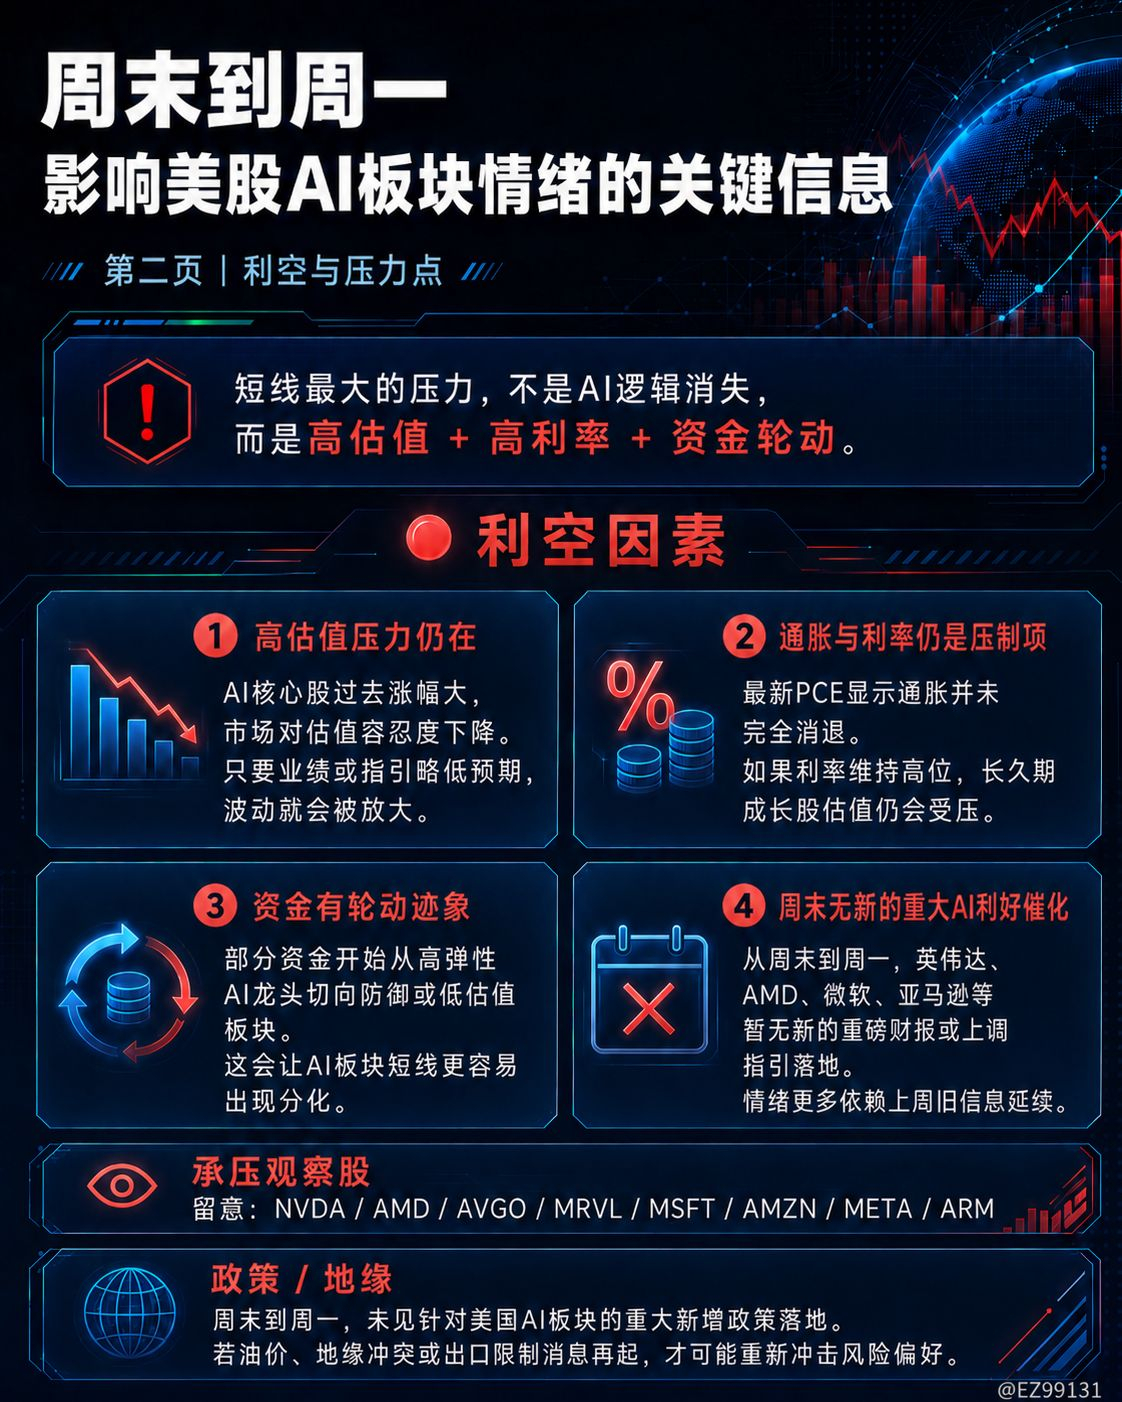
Macro events to watch this week
This is a shortened trading week.
Key events include:
Tuesday: Consumer Confidence, JOLTS job openings
Wednesday: ADP employment, ISM Manufacturing PMI
Thursday: U.S. Nonfarm Payrolls, Unemployment Rate, Average Hourly Earnings (released early because of the Independence Day holiday)
Friday: U.S. equity markets closed for Independence Day observance. (Schwab Brokerage)
These labor-market reports are likely to be the biggest drivers of Treasury yields and AI stock performance this week.
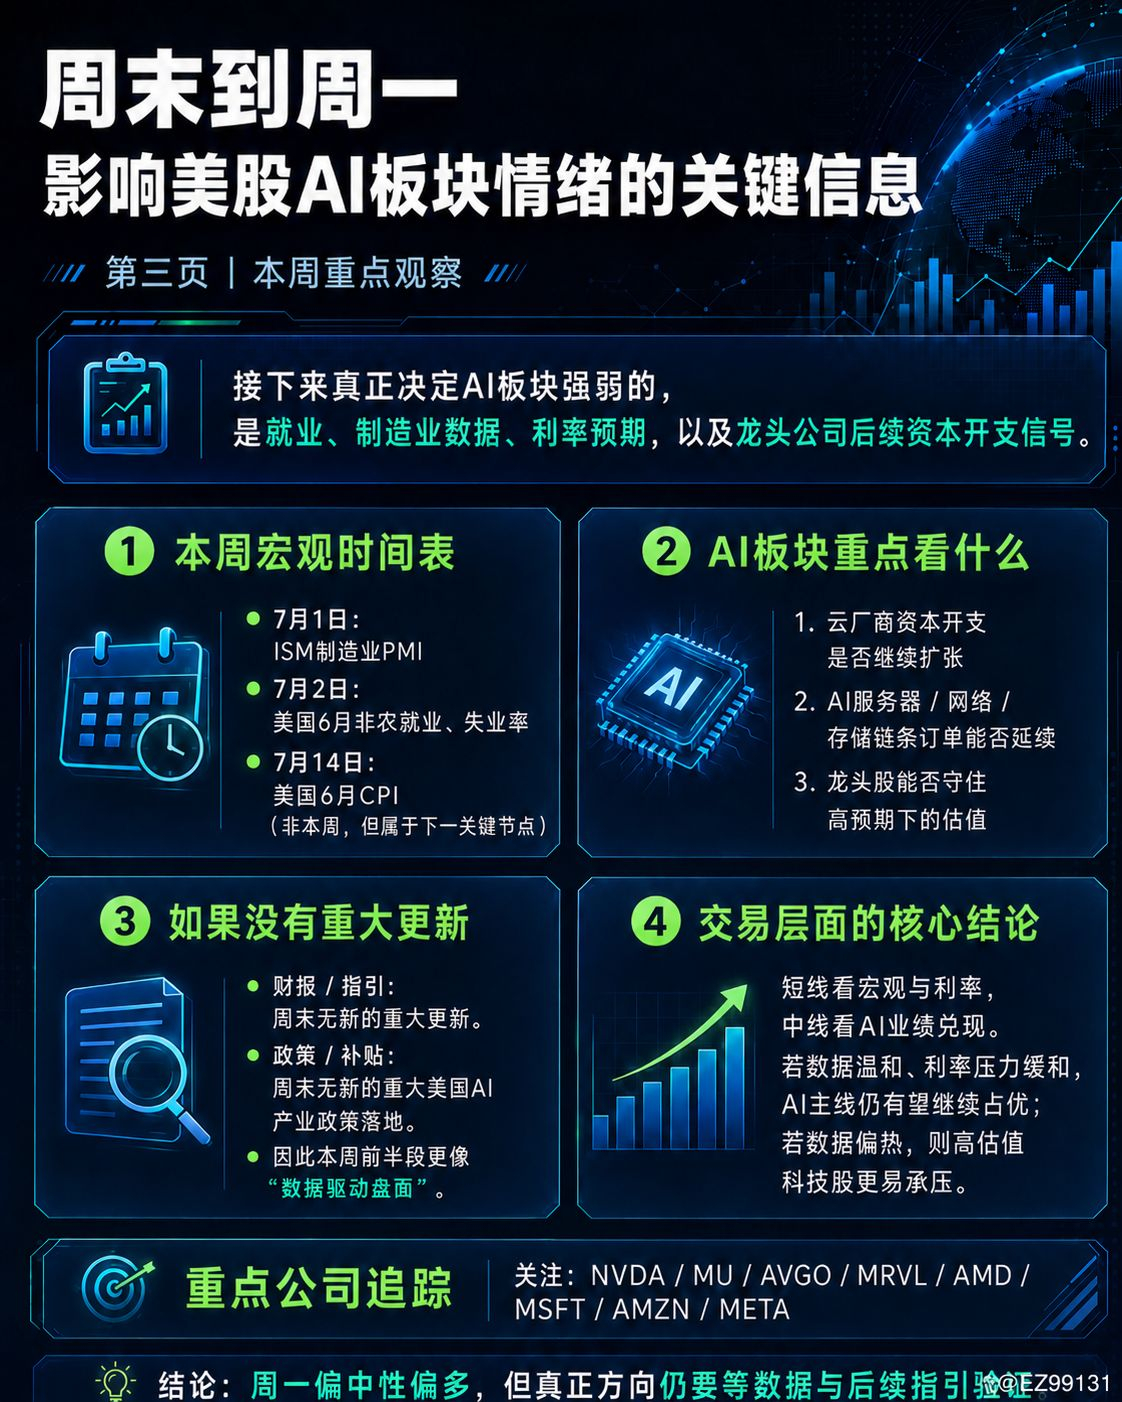
Policy / Geopolitics
Positive
Reported U.S.–Iran de-escalation reduced immediate fears of a prolonged conflict and major disruption in the Strait of Hormuz. (Reuters)
Risk remains The ceasefire and diplomatic progress remain fragile, and markets could react quickly if tensions escalate again. (Reuters) Overall sentiment for Monday Bullish factors
✅ Reduced geopolitical stress
✅ Stable oil prices
✅ Strong long-term AI infrastructure demand
Bearish factors
⚠️ Continued valuation pressure on AI leaders
⚠️ Higher-for-longer rate concerns
⚠️ Profit-taking after a very strong first half for semiconductor stocks
The backdrop into Monday is moderately constructive for U.S. AI stocks because easing geopolitical tensions and relatively contained oil prices support risk appetite. However, the market's focus is shifting from geopolitical headlines back to Fed expectations, labor-market data, and the sustainability of AI capital spending, which are likely to determine whether the AI sector can regain momentum later in the week.