
#ipo
ipo
Просмотров: 947,522
3,633 обсуждают
Популярные
Новые
·
--
Проверено
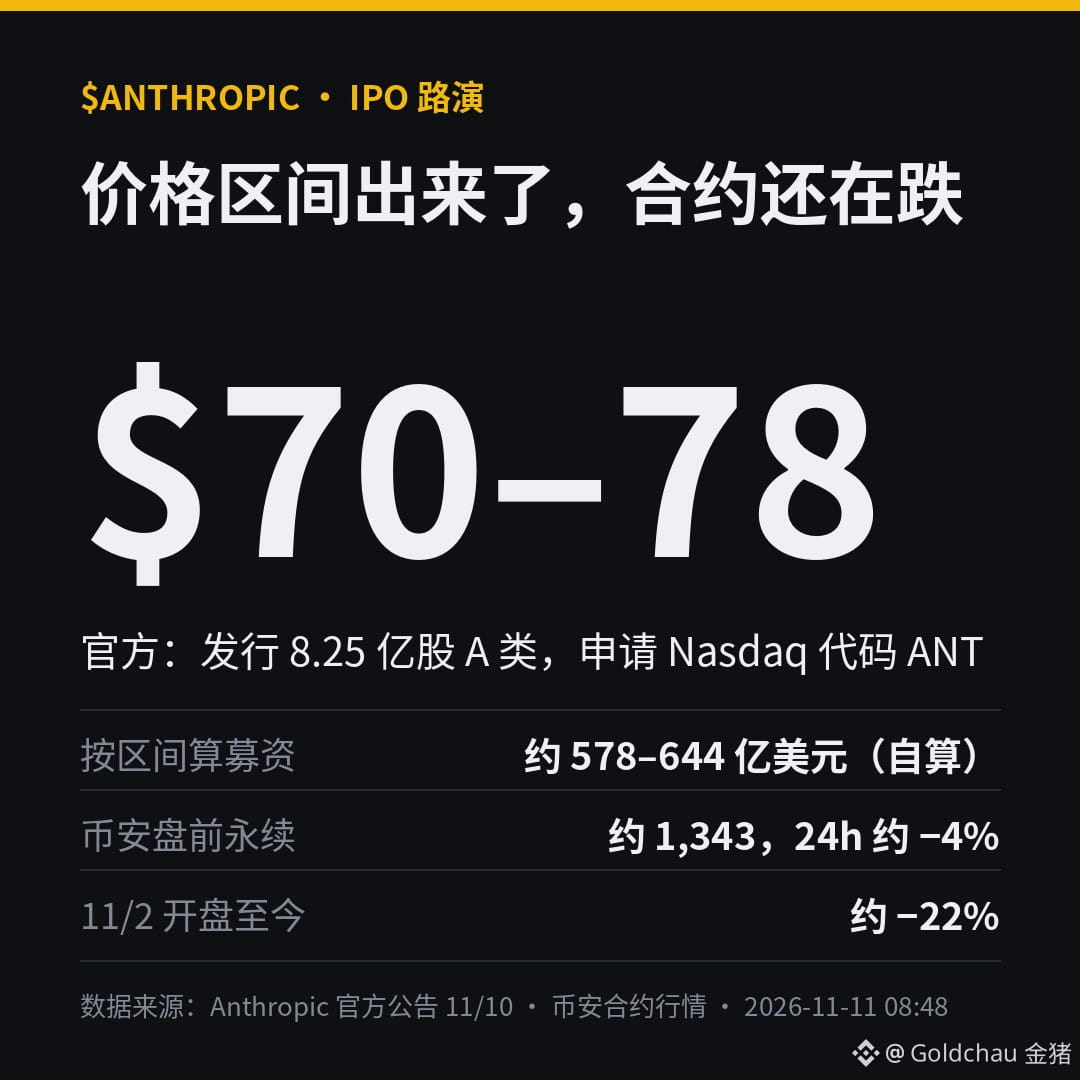
金猪判断:$ANTHROPIC 的 IPO 价格区间终于出来了,盘前合约却还在往下走——我偏多,但只在回踩时分批,不追。
Anthropic 官方 11/10 启动路演:发行 8.25 亿股 A 类股,价格区间 70–78 美元,申请 Nasdaq 代码 ANT。注册声明还没生效,最终定价没出。
币安盘前永续现在约 1,343,24h 约 −4%;从 11/2 开盘约 1,724 算,已经跌了约 22%。
我的理解:区间落地 = 最大的不确定性少了一个,合约这一路跌更像是先把估值泡沫挤掉,不是 AI 故事没了。
我的计划:昨天低点约 1,254 附近小仓试多,跌破 1,250 认错走;站回约 1,420(昨天高点)再加。
提醒:盘前永续不是股票,也不代表持有 Anthropic 股份,价格可能和上市后的股价对不上,仓位和杠杆一定控制好。
IPO 定价前这几天,你打算怎么安排自己在 $ANTHROPIC 上的仓位?
#Anthropic #IPO #AI $ANTHROPIC
数据来源:Anthropic 官方公告、币安合约行情。DYOR,不构成投资建议。
金猪判断:$ANTHROPIC 的 IPO 价格区间终于出来了,盘前合约却还在往下走——我偏多,但只在回踩时分批,不追。
Anthropic 官方 11/10 启动路演:发行 8.25 亿股 A 类股,价格区间 70–78 美元,申请 Nasdaq 代码 ANT。注册声明还没生效,最终定价没出。
币安盘前永续现在约 1,343,24h 约 −4%;从 11/2 开盘约 1,724 算,已经跌了约 22%。
我的理解:区间落地 = 最大的不确定性少了一个,合约这一路跌更像是先把估值泡沫挤掉,不是 AI 故事没了。
我的计划:昨天低点约 1,254 附近小仓试多,跌破 1,250 认错走;站回约 1,420(昨天高点)再加。
提醒:盘前永续不是股票,也不代表持有 Anthropic 股份,价格可能和上市后的股价对不上,仓位和杠杆一定控制好。
IPO 定价前这几天,你打算怎么安排自己在 $ANTHROPIC 上的仓位?
#Anthropic #IPO #AI $ANTHROPIC
数据来源:Anthropic 官方公告、币安合约行情。DYOR,不构成投资建议。
Anthropic 官方 11/10 启动路演:发行 8.25 亿股 A 类股,价格区间 70–78 美元,申请 Nasdaq 代码 ANT。注册声明还没生效,最终定价没出。
币安盘前永续现在约 1,343,24h 约 −4%;从 11/2 开盘约 1,724 算,已经跌了约 22%。
我的理解:区间落地 = 最大的不确定性少了一个,合约这一路跌更像是先把估值泡沫挤掉,不是 AI 故事没了。
我的计划:昨天低点约 1,254 附近小仓试多,跌破 1,250 认错走;站回约 1,420(昨天高点)再加。
提醒:盘前永续不是股票,也不代表持有 Anthropic 股份,价格可能和上市后的股价对不上,仓位和杠杆一定控制好。
IPO 定价前这几天,你打算怎么安排自己在 $ANTHROPIC 上的仓位?
#Anthropic #IPO #AI $ANTHROPIC
数据来源:Anthropic 官方公告、币安合约行情。DYOR,不构成投资建议。
爱吃熊的蜂蜜:
这个盘前发行了之后会变成什么呀
6
5
3k

·
--
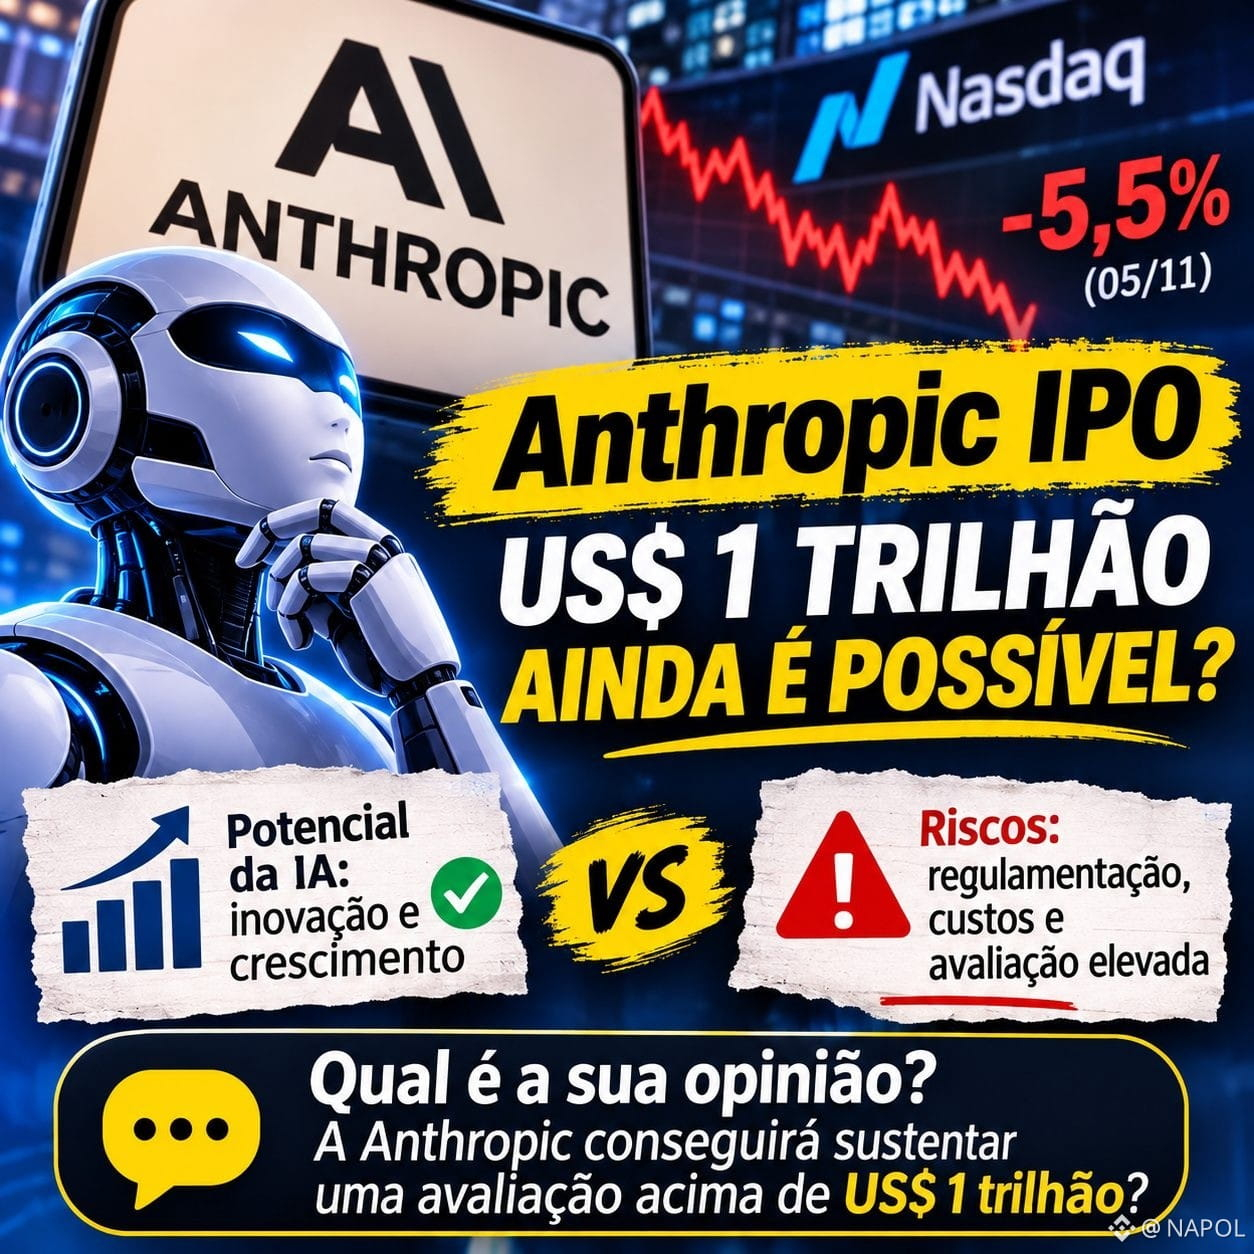
Anthropic IPO: US$ 1 trilhão ainda é uma avaliação possível?
Na minha opinião, a Anthropic tem potencial para se tornar uma das empresas mais importantes da nova economia da inteligência artificial. Porém, uma avaliação de US$ 1 trilhão ou mais exige muito mais do que expectativas e entusiasmo com o setor.
A revisão das projeções, de US$ 2 trilhões para aproximadamente US$ 1,5 trilhão, mostra que o mercado está começando a olhar com mais cautela para esse crescimento.
A IA continua sendo uma das grandes transformações tecnológicas da nossa geração, mas isso não significa que todas as empresas do setor estejam protegidas contra correções.
Também precisamos observar os custos de infraestrutura, a concorrência, a rentabilidade e as possíveis restrições regulatórias aos data centers.
Minha opinião: não acredito que o potencial da IA seja uma bolha por si só. Mas acredito que algumas avaliações podem estar muito à frente dos resultados que essas empresas conseguem entregar atualmente.
A Anthropic poderá surpreender, mas será que o mercado está preparado para pagar esse preço?
$ANTHROPIC $HAEDAL
#AnthropicIPO #AnthropicRejectsIPODelayValuationinQuestion #IPO
Anthropic IPO: US$ 1 trilhão ainda é uma avaliação possível?
Na minha opinião, a Anthropic tem potencial para se tornar uma das empresas mais importantes da nova economia da inteligência artificial. Porém, uma avaliação de US$ 1 trilhão ou mais exige muito mais do que expectativas e entusiasmo com o setor.
A revisão das projeções, de US$ 2 trilhões para aproximadamente US$ 1,5 trilhão, mostra que o mercado está começando a olhar com mais cautela para esse crescimento.
A IA continua sendo uma das grandes transformações tecnológicas da nossa geração, mas isso não significa que todas as empresas do setor estejam protegidas contra correções.
Também precisamos observar os custos de infraestrutura, a concorrência, a rentabilidade e as possíveis restrições regulatórias aos data centers.
Minha opinião: não acredito que o potencial da IA seja uma bolha por si só. Mas acredito que algumas avaliações podem estar muito à frente dos resultados que essas empresas conseguem entregar atualmente.
A Anthropic poderá surpreender, mas será que o mercado está preparado para pagar esse preço?
$ANTHROPIC $HAEDAL
#AnthropicIPO #AnthropicRejectsIPODelayValuationinQuestion #IPO
Na minha opinião, a Anthropic tem potencial para se tornar uma das empresas mais importantes da nova economia da inteligência artificial. Porém, uma avaliação de US$ 1 trilhão ou mais exige muito mais do que expectativas e entusiasmo com o setor.
A revisão das projeções, de US$ 2 trilhões para aproximadamente US$ 1,5 trilhão, mostra que o mercado está começando a olhar com mais cautela para esse crescimento.
A IA continua sendo uma das grandes transformações tecnológicas da nossa geração, mas isso não significa que todas as empresas do setor estejam protegidas contra correções.
Também precisamos observar os custos de infraestrutura, a concorrência, a rentabilidade e as possíveis restrições regulatórias aos data centers.
Minha opinião: não acredito que o potencial da IA seja uma bolha por si só. Mas acredito que algumas avaliações podem estar muito à frente dos resultados que essas empresas conseguem entregar atualmente.
A Anthropic poderá surpreender, mas será que o mercado está preparado para pagar esse preço?
$ANTHROPIC $HAEDAL
#AnthropicIPO #AnthropicRejectsIPODelayValuationinQuestion #IPO
2
123

·
--
【史上最大 IPO 被抢疯了,币安 Anthropic 合约却从高点跌近四成!】
Claude 母公司 Anthropic 本次 IPO 招股价每股 70 至 78 美元,连同私募最多募资约 904 亿美元,比 SpaceX 还多,据报认购已超额数倍,预计 11 月 18 日定价、19 日在纳斯达克上市;币安 Anthropic 盘前永续合约却从 9 月 9 日约 2228 的高点一路跌到现在约 1375、跌约 38%,按币安口径对应估值约 1.37 万亿美元。
#Anthropic #IPO #美股
【史上最大 IPO 被抢疯了,币安 Anthropic 合约却从高点跌近四成!】
Claude 母公司 Anthropic 本次 IPO 招股价每股 70 至 78 美元,连同私募最多募资约 904 亿美元,比 SpaceX 还多,据报认购已超额数倍,预计 11 月 18 日定价、19 日在纳斯达克上市;币安 Anthropic 盘前永续合约却从 9 月 9 日约 2228 的高点一路跌到现在约 1375、跌约 38%,按币安口径对应估值约 1.37 万亿美元。
#Anthropic #IPO #美股
Claude 母公司 Anthropic 本次 IPO 招股价每股 70 至 78 美元,连同私募最多募资约 904 亿美元,比 SpaceX 还多,据报认购已超额数倍,预计 11 月 18 日定价、19 日在纳斯达克上市;币安 Anthropic 盘前永续合约却从 9 月 9 日约 2228 的高点一路跌到现在约 1375、跌约 38%,按币安口径对应估值约 1.37 万亿美元。
#Anthropic #IPO #美股
166
#anthropicrejectsipodelayvaluationinquestion
🚨 ANTHROPIC REFUSES TO SLOW DOWN: $1.4 TRILLION IPO FACES A MAJOR TEST!
Despite growing investor concerns and pressure to reconsider its IPO timing, Anthropic is pushing ahead with its highly anticipated stock market debut.
The company behind Claude AI has moved forward with an updated filing, proposing to offer 825 million shares at an estimated $70–$78 per share.
🔥 Why Is the IPO Raising Concerns?
Anthropic's potential valuation could reach approximately $1.4 trillion.
Earlier expectations reportedly placed its valuation as high as $2 trillion.
Some investors believe the valuation is too aggressive.
Market volatility and concerns about AI spending are creating additional pressure.
The IPO could raise up to $64.35 billion through the public offering.
Why Does This Matter?
Anthropic's IPO could become a major test of investor confidence in the AI industry.
If demand is strong, it could restore confidence in high-value AI companies. But weak demand could signal that investors are becoming more cautious about expensive AI valuations.
One question remains: Is $1.4 trillion a fair price for Anthropic, or is the AI hype getting ahead of reality?
#Anthropic #Aİ #IPO
#anthropicrejectsipodelayvaluationinquestion
🚨 ANTHROPIC REFUSES TO SLOW DOWN: $1.4 TRILLION IPO FACES A MAJOR TEST!
Despite growing investor concerns and pressure to reconsider its IPO timing, Anthropic is pushing ahead with its highly anticipated stock market debut.
The company behind Claude AI has moved forward with an updated filing, proposing to offer 825 million shares at an estimated $70–$78 per share.
🔥 Why Is the IPO Raising Concerns?
Anthropic's potential valuation could reach approximately $1.4 trillion.
Earlier expectations reportedly placed its valuation as high as $2 trillion.
Some investors believe the valuation is too aggressive.
Market volatility and concerns about AI spending are creating additional pressure.
The IPO could raise up to $64.35 billion through the public offering.
Why Does This Matter?
Anthropic's IPO could become a major test of investor confidence in the AI industry.
If demand is strong, it could restore confidence in high-value AI companies. But weak demand could signal that investors are becoming more cautious about expensive AI valuations.
One question remains: Is $1.4 trillion a fair price for Anthropic, or is the AI hype getting ahead of reality?
#Anthropic #Aİ #IPO
🚨 ANTHROPIC REFUSES TO SLOW DOWN: $1.4 TRILLION IPO FACES A MAJOR TEST!
Despite growing investor concerns and pressure to reconsider its IPO timing, Anthropic is pushing ahead with its highly anticipated stock market debut.
The company behind Claude AI has moved forward with an updated filing, proposing to offer 825 million shares at an estimated $70–$78 per share.
🔥 Why Is the IPO Raising Concerns?
Anthropic's potential valuation could reach approximately $1.4 trillion.
Earlier expectations reportedly placed its valuation as high as $2 trillion.
Some investors believe the valuation is too aggressive.
Market volatility and concerns about AI spending are creating additional pressure.
The IPO could raise up to $64.35 billion through the public offering.
Why Does This Matter?
Anthropic's IPO could become a major test of investor confidence in the AI industry.
If demand is strong, it could restore confidence in high-value AI companies. But weak demand could signal that investors are becoming more cautious about expensive AI valuations.
One question remains: Is $1.4 trillion a fair price for Anthropic, or is the AI hype getting ahead of reality?
#Anthropic #Aİ #IPO
265
·
--
🚨 BREAKING AI NEWS: ANTHROPIC IPO UNDER PRESSURE!
Anthropic's massive IPO is attracting attention as investors question its proposed $AAPLB 1.4 trillion valuation.
Market volatility, rising AI infrastructure costs and competition are creating uncertainty around the company's public listing.
Despite these concerns, Anthropic is moving forward with its IPO plans, making this one of the biggest upcoming events in the AI industry.
📊 Investors are watching closely to see whether the AI boom can justify these enormous valuati#IPO #HuangRisksOusterOverReportedAffairWithSubordinate #HuangRisksOusterOverReportedAffairWithSubordinate ClaudeAI #StockMarket #TechNews #AIInvestment
🚨 BREAKING AI NEWS: ANTHROPIC IPO UNDER PRESSURE!
Anthropic's massive IPO is attracting attention as investors question its proposed $AAPLB 1.4 trillion valuation.
Market volatility, rising AI infrastructure costs and competition are creating uncertainty around the company's public listing.
Despite these concerns, Anthropic is moving forward with its IPO plans, making this one of the biggest upcoming events in the AI industry.
📊 Investors are watching closely to see whether the AI boom can justify these enormous valuati#IPO #HuangRisksOusterOverReportedAffairWithSubordinate #HuangRisksOusterOverReportedAffairWithSubordinate ClaudeAI #StockMarket #TechNews #AIInvestment
Anthropic's massive IPO is attracting attention as investors question its proposed $AAPLB 1.4 trillion valuation.
Market volatility, rising AI infrastructure costs and competition are creating uncertainty around the company's public listing.
Despite these concerns, Anthropic is moving forward with its IPO plans, making this one of the biggest upcoming events in the AI industry.
📊 Investors are watching closely to see whether the AI boom can justify these enormous valuati#IPO #HuangRisksOusterOverReportedAffairWithSubordinate #HuangRisksOusterOverReportedAffairWithSubordinate ClaudeAI #StockMarket #TechNews #AIInvestment
129

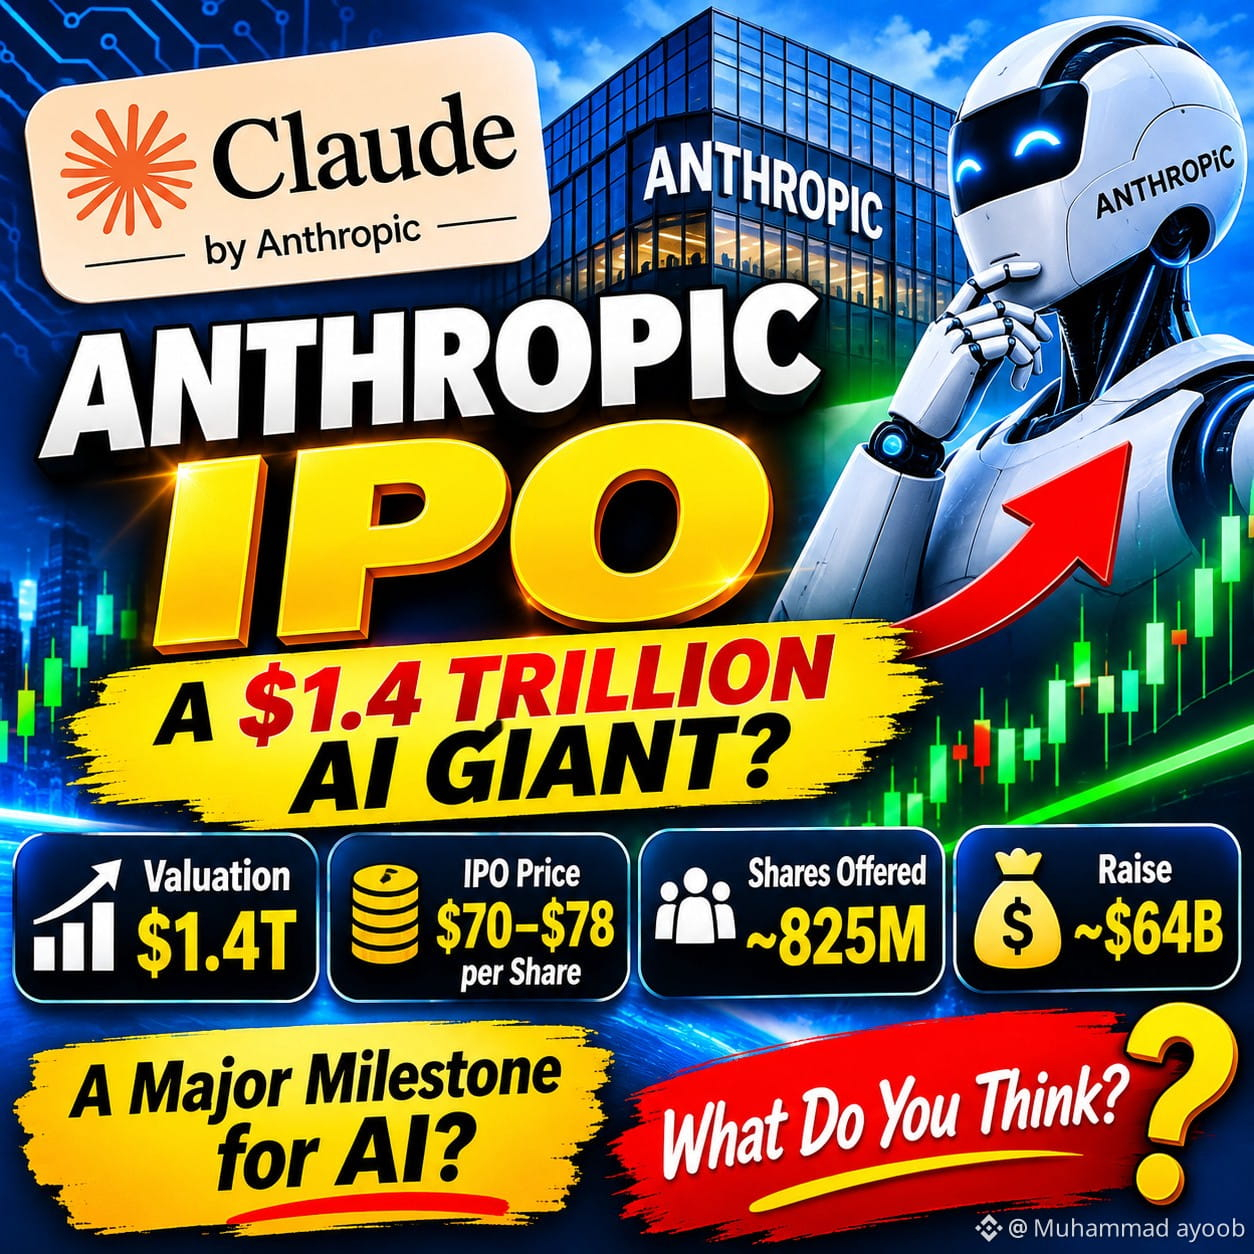
🚀 ANTHROPIC IPO: A $1.4 TRILLION AI GIANT?
The AI industry is preparing for one of its biggest financial events!
Anthropic, the company behind Claude AI, is attracting massive attention with its highly anticipated IPO.
📊 Key Market Highlights:
🔹 Anthropic is targeting a valuation of approximately $1.4 trillion.
🔹 Its proposed IPO price range is $70–$78 per share.
🔹 The company plans to offer around 825 million shares.
🔹 The IPO could raise more than $64 billion.
🔹 Major technology companies and institutional investors are closely watching the offering.
🔥 Why Does This Matter?
Anthropic's IPO could become a major test of investor confidence in the AI industry.
However, massive valuations also bring serious questions about profitability, competition, and long-term growth.
🎯 My Market Perspective:
The real question is not just how much Anthropic is worth today, but whether its future growth can justify such a huge valuation.
💬 What do you think?
Will Anthropic become one of the biggest technology IPOs in history?
Share your thoughts below!
#Anthropic #IPO #ArtificialIntelligence
#CryptoNews #Binance
🚀 ANTHROPIC IPO: A $1.4 TRILLION AI GIANT?
The AI industry is preparing for one of its biggest financial events!
Anthropic, the company behind Claude AI, is attracting massive attention with its highly anticipated IPO.
📊 Key Market Highlights:
🔹 Anthropic is targeting a valuation of approximately $1.4 trillion.
🔹 Its proposed IPO price range is $70–$78 per share.
🔹 The company plans to offer around 825 million shares.
🔹 The IPO could raise more than $64 billion.
🔹 Major technology companies and institutional investors are closely watching the offering.
🔥 Why Does This Matter?
Anthropic's IPO could become a major test of investor confidence in the AI industry.
However, massive valuations also bring serious questions about profitability, competition, and long-term growth.
🎯 My Market Perspective:
The real question is not just how much Anthropic is worth today, but whether its future growth can justify such a huge valuation.
💬 What do you think?
Will Anthropic become one of the biggest technology IPOs in history?
Share your thoughts below!
#Anthropic #IPO #ArtificialIntelligence
#CryptoNews #Binance
The AI industry is preparing for one of its biggest financial events!
Anthropic, the company behind Claude AI, is attracting massive attention with its highly anticipated IPO.
📊 Key Market Highlights:
🔹 Anthropic is targeting a valuation of approximately $1.4 trillion.
🔹 Its proposed IPO price range is $70–$78 per share.
🔹 The company plans to offer around 825 million shares.
🔹 The IPO could raise more than $64 billion.
🔹 Major technology companies and institutional investors are closely watching the offering.
🔥 Why Does This Matter?
Anthropic's IPO could become a major test of investor confidence in the AI industry.
However, massive valuations also bring serious questions about profitability, competition, and long-term growth.
🎯 My Market Perspective:
The real question is not just how much Anthropic is worth today, but whether its future growth can justify such a huge valuation.
💬 What do you think?
Will Anthropic become one of the biggest technology IPOs in history?
Share your thoughts below!
#Anthropic #IPO #ArtificialIntelligence
#CryptoNews #Binance
79
·
--
Рост
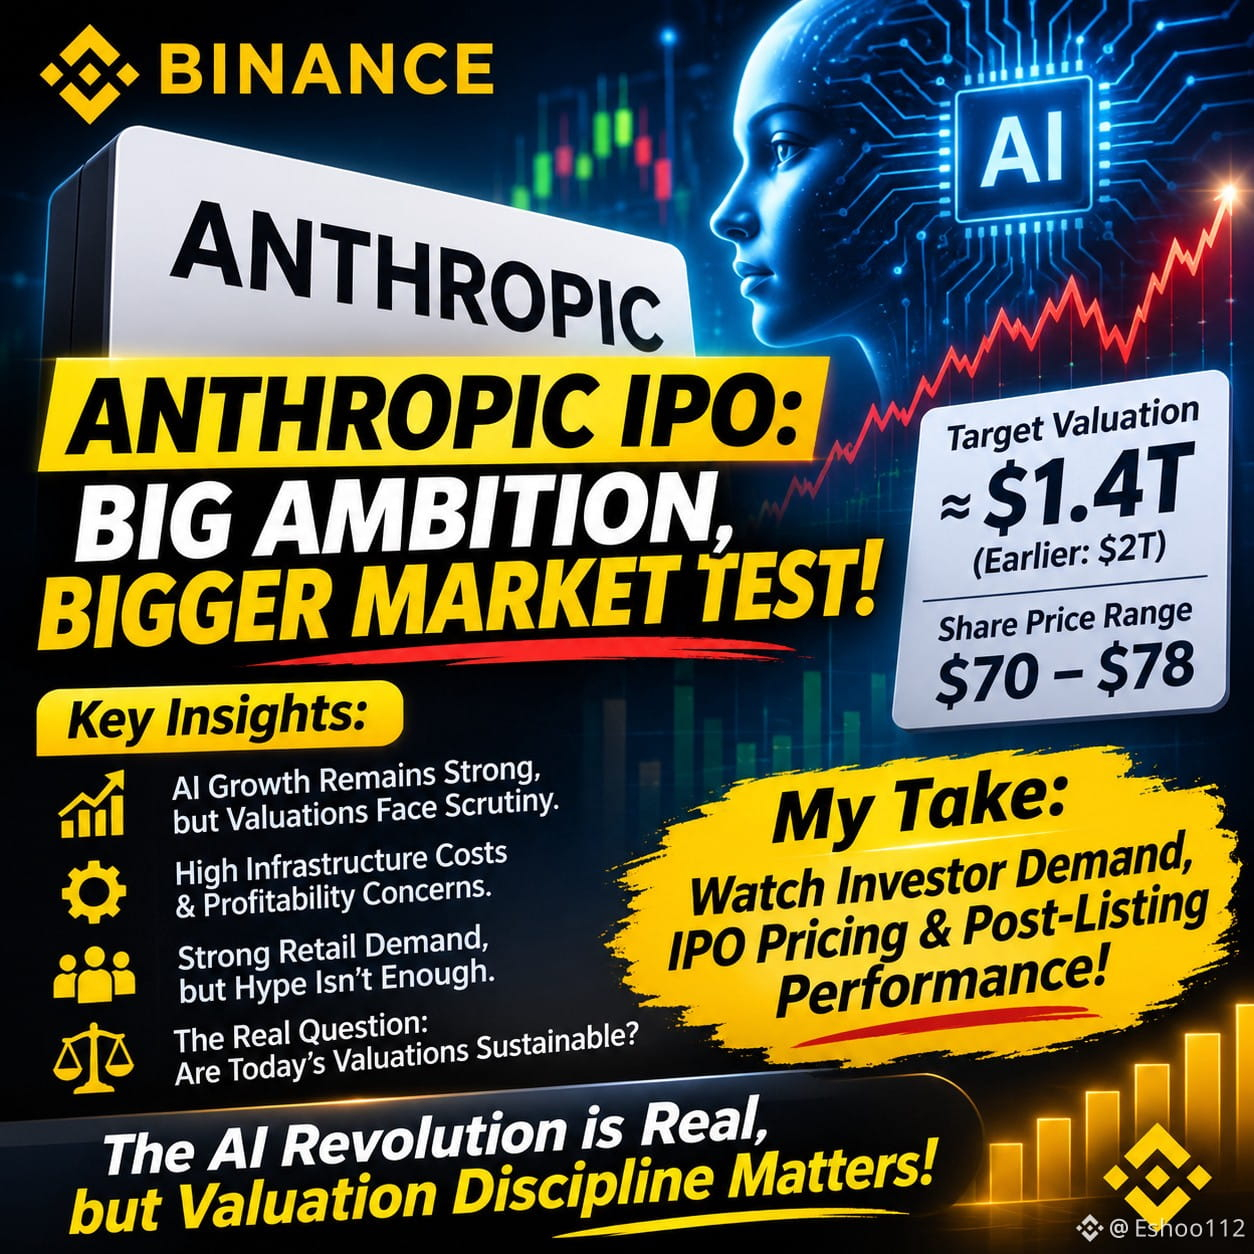
🚨 ANTHROPIC IPO: BIG AMBITION, BIGGER MARKET TEST!
Anthropic's IPO is becoming a major test of confidence in the AI industry.
After earlier expectations of a $2 trillion valuation, the company is now targeting approximately $1.4 trillion, with shares priced at $70–$78.
📊 My Market Analysis:
🔹 AI growth remains powerful, but investors are becoming more valuation-conscious.
🔹 Massive infrastructure costs and profitability concerns cannot be ignored.
🔹 Strong retail demand could support the IPO, but hype alone cannot guarantee long-term performance.
🔹 The real question isn't whether AI will dominate the future — it's whether today's valuations are sustainable.
My Take: This could be a defining moment for AI investments. Watch investor demand, IPO pricing, and post-listing performance before making any decisions.
The AI revolution is real, but valuation discipline matters!
#AI #IPO #CryptoMarket #BinanceSquare #HuangRisksOusterOverReportedAffairWithSubordinate
🚨 ANTHROPIC IPO: BIG AMBITION, BIGGER MARKET TEST!
Anthropic's IPO is becoming a major test of confidence in the AI industry.
After earlier expectations of a $2 trillion valuation, the company is now targeting approximately $1.4 trillion, with shares priced at $70–$78.
📊 My Market Analysis:
🔹 AI growth remains powerful, but investors are becoming more valuation-conscious.
🔹 Massive infrastructure costs and profitability concerns cannot be ignored.
🔹 Strong retail demand could support the IPO, but hype alone cannot guarantee long-term performance.
🔹 The real question isn't whether AI will dominate the future — it's whether today's valuations are sustainable.
My Take: This could be a defining moment for AI investments. Watch investor demand, IPO pricing, and post-listing performance before making any decisions.
The AI revolution is real, but valuation discipline matters!
#AI #IPO #CryptoMarket #BinanceSquare #HuangRisksOusterOverReportedAffairWithSubordinate
Anthropic's IPO is becoming a major test of confidence in the AI industry.
After earlier expectations of a $2 trillion valuation, the company is now targeting approximately $1.4 trillion, with shares priced at $70–$78.
📊 My Market Analysis:
🔹 AI growth remains powerful, but investors are becoming more valuation-conscious.
🔹 Massive infrastructure costs and profitability concerns cannot be ignored.
🔹 Strong retail demand could support the IPO, but hype alone cannot guarantee long-term performance.
🔹 The real question isn't whether AI will dominate the future — it's whether today's valuations are sustainable.
My Take: This could be a defining moment for AI investments. Watch investor demand, IPO pricing, and post-listing performance before making any decisions.
The AI revolution is real, but valuation discipline matters!
#AI #IPO #CryptoMarket #BinanceSquare #HuangRisksOusterOverReportedAffairWithSubordinate
User-fe52f6ef:
ai
4
7
89
Статья
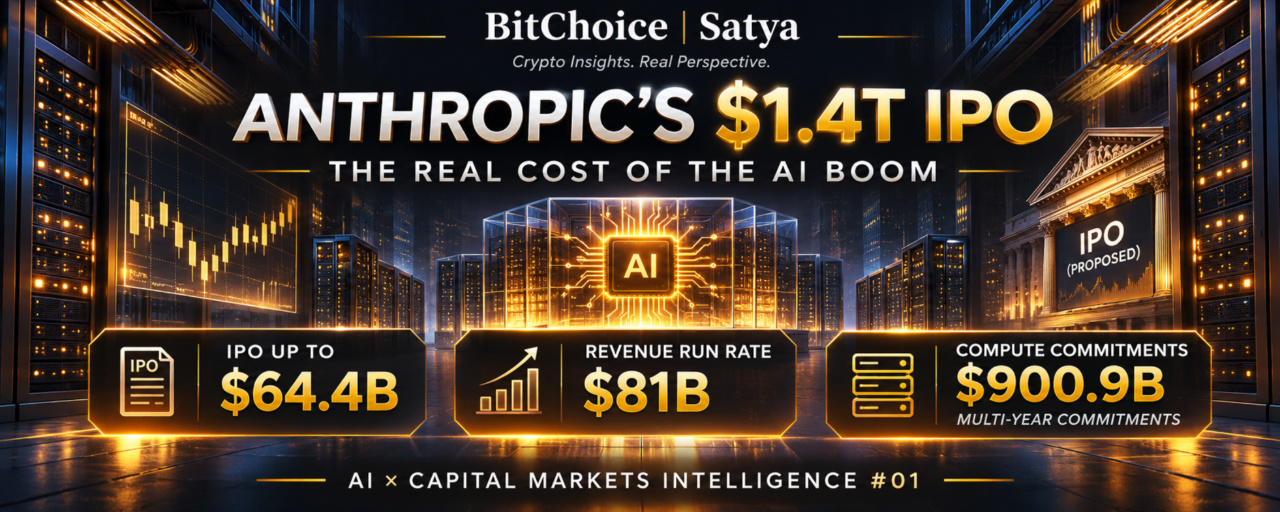
ANTHROPIC'S $1.4 TRILLION IPO: THE REAL COST OF THE AI BOOMAI × Capital Markets Intelligence #01 | November 12, 2026
The AI industry is approaching one of its most important financial tests.
Anthropic, the company behind Claude, has launched the roadshow for a proposed initial public offering that could value the business at approximately $1.4 trillion on a fully diluted basis.
But behind the headline valuation lies a much bigger question:
Can AI companies generate sustainable returns on the enormous computing infrastructure required to power their growth?
1. THE IPO: A HISTORIC CAPITAL RAISE
Anthropic is offering 825 million Class A shares at an indicative price of $70–$78 per share.
At the upper end of that range, the offering could raise approximately $64.4 billion, including shares sold by existing stockholders.
Separately, major technology investors have agreed to purchase $26 billion of non-voting shares in a private placement connected to the IPO.
The proposed Nasdaq ticker is ANT.
However, the pricing remains preliminary. The registration statement has not yet become effective, and the final IPO valuation has not been established.
One distinction matters: the widely reported $1.4 trillion figure uses a fully diluted share count. Valuation calculations based only on currently outstanding shares produce a lower figure.
2. REVENUE GROWTH IS REAL — BUT SO ARE THE COSTS
Anthropic reported $17.0 billion in revenue for the third quarter of 2026.
By October 31, its annualized revenue run rate had reached approximately $81 billion.
That is an extraordinary commercial expansion.
However, annualized run rate is not the same as realized annual revenue. It estimates a yearly level based on a recent revenue pace.
Profitability presents a more complicated picture.
Third-quarter GAAP operating loss reached $567 million, compared with approximately $974 million in operating income during the previous quarter.
The company reported an adjusted operating margin of 15%, down from 19% in the second quarter.
The divergence illustrates how profitability can fluctuate when additional computing capacity becomes available and infrastructure expenses rise.
3. THE $900.9 BILLION COMPUTE QUESTION
The most striking figure in Anthropic's IPO filings may not be its valuation.
It is the approximately $900.9 billion in aggregate purchase and lease commitments, substantially related to computing and infrastructure.
These obligations extend over multiple years, with approximately $451.6 billion expected to be incurred before the end of 2030.
This does not mean Anthropic has already spent $900.9 billion or borrowed that amount.
It means the company has made substantial contractual commitments to secure future capacity.
The strategic logic is understandable.
Frontier AI requires enormous computing resources for training, inference, research and enterprise deployment.
But committing to capacity introduces significant financial exposure if demand, utilization or pricing develops differently from expectations.
4. WHY THE GPU ECONOMICS MATTER
AI infrastructure creates a complex relationship between software companies, chipmakers, cloud providers and data-center operators.
Anthropic needs computing capacity.
NVIDIA, AMD and other hardware providers benefit from demand for accelerators.
Cloud and infrastructure partners monetize computing resources.
But these participants do not necessarily earn identical returns.
For Anthropic, the critical variables include:
Revenue generated per dollar of compute.Model efficiency and inference costs.GPU utilization and infrastructure availability.Pricing competition across AI providers.Enterprise customer retention and recurring demand.Operating cash flow relative to investment requirements.
An increase in AI usage does not automatically guarantee rising profit margins.
If the cost of serving customers grows faster than the revenue those customers generate, strong demand can coexist with financial pressure.
5. A NEW TEST FOR WALL STREET
At approximately $1.4 trillion in fully diluted equity value and an $81 billion annualized revenue run rate, Anthropic would trade at roughly 17 times that run rate.
This is only an indicative valuation comparison, not a conventional trailing annual revenue multiple.
The market is effectively being asked to price years of future commercial expansion today.
For investors, the question is not whether AI will become important.
It already is.
The question is how much future profitability is already reflected in the proposed share price.
High growth can justify premium valuations, but the margin for disappointment becomes narrower when expectations are exceptionally large.
6. THE BROADER MARKET EFFECT
Anthropic's IPO could become a major event for the entire AI investment ecosystem.
Its reception may influence market sentiment toward AI software businesses, semiconductor manufacturers and data-center infrastructure providers.
The offering may also attract substantial institutional and index-related demand.
However, IPO demand, early trading performance and sustainable long-term valuation are different things.
A limited public float can amplify initial price movements. Future share sales, changes in investor positioning and operating results can alter that dynamic.
Another consideration is governance: the proposed share structure gives public Class A investors more limited influence than a conventional single-class share structure might provide.
BITCHOICE | SATYA PERSPECTIVE
Anthropic's proposed IPO is not simply a vote on the future of artificial intelligence.
It is a test of the economics behind the AI infrastructure boom.
The bullish case rests on enterprise adoption, rapid revenue growth, improving model efficiency and the possibility of substantial operating leverage.
The bearish case centers on infrastructure commitments, competition, capital intensity, governance and the risk that future profitability falls short of current expectations.
Both perspectives deserve serious consideration.
The most important question is not whether Anthropic can command a trillion-dollar valuation.
It is whether the company can eventually generate cash flows that justify that valuation.
AI demand may be growing rapidly.
But demand, revenue, earnings and free cash flow are four different things.
The next phase of the AI boom will be judged increasingly by the relationship between them.
BitChoice | Satya — Crypto Insights. Real Perspective.
#IPO $NVDAB $AMZNB $AAPL
{future}(AAPLUSDT)
{spot}(NVDABUSDT)
ANTHROPIC'S $1.4 TRILLION IPO: THE REAL COST OF THE AI BOOM
AI × Capital Markets Intelligence #01 | November 12, 2026
The AI industry is approaching one of its most important financial tests.
Anthropic, the company behind Claude, has launched the roadshow for a proposed initial public offering that could value the business at approximately $1.4 trillion on a fully diluted basis.
But behind the headline valuation lies a much bigger question:
Can AI companies generate sustainable returns on the enormous computing infrastructure required to power their growth?
1. THE IPO: A HISTORIC CAPITAL RAISE
Anthropic is offering 825 million Class A shares at an indicative price of $70–$78 per share.
At the upper end of that range, the offering could raise approximately $64.4 billion, including shares sold by existing stockholders.
Separately, major technology investors have agreed to purchase $26 billion of non-voting shares in a private placement connected to the IPO.
The proposed Nasdaq ticker is ANT.
However, the pricing remains preliminary. The registration statement has not yet become effective, and the final IPO valuation has not been established.
One distinction matters: the widely reported $1.4 trillion figure uses a fully diluted share count. Valuation calculations based only on currently outstanding shares produce a lower figure.
2. REVENUE GROWTH IS REAL — BUT SO ARE THE COSTS
Anthropic reported $17.0 billion in revenue for the third quarter of 2026.
By October 31, its annualized revenue run rate had reached approximately $81 billion.
That is an extraordinary commercial expansion.
However, annualized run rate is not the same as realized annual revenue. It estimates a yearly level based on a recent revenue pace.
Profitability presents a more complicated picture.
Third-quarter GAAP operating loss reached $567 million, compared with approximately $974 million in operating income during the previous quarter.
The company reported an adjusted operating margin of 15%, down from 19% in the second quarter.
The divergence illustrates how profitability can fluctuate when additional computing capacity becomes available and infrastructure expenses rise.
3. THE $900.9 BILLION COMPUTE QUESTION
The most striking figure in Anthropic's IPO filings may not be its valuation.
It is the approximately $900.9 billion in aggregate purchase and lease commitments, substantially related to computing and infrastructure.
These obligations extend over multiple years, with approximately $451.6 billion expected to be incurred before the end of 2030.
This does not mean Anthropic has already spent $900.9 billion or borrowed that amount.
It means the company has made substantial contractual commitments to secure future capacity.
The strategic logic is understandable.
Frontier AI requires enormous computing resources for training, inference, research and enterprise deployment.
But committing to capacity introduces significant financial exposure if demand, utilization or pricing develops differently from expectations.
4. WHY THE GPU ECONOMICS MATTER
AI infrastructure creates a complex relationship between software companies, chipmakers, cloud providers and data-center operators.
Anthropic needs computing capacity.
NVIDIA, AMD and other hardware providers benefit from demand for accelerators.
Cloud and infrastructure partners monetize computing resources.
But these participants do not necessarily earn identical returns.
For Anthropic, the critical variables include:
Revenue generated per dollar of compute.Model efficiency and inference costs.GPU utilization and infrastructure availability.Pricing competition across AI providers.Enterprise customer retention and recurring demand.Operating cash flow relative to investment requirements.
An increase in AI usage does not automatically guarantee rising profit margins.
If the cost of serving customers grows faster than the revenue those customers generate, strong demand can coexist with financial pressure.
5. A NEW TEST FOR WALL STREET
At approximately $1.4 trillion in fully diluted equity value and an $81 billion annualized revenue run rate, Anthropic would trade at roughly 17 times that run rate.
This is only an indicative valuation comparison, not a conventional trailing annual revenue multiple.
The market is effectively being asked to price years of future commercial expansion today.
For investors, the question is not whether AI will become important.
It already is.
The question is how much future profitability is already reflected in the proposed share price.
High growth can justify premium valuations, but the margin for disappointment becomes narrower when expectations are exceptionally large.
6. THE BROADER MARKET EFFECT
Anthropic's IPO could become a major event for the entire AI investment ecosystem.
Its reception may influence market sentiment toward AI software businesses, semiconductor manufacturers and data-center infrastructure providers.
The offering may also attract substantial institutional and index-related demand.
However, IPO demand, early trading performance and sustainable long-term valuation are different things.
A limited public float can amplify initial price movements. Future share sales, changes in investor positioning and operating results can alter that dynamic.
Another consideration is governance: the proposed share structure gives public Class A investors more limited influence than a conventional single-class share structure might provide.
BITCHOICE | SATYA PERSPECTIVE
Anthropic's proposed IPO is not simply a vote on the future of artificial intelligence.
It is a test of the economics behind the AI infrastructure boom.
The bullish case rests on enterprise adoption, rapid revenue growth, improving model efficiency and the possibility of substantial operating leverage.
The bearish case centers on infrastructure commitments, competition, capital intensity, governance and the risk that future profitability falls short of current expectations.
Both perspectives deserve serious consideration.
The most important question is not whether Anthropic can command a trillion-dollar valuation.
It is whether the company can eventually generate cash flows that justify that valuation.
AI demand may be growing rapidly.
But demand, revenue, earnings and free cash flow are four different things.
The next phase of the AI boom will be judged increasingly by the relationship between them.
BitChoice | Satya — Crypto Insights. Real Perspective.
#IPO $NVDAB $AMZNB $AAPL
The AI industry is approaching one of its most important financial tests.
Anthropic, the company behind Claude, has launched the roadshow for a proposed initial public offering that could value the business at approximately $1.4 trillion on a fully diluted basis.
But behind the headline valuation lies a much bigger question:
Can AI companies generate sustainable returns on the enormous computing infrastructure required to power their growth?
1. THE IPO: A HISTORIC CAPITAL RAISE
Anthropic is offering 825 million Class A shares at an indicative price of $70–$78 per share.
At the upper end of that range, the offering could raise approximately $64.4 billion, including shares sold by existing stockholders.
Separately, major technology investors have agreed to purchase $26 billion of non-voting shares in a private placement connected to the IPO.
The proposed Nasdaq ticker is ANT.
However, the pricing remains preliminary. The registration statement has not yet become effective, and the final IPO valuation has not been established.
One distinction matters: the widely reported $1.4 trillion figure uses a fully diluted share count. Valuation calculations based only on currently outstanding shares produce a lower figure.
2. REVENUE GROWTH IS REAL — BUT SO ARE THE COSTS
Anthropic reported $17.0 billion in revenue for the third quarter of 2026.
By October 31, its annualized revenue run rate had reached approximately $81 billion.
That is an extraordinary commercial expansion.
However, annualized run rate is not the same as realized annual revenue. It estimates a yearly level based on a recent revenue pace.
Profitability presents a more complicated picture.
Third-quarter GAAP operating loss reached $567 million, compared with approximately $974 million in operating income during the previous quarter.
The company reported an adjusted operating margin of 15%, down from 19% in the second quarter.
The divergence illustrates how profitability can fluctuate when additional computing capacity becomes available and infrastructure expenses rise.
3. THE $900.9 BILLION COMPUTE QUESTION
The most striking figure in Anthropic's IPO filings may not be its valuation.
It is the approximately $900.9 billion in aggregate purchase and lease commitments, substantially related to computing and infrastructure.
These obligations extend over multiple years, with approximately $451.6 billion expected to be incurred before the end of 2030.
This does not mean Anthropic has already spent $900.9 billion or borrowed that amount.
It means the company has made substantial contractual commitments to secure future capacity.
The strategic logic is understandable.
Frontier AI requires enormous computing resources for training, inference, research and enterprise deployment.
But committing to capacity introduces significant financial exposure if demand, utilization or pricing develops differently from expectations.
4. WHY THE GPU ECONOMICS MATTER
AI infrastructure creates a complex relationship between software companies, chipmakers, cloud providers and data-center operators.
Anthropic needs computing capacity.
NVIDIA, AMD and other hardware providers benefit from demand for accelerators.
Cloud and infrastructure partners monetize computing resources.
But these participants do not necessarily earn identical returns.
For Anthropic, the critical variables include:
Revenue generated per dollar of compute.Model efficiency and inference costs.GPU utilization and infrastructure availability.Pricing competition across AI providers.Enterprise customer retention and recurring demand.Operating cash flow relative to investment requirements.
An increase in AI usage does not automatically guarantee rising profit margins.
If the cost of serving customers grows faster than the revenue those customers generate, strong demand can coexist with financial pressure.
5. A NEW TEST FOR WALL STREET
At approximately $1.4 trillion in fully diluted equity value and an $81 billion annualized revenue run rate, Anthropic would trade at roughly 17 times that run rate.
This is only an indicative valuation comparison, not a conventional trailing annual revenue multiple.
The market is effectively being asked to price years of future commercial expansion today.
For investors, the question is not whether AI will become important.
It already is.
The question is how much future profitability is already reflected in the proposed share price.
High growth can justify premium valuations, but the margin for disappointment becomes narrower when expectations are exceptionally large.
6. THE BROADER MARKET EFFECT
Anthropic's IPO could become a major event for the entire AI investment ecosystem.
Its reception may influence market sentiment toward AI software businesses, semiconductor manufacturers and data-center infrastructure providers.
The offering may also attract substantial institutional and index-related demand.
However, IPO demand, early trading performance and sustainable long-term valuation are different things.
A limited public float can amplify initial price movements. Future share sales, changes in investor positioning and operating results can alter that dynamic.
Another consideration is governance: the proposed share structure gives public Class A investors more limited influence than a conventional single-class share structure might provide.
BITCHOICE | SATYA PERSPECTIVE
Anthropic's proposed IPO is not simply a vote on the future of artificial intelligence.
It is a test of the economics behind the AI infrastructure boom.
The bullish case rests on enterprise adoption, rapid revenue growth, improving model efficiency and the possibility of substantial operating leverage.
The bearish case centers on infrastructure commitments, competition, capital intensity, governance and the risk that future profitability falls short of current expectations.
Both perspectives deserve serious consideration.
The most important question is not whether Anthropic can command a trillion-dollar valuation.
It is whether the company can eventually generate cash flows that justify that valuation.
AI demand may be growing rapidly.
But demand, revenue, earnings and free cash flow are four different things.
The next phase of the AI boom will be judged increasingly by the relationship between them.
BitChoice | Satya — Crypto Insights. Real Perspective.
#IPO $NVDAB $AMZNB $AAPL
237
·
--
嘿,朋友们!听说 OpenAI 的 IPO 传闻已经在科技圈掀起了惊涛骇浪,估值直接上天!🚀 市场上的情绪啊,就像是过山车一样,FOMO(害怕错过)和贪婪情绪弥漫开来。 想象一下,一个估值高达千亿美金的 AI 公司,那得多疯狂啊!大家都生怕错过了这个投资的大风口,毕竟这可是改变世界的巨头公司啊!🌟 但说实话,这种天量估值也让人不禁有些 FUD(恐惧、怀疑、担忧),这背后是真是假,谁又能说得清呢?但不管怎样,市场热度已经起来了,很多科技公司、风险投资都坐不住了,都在密切关注这个动向。 这不禁让我想起了比特币当初上市的那段时间,市场同样充满了炒作和疯狂,最后呢?大家都赚了个盆满钵满!🤑 所以说,各位朋友,你们觉得 OpenAI 的 IPO 会是下一个比特币吗?你们准备好了没有?🤔 在评论区告诉我你们的看法吧!#OpenAI #IPO #估值 #科技圈
$BTC $ETH $SOL
嘿,朋友们!听说 OpenAI 的 IPO 传闻已经在科技圈掀起了惊涛骇浪,估值直接上天!🚀 市场上的情绪啊,就像是过山车一样,FOMO(害怕错过)和贪婪情绪弥漫开来。 想象一下,一个估值高达千亿美金的 AI 公司,那得多疯狂啊!大家都生怕错过了这个投资的大风口,毕竟这可是改变世界的巨头公司啊!🌟 但说实话,这种天量估值也让人不禁有些 FUD(恐惧、怀疑、担忧),这背后是真是假,谁又能说得清呢?但不管怎样,市场热度已经起来了,很多科技公司、风险投资都坐不住了,都在密切关注这个动向。 这不禁让我想起了比特币当初上市的那段时间,市场同样充满了炒作和疯狂,最后呢?大家都赚了个盆满钵满!🤑 所以说,各位朋友,你们觉得 OpenAI 的 IPO 会是下一个比特币吗?你们准备好了没有?🤔 在评论区告诉我你们的看法吧!#OpenAI #IPO #估值 #科技圈
$BTC $ETH $SOL
$BTC $ETH $SOL
1
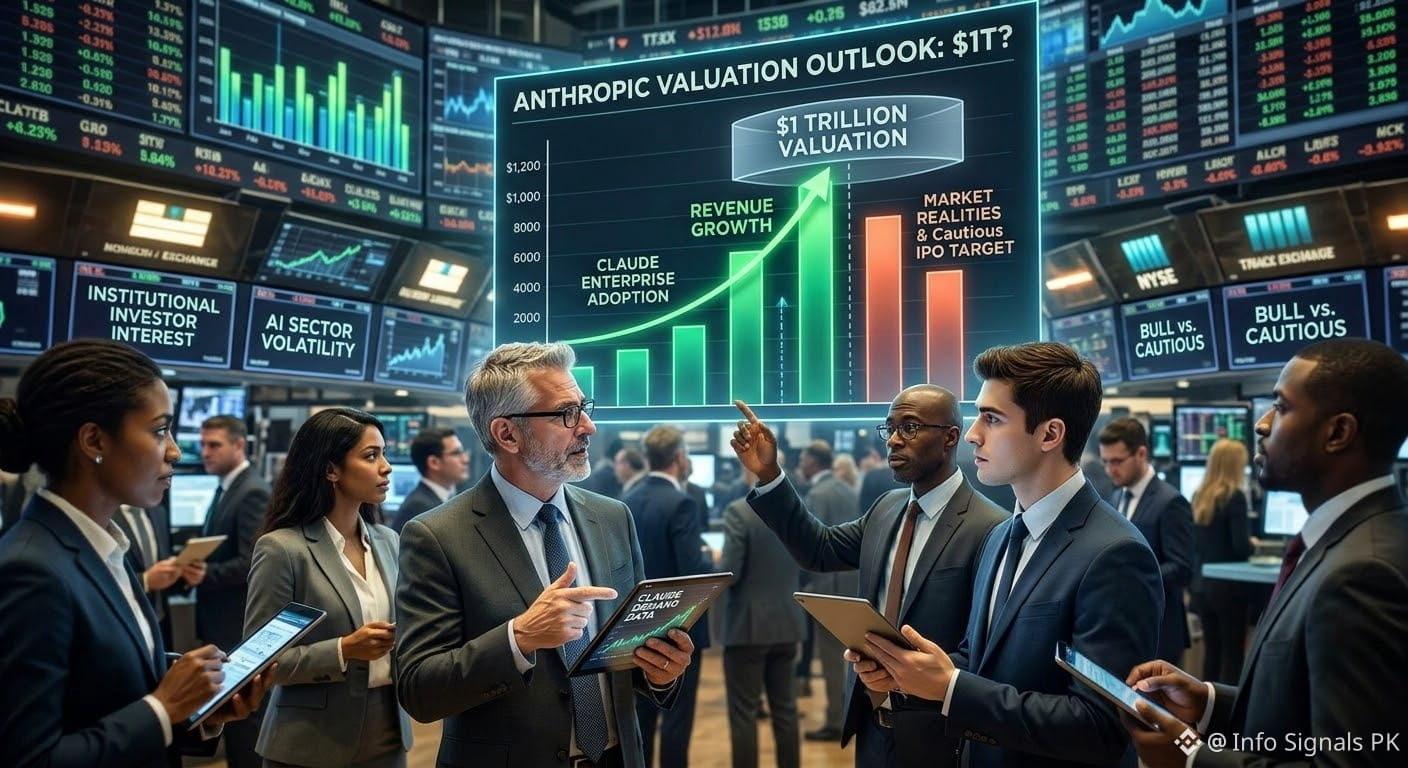
Can Anthropic really hold a $1T+ valuation? 🤔
I keep coming back to this one. If the reports of a lower IPO target are right, I think scaling back expectations is the smart move in this market. Pricing a little conservatively usually leaves room for a stronger first day.
What keeps me optimistic is the demand. Businesses are leaning hard on Claude, revenue is growing fast, and big institutional investors seem very interested.
Do I think it stays above $1T? I lean yes. But I'm curious what you think. Bullish or cautious?
#AnthropicIPO #AI #IPO
Can Anthropic really hold a $1T+ valuation? 🤔
I keep coming back to this one. If the reports of a lower IPO target are right, I think scaling back expectations is the smart move in this market. Pricing a little conservatively usually leaves room for a stronger first day.
What keeps me optimistic is the demand. Businesses are leaning hard on Claude, revenue is growing fast, and big institutional investors seem very interested.
Do I think it stays above $1T? I lean yes. But I'm curious what you think. Bullish or cautious?
#AnthropicIPO #AI #IPO
I keep coming back to this one. If the reports of a lower IPO target are right, I think scaling back expectations is the smart move in this market. Pricing a little conservatively usually leaves room for a stronger first day.
What keeps me optimistic is the demand. Businesses are leaning hard on Claude, revenue is growing fast, and big institutional investors seem very interested.
Do I think it stays above $1T? I lean yes. But I'm curious what you think. Bullish or cautious?
#AnthropicIPO #AI #IPO
171
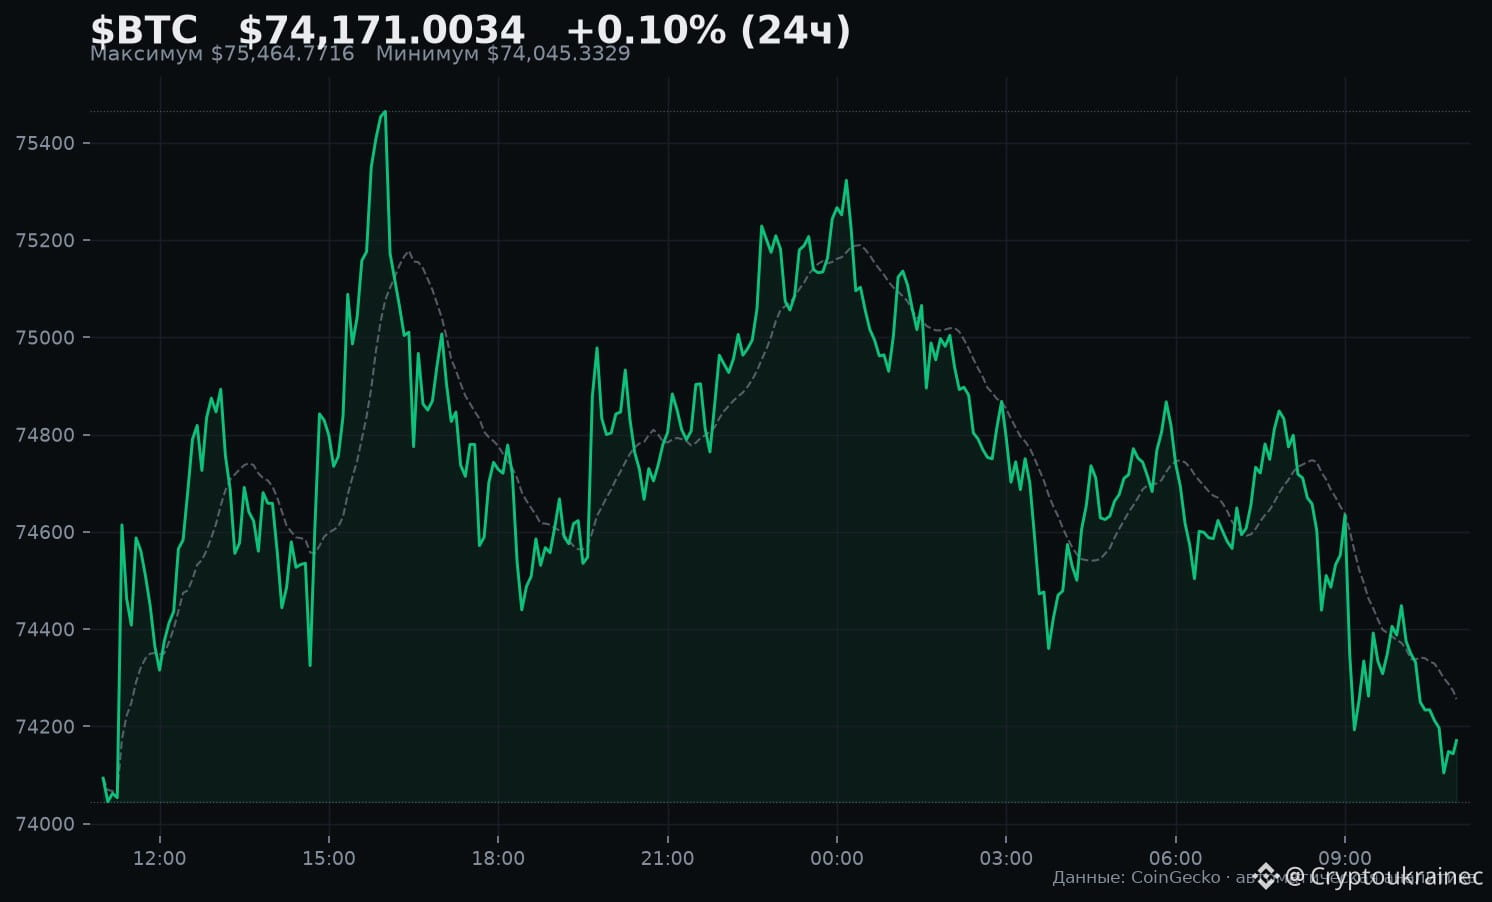
Anthropic готовится к IPO — и это меняет расклад сил на рынке ИИ. Компания, получившая миллиарды от Amazon и Google, выходит на публичный рынок в момент, когда AI-сектор под максимальным давлением. Как мы отмечали ранее, Anthropic наращивает инфраструктуру агрессивно — IPO логично продолжает эту стратегию. AI-токены могут отреагировать первыми.
Ждёте ли вы роста в AI-секторе после этого IPO?
$BTC $FET $TAO #AI #IPO
Anthropic готовится к IPO — и это меняет расклад сил на рынке ИИ. Компания, получившая миллиарды от Amazon и Google, выходит на публичный рынок в момент, когда AI-сектор под максимальным давлением. Как мы отмечали ранее, Anthropic наращивает инфраструктуру агрессивно — IPO логично продолжает эту стратегию. AI-токены могут отреагировать первыми.
Ждёте ли вы роста в AI-секторе после этого IPO?
$BTC $FET $TAO #AI #IPO
Ждёте ли вы роста в AI-секторе после этого IPO?
$BTC $FET $TAO #AI #IPO
103
·
--
🚨 ANTHROPIC ГОТУЄ ГУЧНЕ IPO! АКЦІЇ МОЖУТЬ З'ЯВИТИСЯ НА NASDAQ ВЖЕ 19 ЛИСТОПАДА!
Компанія, яка створила штучний інтелект Claude, готується до одного з найбільш обговорюваних біржових дебютів року. 🤖
📍 Де планується лістинг?
На американській біржі NASDAQ.
🔠 Очікуваний біржовий тикер: ANT.
📅 Орієнтовна дата початку торгів: 19 листопада 2026 року.
💵 Попередній ціновий діапазон IPO: $70–78 за акцію.
Але найцікавіше — оцінка всієї компанії може сягнути $1,4 трлн!
Що це означає для інвесторів?
Після початку біржових торгів акції потенційно можна буде придбати через брокерів, які надають доступ до NASDAQ.
Взяти участь безпосередньо в IPO складніше: розподіл акцій до початку торгів залежить від брокера та доступу до розміщення.
⚠️ Усі умови поки попередні й можуть змінитися.
👀 А ви хотіли б купити акції Anthropic у перший день торгів?
#Anthropic #IPO #NASDAQ
🚨 ANTHROPIC ГОТУЄ ГУЧНЕ IPO! АКЦІЇ МОЖУТЬ З'ЯВИТИСЯ НА NASDAQ ВЖЕ 19 ЛИСТОПАДА!
Компанія, яка створила штучний інтелект Claude, готується до одного з найбільш обговорюваних біржових дебютів року. 🤖
📍 Де планується лістинг?
На американській біржі NASDAQ.
🔠 Очікуваний біржовий тикер: ANT.
📅 Орієнтовна дата початку торгів: 19 листопада 2026 року.
💵 Попередній ціновий діапазон IPO: $70–78 за акцію.
Але найцікавіше — оцінка всієї компанії може сягнути $1,4 трлн!
Що це означає для інвесторів?
Після початку біржових торгів акції потенційно можна буде придбати через брокерів, які надають доступ до NASDAQ.
Взяти участь безпосередньо в IPO складніше: розподіл акцій до початку торгів залежить від брокера та доступу до розміщення.
⚠️ Усі умови поки попередні й можуть змінитися.
👀 А ви хотіли б купити акції Anthropic у перший день торгів?
#Anthropic #IPO #NASDAQ
Компанія, яка створила штучний інтелект Claude, готується до одного з найбільш обговорюваних біржових дебютів року. 🤖
📍 Де планується лістинг?
На американській біржі NASDAQ.
🔠 Очікуваний біржовий тикер: ANT.
📅 Орієнтовна дата початку торгів: 19 листопада 2026 року.
💵 Попередній ціновий діапазон IPO: $70–78 за акцію.
Але найцікавіше — оцінка всієї компанії може сягнути $1,4 трлн!
Що це означає для інвесторів?
Після початку біржових торгів акції потенційно можна буде придбати через брокерів, які надають доступ до NASDAQ.
Взяти участь безпосередньо в IPO складніше: розподіл акцій до початку торгів залежить від брокера та доступу до розміщення.
⚠️ Усі умови поки попередні й можуть змінитися.
👀 А ви хотіли б купити акції Anthropic у перший день торгів?
#Anthropic #IPO #NASDAQ
23

{future}(MUUUSDT)
Anthropic's IPO Draft Was Retracted. Treat the Headline Carefully.
$MUU
Reuters reported that IPO pricing details circulated to banks, then Anthropic said the pricing information was inaccurate and would be updated. The withdrawn draft showed a possible raise of up to $69.3 billion, but Reuters could not establish which details were wrong.
$ZHONGJI
The lesson is bigger than one AI company: a draft, a roadshow plan and a final offering are different stages. Headline valuations are not confirmed deal terms.
$OPG
For crypto readers watching AI-linked narratives, this is a reminder to separate private-company equity valuations from blockchain-token economics. They are not interchangeable assets.
Source: Reuters, Nov. 10, 2026.
Risk note: Do not trade on withdrawn or preliminary figures.
#AnthropicRejectsIPODelayValuationinQuestion #AIValuation #IPO #TechMarkets #CryptoResearch
Anthropic's IPO Draft Was Retracted. Treat the Headline Carefully.
$MUU
Reuters reported that IPO pricing details circulated to banks, then Anthropic said the pricing information was inaccurate and would be updated. The withdrawn draft showed a possible raise of up to $69.3 billion, but Reuters could not establish which details were wrong.
$ZHONGJI
The lesson is bigger than one AI company: a draft, a roadshow plan and a final offering are different stages. Headline valuations are not confirmed deal terms.
$OPG
For crypto readers watching AI-linked narratives, this is a reminder to separate private-company equity valuations from blockchain-token economics. They are not interchangeable assets.
Source: Reuters, Nov. 10, 2026.
Risk note: Do not trade on withdrawn or preliminary figures.
#AnthropicRejectsIPODelayValuationinQuestion #AIValuation #IPO #TechMarkets #CryptoResearch
$MUU
Reuters reported that IPO pricing details circulated to banks, then Anthropic said the pricing information was inaccurate and would be updated. The withdrawn draft showed a possible raise of up to $69.3 billion, but Reuters could not establish which details were wrong.
$ZHONGJI
The lesson is bigger than one AI company: a draft, a roadshow plan and a final offering are different stages. Headline valuations are not confirmed deal terms.
$OPG
For crypto readers watching AI-linked narratives, this is a reminder to separate private-company equity valuations from blockchain-token economics. They are not interchangeable assets.
Source: Reuters, Nov. 10, 2026.
Risk note: Do not trade on withdrawn or preliminary figures.
#AnthropicRejectsIPODelayValuationinQuestion #AIValuation #IPO #TechMarkets #CryptoResearch
1
346

·
--
Проверено
下周美股要从市场上一口气抽走将近 900 亿美元,就一家公司。
Anthropic 昨天开了路演,8.25 亿股,每股 70 到 78 美元,顶格算融 643 亿。另外还有 260 亿私募,英伟达、谷歌各掏 100 亿,AMD、博通、美光、微软、台积电都在名单里。按上限估值 1.4 万亿,5 月那轮才 9650 亿。北京时间 11/19 晚上在纳斯达克开始交易。
卧槽这个时间点挑得是真够硬。
CPI 刚超预期,12 月加息几乎被当成定局,$NVDA 一天又跌了 5.47%,收 168.89,盘中市值还被微软反超了一下。在这种盘面里发一个规模只比 SpaceX 那次小的 IPO,还给散户留了大约 20% 的份额,远高于一般的 5% 到 10%。
讲真我更在意的是钱从哪来。机构要腾出位置接这 600 多亿,最顺手的就是卖手里已经很重的 AI 老仓位。散户那 20% 也是同一拨风险偏好的钱。
BTC 这边,现货 ETF 截至周一已经连着 7 个交易日净流出,价格 7.37 万左右,本来就没什么新钱。下周要是 ANT 认购火爆,币圈会不会再被抽一管血
#美股 #AI #比特币 #IPO $NVDA $BTC
下周美股要从市场上一口气抽走将近 900 亿美元,就一家公司。
Anthropic 昨天开了路演,8.25 亿股,每股 70 到 78 美元,顶格算融 643 亿。另外还有 260 亿私募,英伟达、谷歌各掏 100 亿,AMD、博通、美光、微软、台积电都在名单里。按上限估值 1.4 万亿,5 月那轮才 9650 亿。北京时间 11/19 晚上在纳斯达克开始交易。
卧槽这个时间点挑得是真够硬。
CPI 刚超预期,12 月加息几乎被当成定局,$NVDA 一天又跌了 5.47%,收 168.89,盘中市值还被微软反超了一下。在这种盘面里发一个规模只比 SpaceX 那次小的 IPO,还给散户留了大约 20% 的份额,远高于一般的 5% 到 10%。
讲真我更在意的是钱从哪来。机构要腾出位置接这 600 多亿,最顺手的就是卖手里已经很重的 AI 老仓位。散户那 20% 也是同一拨风险偏好的钱。
BTC 这边,现货 ETF 截至周一已经连着 7 个交易日净流出,价格 7.37 万左右,本来就没什么新钱。下周要是 ANT 认购火爆,币圈会不会再被抽一管血
#美股 #AI #比特币 #IPO $NVDA $BTC
Anthropic 昨天开了路演,8.25 亿股,每股 70 到 78 美元,顶格算融 643 亿。另外还有 260 亿私募,英伟达、谷歌各掏 100 亿,AMD、博通、美光、微软、台积电都在名单里。按上限估值 1.4 万亿,5 月那轮才 9650 亿。北京时间 11/19 晚上在纳斯达克开始交易。
卧槽这个时间点挑得是真够硬。
CPI 刚超预期,12 月加息几乎被当成定局,$NVDA 一天又跌了 5.47%,收 168.89,盘中市值还被微软反超了一下。在这种盘面里发一个规模只比 SpaceX 那次小的 IPO,还给散户留了大约 20% 的份额,远高于一般的 5% 到 10%。
讲真我更在意的是钱从哪来。机构要腾出位置接这 600 多亿,最顺手的就是卖手里已经很重的 AI 老仓位。散户那 20% 也是同一拨风险偏好的钱。
BTC 这边,现货 ETF 截至周一已经连着 7 个交易日净流出,价格 7.37 万左右,本来就没什么新钱。下周要是 ANT 认购火爆,币圈会不会再被抽一管血
#美股 #AI #比特币 #IPO $NVDA $BTC
544
·
--
Рост
#AnthropicRejectsIPODelayValuationinQuestion
🚨 ANTHROPIC PUSHES AHEAD WITH IPO — BUT IS A $1.4 TRILLION VALUATION TOO HIGH?
Anthropic is moving forward with its highly anticipated IPO despite market uncertainty and growing questions about AI valuations.
The company is targeting a valuation of approximately $1.4 trillion, below the $2 trillion figure previously discussed. Its IPO could raise up to $64.4 billion, making it one of the biggest public offerings in history.
📊 WHY DOES THIS MATTER?
This IPO is more than just an Anthropic milestone. It will test how much investors are still willing to pay for the AI revolution.
A successful listing could strengthen confidence in AI-related technology stocks, while weaker demand could raise questions about stretched valuations across the technology sector.
₿ WHAT DOES THIS MEAN FOR CRYPTO?
Crypto markets could feel indirect effects through broader risk sentiment.
- Strong IPO demand could support confidence in high-growth technology investments.
- Weak investor demand could increase caution toward speculative assets.
- Bitcoin and altcoins may react to changing liquidity expectations and movements in technology stocks.
My Market Take:
The interesting part isn't simply whether Anthropic goes public. It's whether public-market investors accept its enormous valuation.
AI remains a major long-term growth story, but even promising companies must justify their prices.
For crypto traders, watching investor demand and broader market liquidity may be more useful than reacting to the IPO headline alone.
The real question: Is the AI boom still attracting fresh capital, or is investor enthusiasm starting to meet valuation reality?
#Anthropic #AI #CryptoMarket #IPO
$ANTHROPIC
{future}(ANTHROPICUSDT)
$AGT
{future}(AGTUSDT)
$ARIA
{future}(ARIAUSDT)
#AnthropicRejectsIPODelayValuationinQuestion
🚨 ANTHROPIC PUSHES AHEAD WITH IPO — BUT IS A $1.4 TRILLION VALUATION TOO HIGH?
Anthropic is moving forward with its highly anticipated IPO despite market uncertainty and growing questions about AI valuations.
The company is targeting a valuation of approximately $1.4 trillion, below the $2 trillion figure previously discussed. Its IPO could raise up to $64.4 billion, making it one of the biggest public offerings in history.
📊 WHY DOES THIS MATTER?
This IPO is more than just an Anthropic milestone. It will test how much investors are still willing to pay for the AI revolution.
A successful listing could strengthen confidence in AI-related technology stocks, while weaker demand could raise questions about stretched valuations across the technology sector.
₿ WHAT DOES THIS MEAN FOR CRYPTO?
Crypto markets could feel indirect effects through broader risk sentiment.
- Strong IPO demand could support confidence in high-growth technology investments.
- Weak investor demand could increase caution toward speculative assets.
- Bitcoin and altcoins may react to changing liquidity expectations and movements in technology stocks.
My Market Take:
The interesting part isn't simply whether Anthropic goes public. It's whether public-market investors accept its enormous valuation.
AI remains a major long-term growth story, but even promising companies must justify their prices.
For crypto traders, watching investor demand and broader market liquidity may be more useful than reacting to the IPO headline alone.
The real question: Is the AI boom still attracting fresh capital, or is investor enthusiasm starting to meet valuation reality?
#Anthropic #AI #CryptoMarket #IPO
$ANTHROPIC
$AGT
$ARIA
🚨 ANTHROPIC PUSHES AHEAD WITH IPO — BUT IS A $1.4 TRILLION VALUATION TOO HIGH?
Anthropic is moving forward with its highly anticipated IPO despite market uncertainty and growing questions about AI valuations.
The company is targeting a valuation of approximately $1.4 trillion, below the $2 trillion figure previously discussed. Its IPO could raise up to $64.4 billion, making it one of the biggest public offerings in history.
📊 WHY DOES THIS MATTER?
This IPO is more than just an Anthropic milestone. It will test how much investors are still willing to pay for the AI revolution.
A successful listing could strengthen confidence in AI-related technology stocks, while weaker demand could raise questions about stretched valuations across the technology sector.
₿ WHAT DOES THIS MEAN FOR CRYPTO?
Crypto markets could feel indirect effects through broader risk sentiment.
- Strong IPO demand could support confidence in high-growth technology investments.
- Weak investor demand could increase caution toward speculative assets.
- Bitcoin and altcoins may react to changing liquidity expectations and movements in technology stocks.
My Market Take:
The interesting part isn't simply whether Anthropic goes public. It's whether public-market investors accept its enormous valuation.
AI remains a major long-term growth story, but even promising companies must justify their prices.
For crypto traders, watching investor demand and broader market liquidity may be more useful than reacting to the IPO headline alone.
The real question: Is the AI boom still attracting fresh capital, or is investor enthusiasm starting to meet valuation reality?
#Anthropic #AI #CryptoMarket #IPO
$ANTHROPIC
$AGT
$ARIA
72
·
--
Anthropic is NOT delaying. Anthropic is NOT cancelling.
It is fighting over price.
What Happened?
Anthropic sent banks a filing: 866.7M shares at $70-$80 = raise up to $69.3B.
Hours later, it withdrew it. Said pricing was "inaccurate."
No corrected filing yet. S-1 is still live, price range still blank.
Roadshow starts Tuesday. Pricing next week. Listing before Thanksgiving.
Valuation War:
May 2026 Private Round: $965B
October Talk: $2.0T
Mid-October: $1.5T
Now Investors Say: $1.2T - $1.3T
One Big Investor Says: Closer to $1.0T
That is $500B - $1T wiped out before listing.
Why Investors Are Scared?
Q3 Revenue: $16.96B, +47% QoQ - still massive
But Future Commitments: $895.4B - mostly for compute
H1 Net Loss: $80.7B reported
Nasdaq -5.5% on Nov 5, worst day since April 2025
Why Anthropic Is NOT Backing Down?
$26B private placement already lined up from 7 giants:
Google, Nvidia, AMD, Broadcom, Micron, Microsoft, TSMC
At IPO price. Right after listing.
$112.4B cash on hand. It does not NEED this IPO. It wants it.
My Take:
This IPO is the AI bubble test.
If Anthropic prices at $1.5T, AI trade is alive.
If it cuts to $1.0T or delays, whole AI sector reprices lower.
Anthropic said NO to delay. Now market has to say YES to price.
Is Anthropic worth $1.5T or $1.0T?
Comment *1.5T* or *1.0T*
#Anthropic #Aİ #IPO
#AnthropicRejectsIPODelayValuationinQuestion
Anthropic is NOT delaying. Anthropic is NOT cancelling.
It is fighting over price.
What Happened?
Anthropic sent banks a filing: 866.7M shares at $70-$80 = raise up to $69.3B.
Hours later, it withdrew it. Said pricing was "inaccurate."
No corrected filing yet. S-1 is still live, price range still blank.
Roadshow starts Tuesday. Pricing next week. Listing before Thanksgiving.
Valuation War:
May 2026 Private Round: $965B
October Talk: $2.0T
Mid-October: $1.5T
Now Investors Say: $1.2T - $1.3T
One Big Investor Says: Closer to $1.0T
That is $500B - $1T wiped out before listing.
Why Investors Are Scared?
Q3 Revenue: $16.96B, +47% QoQ - still massive
But Future Commitments: $895.4B - mostly for compute
H1 Net Loss: $80.7B reported
Nasdaq -5.5% on Nov 5, worst day since April 2025
Why Anthropic Is NOT Backing Down?
$26B private placement already lined up from 7 giants:
Google, Nvidia, AMD, Broadcom, Micron, Microsoft, TSMC
At IPO price. Right after listing.
$112.4B cash on hand. It does not NEED this IPO. It wants it.
My Take:
This IPO is the AI bubble test.
If Anthropic prices at $1.5T, AI trade is alive.
If it cuts to $1.0T or delays, whole AI sector reprices lower.
Anthropic said NO to delay. Now market has to say YES to price.
Is Anthropic worth $1.5T or $1.0T?
Comment *1.5T* or *1.0T*
#Anthropic #Aİ #IPO
#AnthropicRejectsIPODelayValuationinQuestion
It is fighting over price.
What Happened?
Anthropic sent banks a filing: 866.7M shares at $70-$80 = raise up to $69.3B.
Hours later, it withdrew it. Said pricing was "inaccurate."
No corrected filing yet. S-1 is still live, price range still blank.
Roadshow starts Tuesday. Pricing next week. Listing before Thanksgiving.
Valuation War:
May 2026 Private Round: $965B
October Talk: $2.0T
Mid-October: $1.5T
Now Investors Say: $1.2T - $1.3T
One Big Investor Says: Closer to $1.0T
That is $500B - $1T wiped out before listing.
Why Investors Are Scared?
Q3 Revenue: $16.96B, +47% QoQ - still massive
But Future Commitments: $895.4B - mostly for compute
H1 Net Loss: $80.7B reported
Nasdaq -5.5% on Nov 5, worst day since April 2025
Why Anthropic Is NOT Backing Down?
$26B private placement already lined up from 7 giants:
Google, Nvidia, AMD, Broadcom, Micron, Microsoft, TSMC
At IPO price. Right after listing.
$112.4B cash on hand. It does not NEED this IPO. It wants it.
My Take:
This IPO is the AI bubble test.
If Anthropic prices at $1.5T, AI trade is alive.
If it cuts to $1.0T or delays, whole AI sector reprices lower.
Anthropic said NO to delay. Now market has to say YES to price.
Is Anthropic worth $1.5T or $1.0T?
Comment *1.5T* or *1.0T*
#Anthropic #Aİ #IPO
#AnthropicRejectsIPODelayValuationinQuestion
1
132
Anthropic IPO 定价 $70–78/股、估值最高 $1.4T,但加密市场几周前就通过链上盘前合约先完成了价格发现——纳斯达克只是在追赶。
Anthropic just priced its IPO at $70–$78 a share — up to a $1.4T valuation.
But here's the thing: crypto markets priced Anthropic weeks ago.
The roadshow happened on-chain first.
September's draft floated ~$2T. The filed range tops out at $1.4T fully diluted — and the first version was pulled within a day and refiled smaller.
Wall Street haggled the price down. Crypto didn't wait for the haggling.
Pre-IPO perps and options for Anthropic were already trading on-chain before the roadshow even started.
That's the real shift: price discovery for the biggest AI IPO in history didn't begin on Nasdaq.
It began on-chain. The exchange is just catching up.
#Anthropic #IPO #Crypto
Anthropic IPO 定价 $70–78/股、估值最高 $1.4T,但加密市场几周前就通过链上盘前合约先完成了价格发现——纳斯达克只是在追赶。
Anthropic just priced its IPO at $70–$78 a share — up to a $1.4T valuation.
But here's the thing: crypto markets priced Anthropic weeks ago.
The roadshow happened on-chain first.
September's draft floated ~$2T. The filed range tops out at $1.4T fully diluted — and the first version was pulled within a day and refiled smaller.
Wall Street haggled the price down. Crypto didn't wait for the haggling.
Pre-IPO perps and options for Anthropic were already trading on-chain before the roadshow even started.
That's the real shift: price discovery for the biggest AI IPO in history didn't begin on Nasdaq.
It began on-chain. The exchange is just catching up.
#Anthropic #IPO #Crypto
Anthropic just priced its IPO at $70–$78 a share — up to a $1.4T valuation.
But here's the thing: crypto markets priced Anthropic weeks ago.
The roadshow happened on-chain first.
September's draft floated ~$2T. The filed range tops out at $1.4T fully diluted — and the first version was pulled within a day and refiled smaller.
Wall Street haggled the price down. Crypto didn't wait for the haggling.
Pre-IPO perps and options for Anthropic were already trading on-chain before the roadshow even started.
That's the real shift: price discovery for the biggest AI IPO in history didn't begin on Nasdaq.
It began on-chain. The exchange is just catching up.
#Anthropic #IPO #Crypto
113
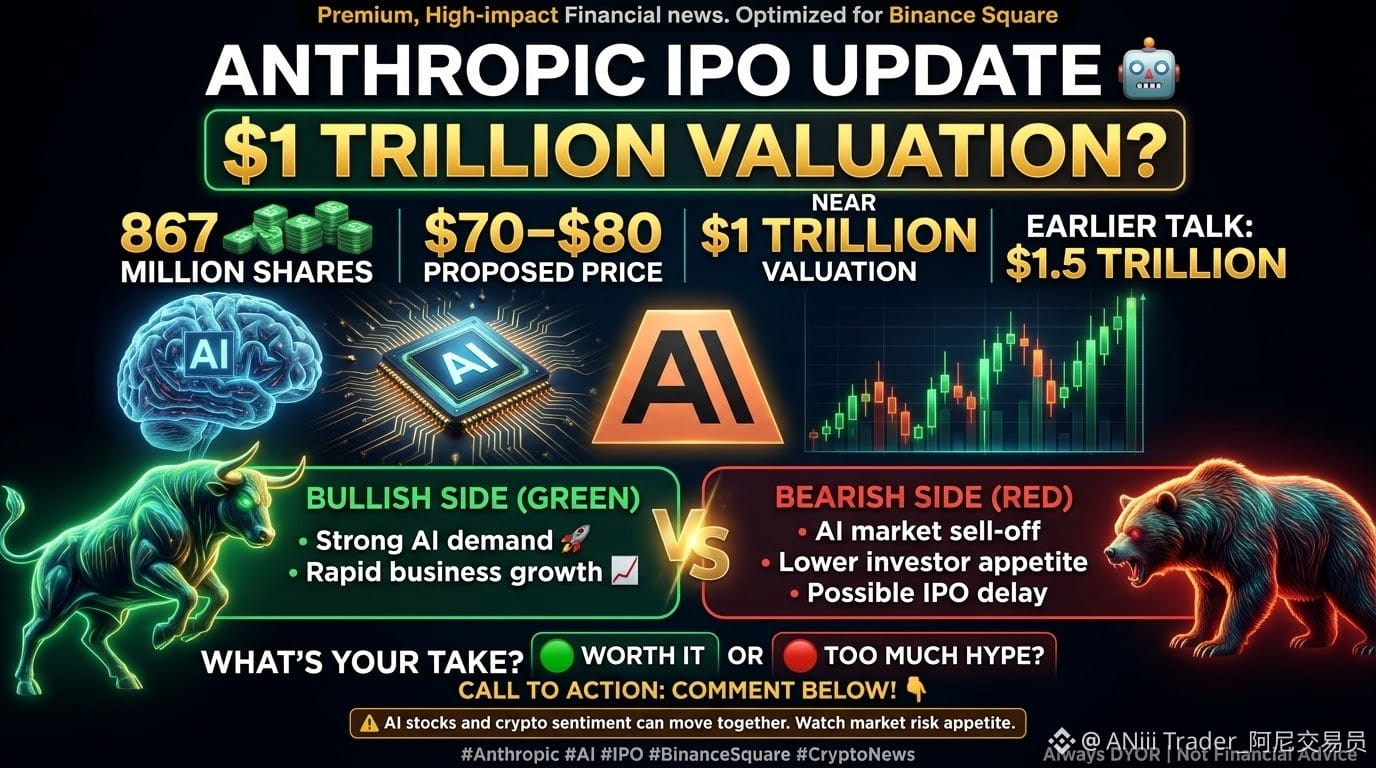
🤖 ANTHROPIC'S IPO PRICE: THE $1 TRILLION QUESTION! 💰
📈 Anthropic is reportedly planning to sell about 867M shares at $70-$80, which values it near $1T at the top of the range. That is down from the earlier $1.5T talk. 👀🔥
💚 THE BULL CASE: Fast growth and huge demand for AI tools.
🔴 THE BEAR CASE: After the AI sell-off, some investors want a lower price, and a delay is still possible.
⚠️ AI stocks and crypto sentiment often move together, so watch risk appetite. ⚠️
💬 YOUR TAKE?
🟢 Worth it or 🔴 Too much hype? Comment below! 👇✨
⚠️ Not financial advice. Always DYOR! 👑
#Anthropic #AI #IPO #BinanceSquare #CryptoNews
$ARIA
{future}(ARIAUSDT)
$AGT
{future}(AGTUSDT)
🤖 ANTHROPIC'S IPO PRICE: THE $1 TRILLION QUESTION! 💰
📈 Anthropic is reportedly planning to sell about 867M shares at $70-$80, which values it near $1T at the top of the range. That is down from the earlier $1.5T talk. 👀🔥
💚 THE BULL CASE: Fast growth and huge demand for AI tools.
🔴 THE BEAR CASE: After the AI sell-off, some investors want a lower price, and a delay is still possible.
⚠️ AI stocks and crypto sentiment often move together, so watch risk appetite. ⚠️
💬 YOUR TAKE?
🟢 Worth it or 🔴 Too much hype? Comment below! 👇✨
⚠️ Not financial advice. Always DYOR! 👑
#Anthropic #AI #IPO #BinanceSquare #CryptoNews
$ARIA
$AGT
📈 Anthropic is reportedly planning to sell about 867M shares at $70-$80, which values it near $1T at the top of the range. That is down from the earlier $1.5T talk. 👀🔥
💚 THE BULL CASE: Fast growth and huge demand for AI tools.
🔴 THE BEAR CASE: After the AI sell-off, some investors want a lower price, and a delay is still possible.
⚠️ AI stocks and crypto sentiment often move together, so watch risk appetite. ⚠️
💬 YOUR TAKE?
🟢 Worth it or 🔴 Too much hype? Comment below! 👇✨
⚠️ Not financial advice. Always DYOR! 👑
#Anthropic #AI #IPO #BinanceSquare #CryptoNews
$ARIA
$AGT
132
$ANTHROPIC
{future}(ANTHROPICUSDT)
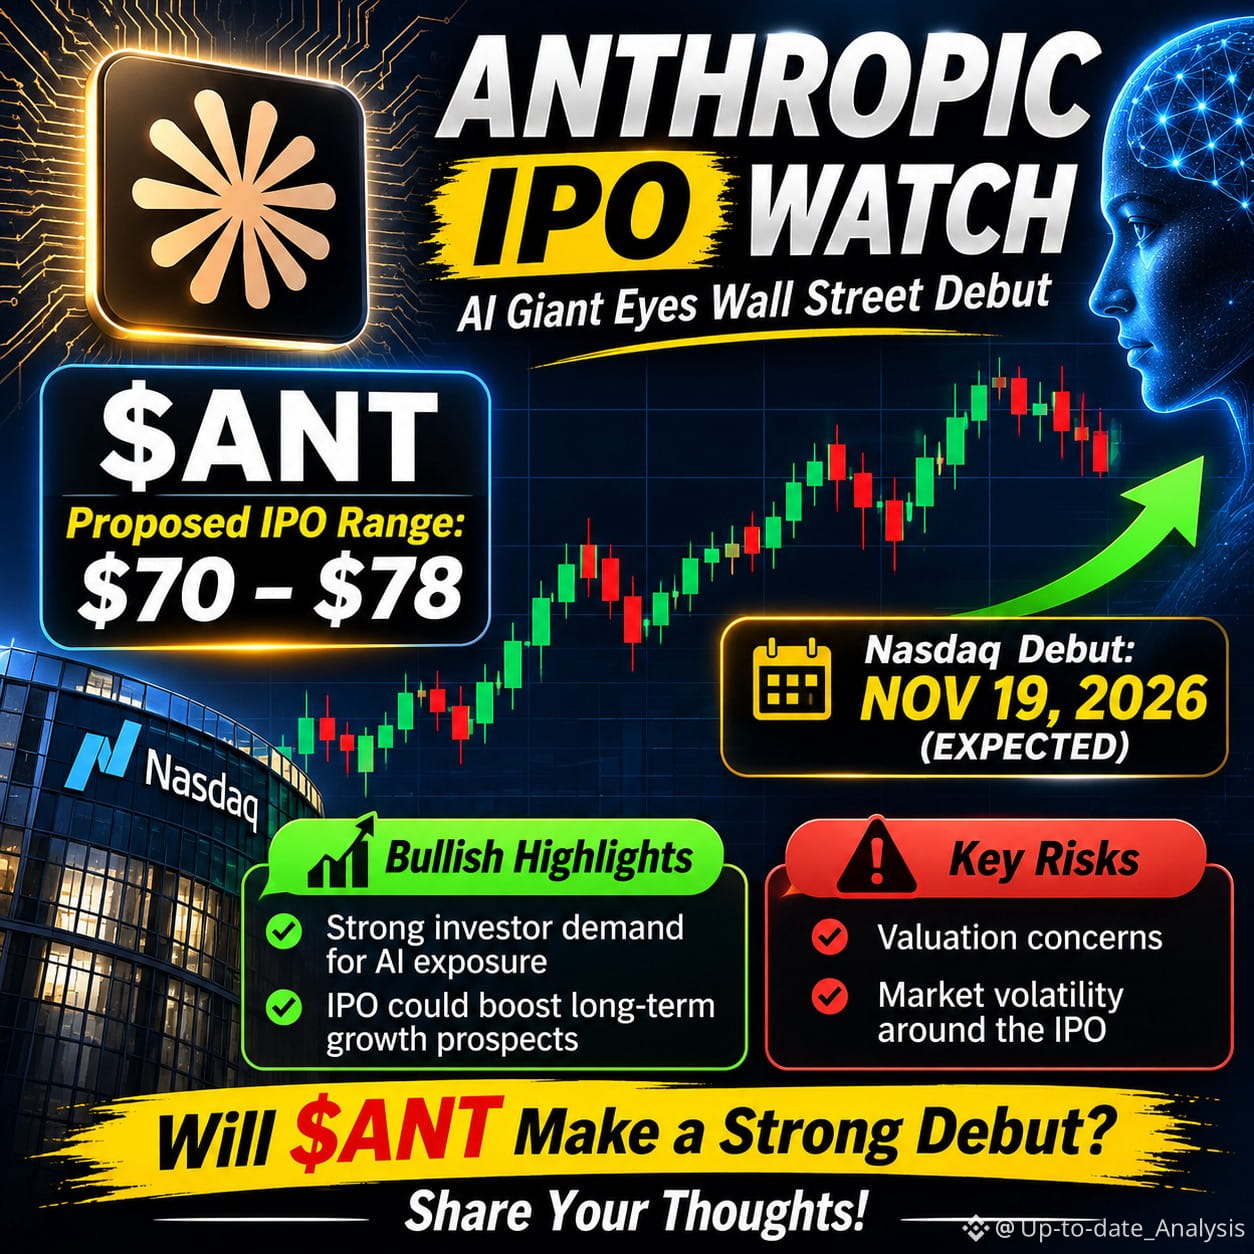
🚀 ANTHROPIC (ANT): THE AI IPO EVERYONE IS WATCHING! 📊
Anthropic, the company behind Claude AI, is preparing for a major Nasdaq debut under ticker $ANT.
🔥 Bullish Factors:
- Growing demand for advanced AI technology.
- Strong interest from major technology investors.
- Proposed IPO price range: $70–$78 per share.
⚠️ Key Risk: A high valuation and massive AI infrastructure costs could create volatility.
📈 What’s Next? Investors are watching the expected November 19 listing.
💬 Will $ANT become one of the biggest AI market stories of 2026? Share your prediction!
#Anthropic #ClaudeAI #ArtificialIntelligence #IPO #ANT
$ANTHROPIC
🚀 ANTHROPIC (ANT): THE AI IPO EVERYONE IS WATCHING! 📊
Anthropic, the company behind Claude AI, is preparing for a major Nasdaq debut under ticker $ANT.
🔥 Bullish Factors:
- Growing demand for advanced AI technology.
- Strong interest from major technology investors.
- Proposed IPO price range: $70–$78 per share.
⚠️ Key Risk: A high valuation and massive AI infrastructure costs could create volatility.
📈 What’s Next? Investors are watching the expected November 19 listing.
💬 Will $ANT become one of the biggest AI market stories of 2026? Share your prediction!
#Anthropic #ClaudeAI #ArtificialIntelligence #IPO #ANT
🚀 ANTHROPIC (ANT): THE AI IPO EVERYONE IS WATCHING! 📊
Anthropic, the company behind Claude AI, is preparing for a major Nasdaq debut under ticker $ANT.
🔥 Bullish Factors:
- Growing demand for advanced AI technology.
- Strong interest from major technology investors.
- Proposed IPO price range: $70–$78 per share.
⚠️ Key Risk: A high valuation and massive AI infrastructure costs could create volatility.
📈 What’s Next? Investors are watching the expected November 19 listing.
💬 Will $ANT become one of the biggest AI market stories of 2026? Share your prediction!
#Anthropic #ClaudeAI #ArtificialIntelligence #IPO #ANT
134
·
--
#AnthropicRejectsIPODelayValuationinQuestion
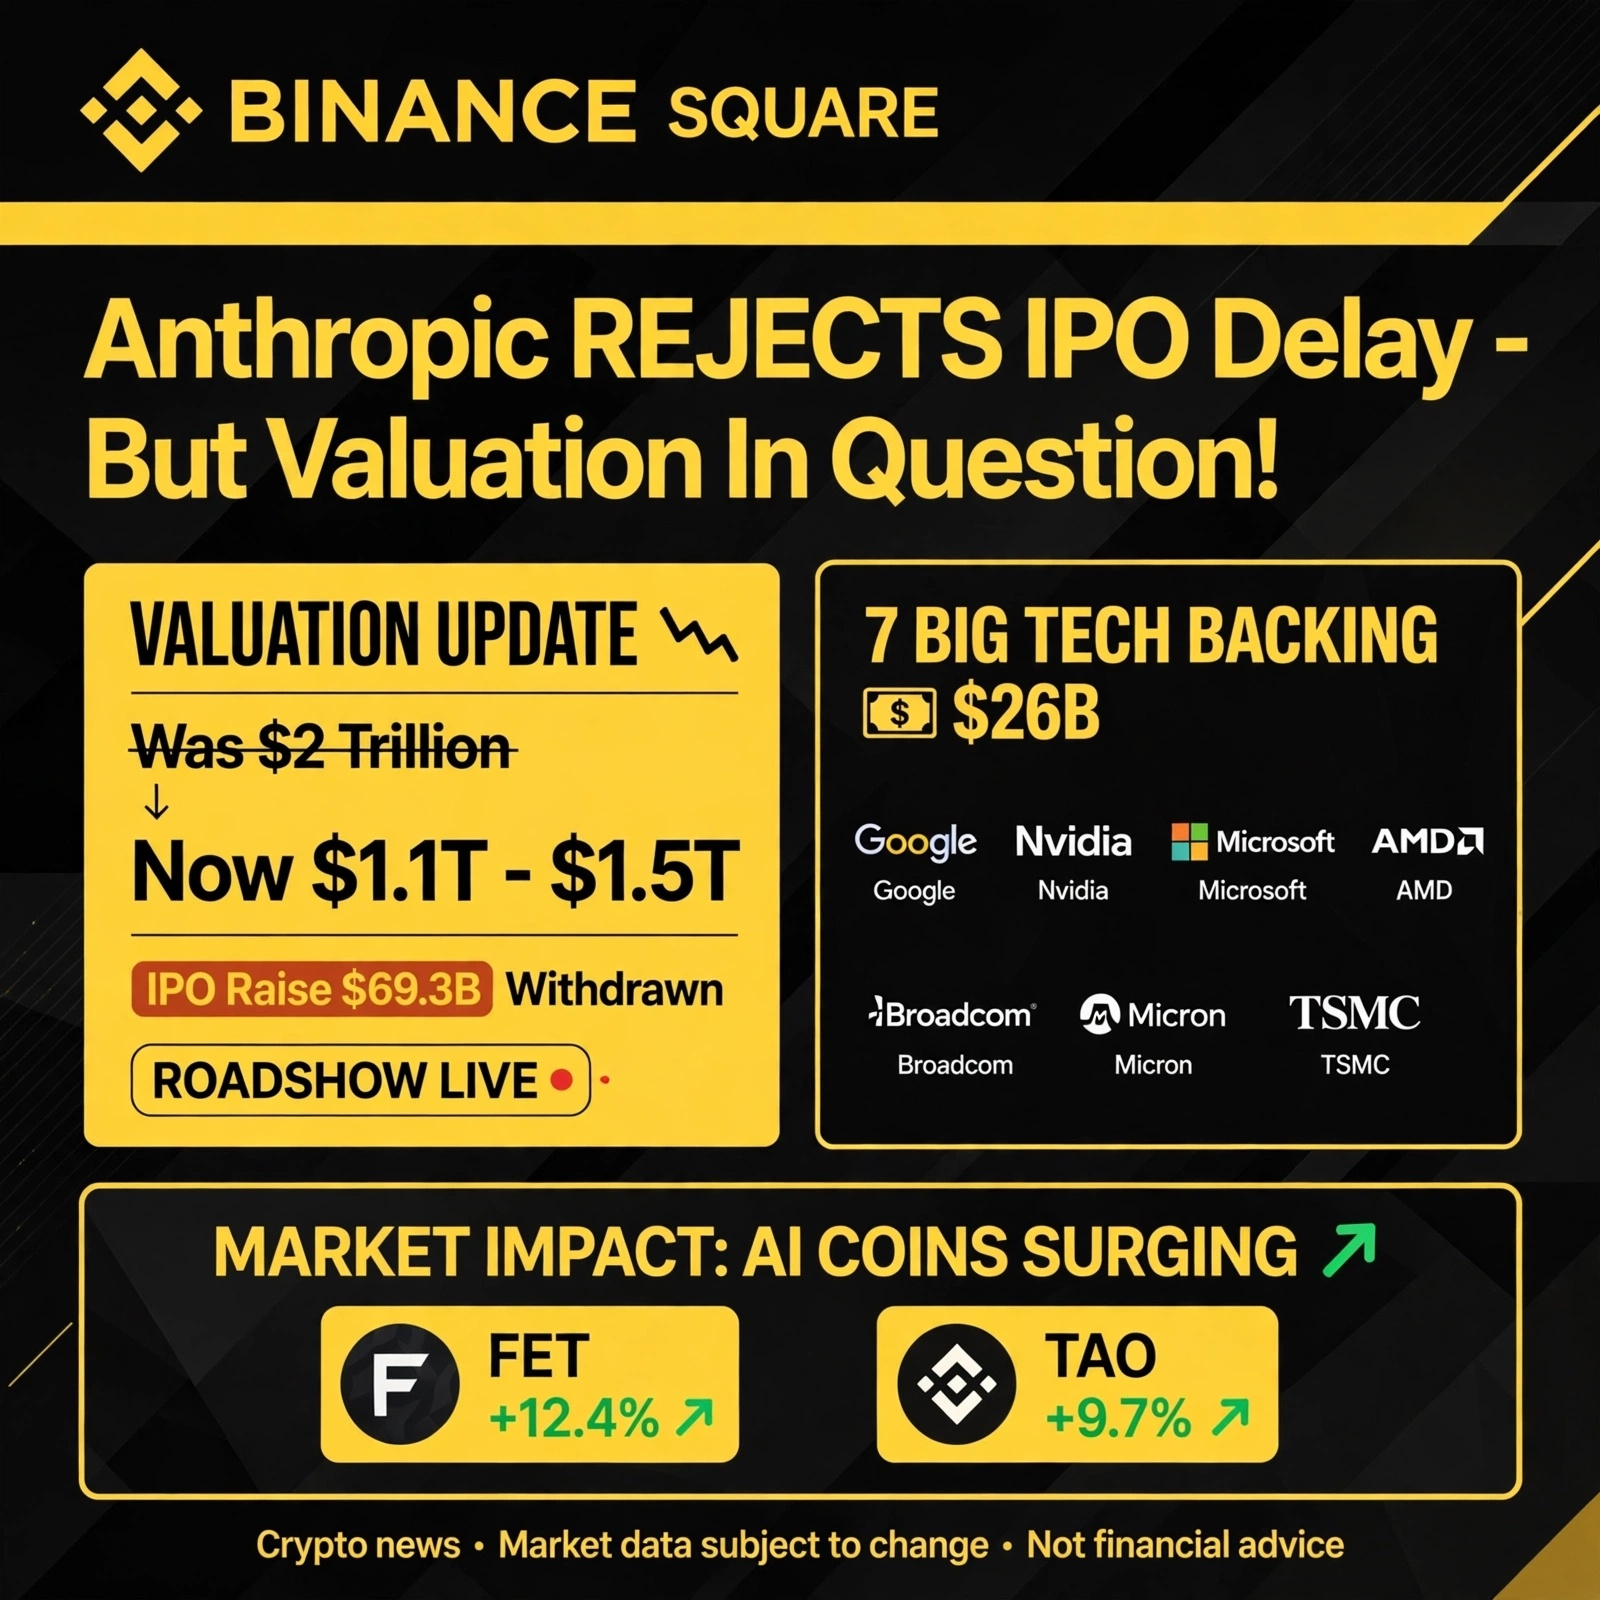
Everyone is saying the Anthropic CANCELLED its IPO. That's *FALSE.*
Anthropic says: *We will NOT delay.* Roadshow is LIVE. Listing before Thanksgiving.
But the REAL drama is Valuation War:
*Before:* $2 Trillion dream
*Banks Now:* $1.4T - $1.5T
*Big Investors:* $1.1T is fair, some say $1T
= *$500B - $900B wiped out before listing!*
Yesterday Anthropic sent banks a filing to raise *$69.3B* (866M shares at $70-$80) — then withdrew it saying "pricing error". S-1 still lives on the SEC, but the price is BLANK.
Still, 7 Big Tech are backing it with *$26B* private placement: Google, Nvidia, Microsoft, AMD, Broadcom, Micron, TSMC.
Revenue is REAL: Q3 ∼$16.8B, up to 45% QoQ.
*What does it mean for Crypto?*
AI coins are already reacting: FET +5.9%, TAO +4.7% in 24h. If IPO succeeds = AI narrative back. If it fails = AI bubble fear for BTC & Altcoins.
Is Anthropic worth $1.5T or is this the biggest overvaluation in tech history? 👇
#Anthropic $AI #Claude #IPO #CryptoAI #Binance #BinanceSquare #Bitcoin $FET $TAO #TechStocks
#AnthropicRejectsIPODelayValuationinQuestion
Everyone is saying the Anthropic CANCELLED its IPO. That's *FALSE.*
Anthropic says: *We will NOT delay.* Roadshow is LIVE. Listing before Thanksgiving.
But the REAL drama is Valuation War:
*Before:* $2 Trillion dream
*Banks Now:* $1.4T - $1.5T
*Big Investors:* $1.1T is fair, some say $1T
= *$500B - $900B wiped out before listing!*
Yesterday Anthropic sent banks a filing to raise *$69.3B* (866M shares at $70-$80) — then withdrew it saying "pricing error". S-1 still lives on the SEC, but the price is BLANK.
Still, 7 Big Tech are backing it with *$26B* private placement: Google, Nvidia, Microsoft, AMD, Broadcom, Micron, TSMC.
Revenue is REAL: Q3 ∼$16.8B, up to 45% QoQ.
*What does it mean for Crypto?*
AI coins are already reacting: FET +5.9%, TAO +4.7% in 24h. If IPO succeeds = AI narrative back. If it fails = AI bubble fear for BTC & Altcoins.
Is Anthropic worth $1.5T or is this the biggest overvaluation in tech history? 👇
#Anthropic $AI #Claude #IPO #CryptoAI #Binance #BinanceSquare #Bitcoin $FET $TAO #TechStocks
Everyone is saying the Anthropic CANCELLED its IPO. That's *FALSE.*
Anthropic says: *We will NOT delay.* Roadshow is LIVE. Listing before Thanksgiving.
But the REAL drama is Valuation War:
*Before:* $2 Trillion dream
*Banks Now:* $1.4T - $1.5T
*Big Investors:* $1.1T is fair, some say $1T
= *$500B - $900B wiped out before listing!*
Yesterday Anthropic sent banks a filing to raise *$69.3B* (866M shares at $70-$80) — then withdrew it saying "pricing error". S-1 still lives on the SEC, but the price is BLANK.
Still, 7 Big Tech are backing it with *$26B* private placement: Google, Nvidia, Microsoft, AMD, Broadcom, Micron, TSMC.
Revenue is REAL: Q3 ∼$16.8B, up to 45% QoQ.
*What does it mean for Crypto?*
AI coins are already reacting: FET +5.9%, TAO +4.7% in 24h. If IPO succeeds = AI narrative back. If it fails = AI bubble fear for BTC & Altcoins.
Is Anthropic worth $1.5T or is this the biggest overvaluation in tech history? 👇
#Anthropic $AI #Claude #IPO #CryptoAI #Binance #BinanceSquare #Bitcoin $FET $TAO #TechStocks
1
1
632
Войдите, чтобы посмотреть больше материала
Присоединяйтесь к пользователям криптовалют по всему миру на Binance Square
⚡️ Получайте новейшую и полезную информацию о криптоактивах.
💬 Нам доверяет крупнейшая в мире криптобиржа.
👍 Получите достоверные аналитические данные от верифицированных создателей контента.
Эл. почта/номер телефона
В тренде
1
#HuangRisksOusterOverReportedAffairWithSubordinate
Просмотров: 27,624
469 обсуждают
2
#AnthropicRejectsIPODelayValuationinQuestion
Просмотров: 470,966
3,922 обсуждают
3
#CoreWeaveJumps10%On168%RevenueGrowth
Просмотров: 65,941
883 обсуждают
4
#ZcashFallsBelow$1000ForFirstTimeSinceSeptember
Просмотров: 37,653
187 обсуждают
5
#MSCIRemovalMayCurbStrategy’sBitcoinBuying
Просмотров: 1,101
53 обсуждают
6
#CanNvidiaEarningsEaseMarketConcerns?
Просмотров: 177,254
1,823 обсуждают
7
#SouthKoreaToLetExchangesSuspendWithdrawalsOnSuspectedHacks
Просмотров: 0
1 обсуждают
8
#PythAddsNYSERealTimeDataToMarketplace
Просмотров: 837
45 обсуждают
9
#SolanaCompanyReports$3.4MQ3Revenue
Просмотров: 952
22 обсуждают
10
#tZEROWinsCFTCApprovalForRegulatedDerivativesExchange
Просмотров: 715
12 обсуждают