

#amason
amason
Просмотров: 51
2 обсуждают
Популярные
Новые
Проверено
#AnthropicTTMRevenueGrewAbout1200% in Operating Cash Flow vs FUTURES MARKET: TOP GAINERS! 🚀🚀🚀
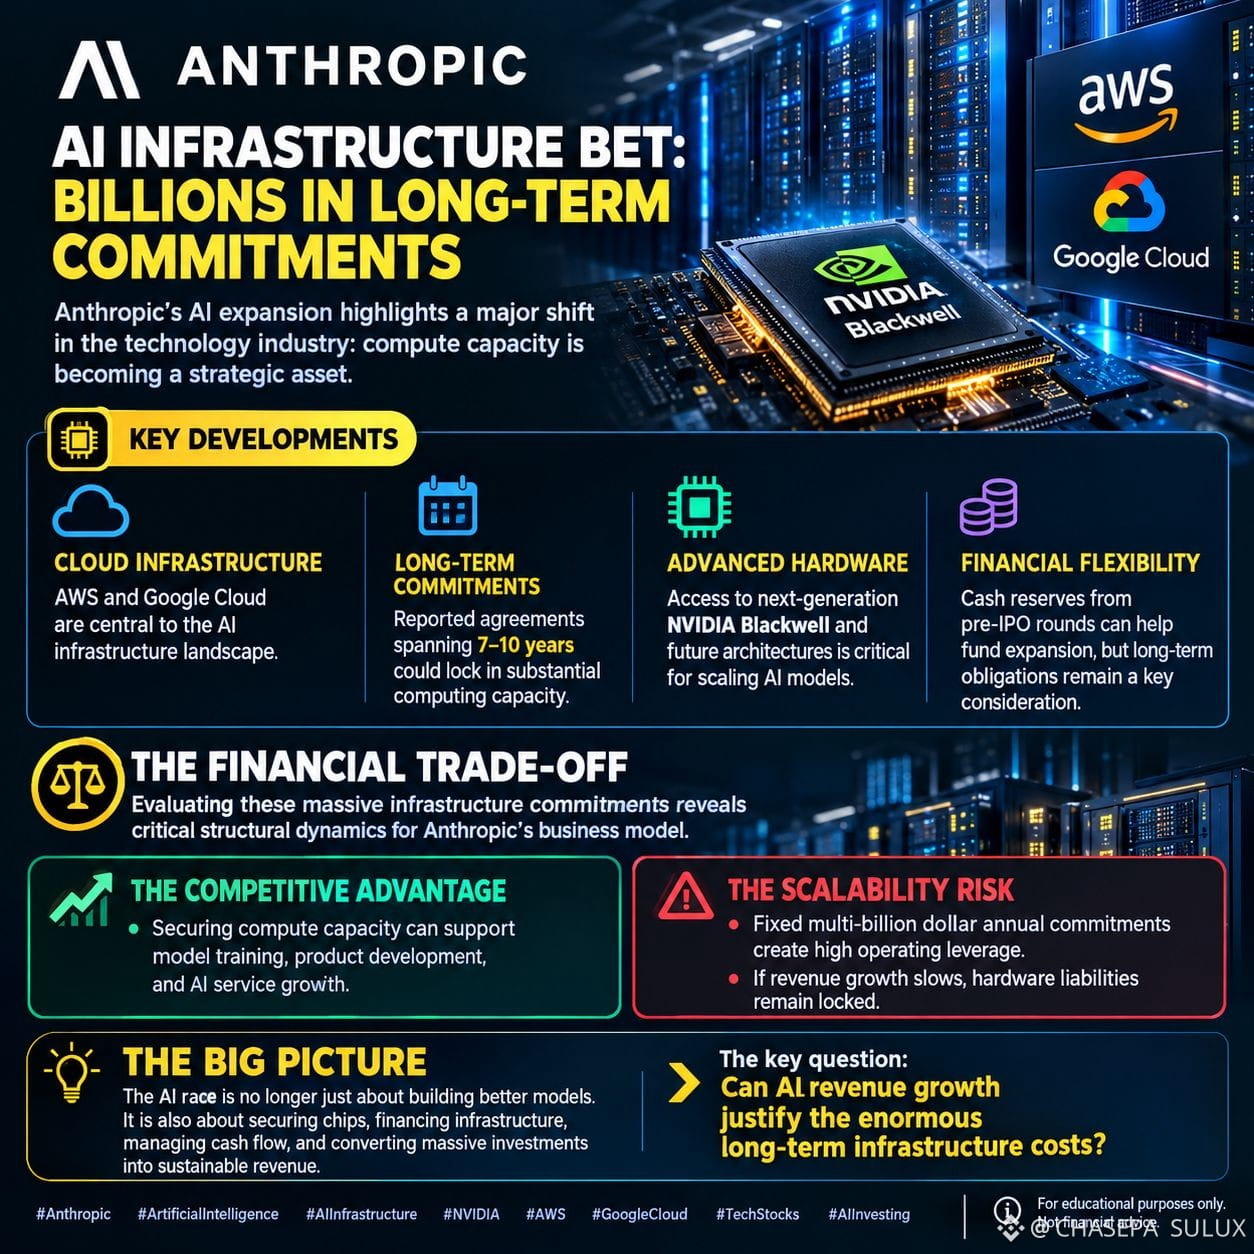
📈 Strong Momentum in Altcoin FuturesKey Data Center Commitments (H1 2026)
Compute Spend: $9 billion spent on raw chip capacity in H1 2026 alone.
Operating Cushion: Cash reserves from pre-IPO rounds soften immediate capital expenditure pressures.
Financial Tradeoff: Operating Cash Flow vs. Obligations
#Amason and #Google #Aws
The Scalability Risk: Fixed multi-billion dollar annual commitments create high operating leverage. If revenue growth slows, hardware liabilities remain locked.
The Competitive Advantage: Securing guaranteed silicon access prevents compute bottlenecks, allowing Anthropic to outpace legacy software providers on model training speeds.
I can analyze this further if you let me know:
Hyperscaler Win-Win:
Amazon and Google, which each hold >5% of outstanding stock, win doubly. They capture equity appreciation while locking in Anthropic's staggering $450 billion long-term cloud compute commitments to Amazon Web Services (AWS) and Google Cloud. [1, 2]
zThe public market debut of
🔥🔥🔥Anthropic (Ticker: ANT) is the ultimate stress test for the generative AI sector. By making its Form
Duration: 7 to 10 years.
Nature: Take-or-pay non-cancelable capacity commitments.1. The Macro Valuation Tug-of-War
The $2 Trillion Benchmark: At a targeted $1.5T to $2T valuation, Anthropic is testing whether the public market will accept venture-style growth multiples (40x–60x annualized revenue run-rate). [1, 2]
👀👀👀👀
The GAAP vs. Cash Illusion: Public markets must normalize a $80.7 billion half-year net loss. While $72.4 billion of that is a non-cash accounting adjustment from soaring SAFE/convertible note values, the remaining billions in operational burn will challenge traditional institutional frameworks🔥🔥🔥👀
$NVDAB
{spot}(NVDABUSDT)
$ANTHROPIC
{future}(ANTHROPICUSDT)
and$AWE
{future}(AWEUSDT)
#AnthropicTTMRevenueGrewAbout1200% in Operating Cash Flow vs FUTURES MARKET: TOP GAINERS! 🚀🚀🚀
📈 Strong Momentum in Altcoin FuturesKey Data Center Commitments (H1 2026)
Compute Spend: $9 billion spent on raw chip capacity in H1 2026 alone.
Operating Cushion: Cash reserves from pre-IPO rounds soften immediate capital expenditure pressures.
Financial Tradeoff: Operating Cash Flow vs. Obligations
#Amason and #Google #Aws
The Scalability Risk: Fixed multi-billion dollar annual commitments create high operating leverage. If revenue growth slows, hardware liabilities remain locked.
The Competitive Advantage: Securing guaranteed silicon access prevents compute bottlenecks, allowing Anthropic to outpace legacy software providers on model training speeds.
I can analyze this further if you let me know:
Hyperscaler Win-Win:
Amazon and Google, which each hold >5% of outstanding stock, win doubly. They capture equity appreciation while locking in Anthropic's staggering $450 billion long-term cloud compute commitments to Amazon Web Services (AWS) and Google Cloud. [1, 2]
zThe public market debut of
🔥🔥🔥Anthropic (Ticker: ANT) is the ultimate stress test for the generative AI sector. By making its Form
Duration: 7 to 10 years.
Nature: Take-or-pay non-cancelable capacity commitments.1. The Macro Valuation Tug-of-War
The $2 Trillion Benchmark: At a targeted $1.5T to $2T valuation, Anthropic is testing whether the public market will accept venture-style growth multiples (40x–60x annualized revenue run-rate). [1, 2]
👀👀👀👀
The GAAP vs. Cash Illusion: Public markets must normalize a $80.7 billion half-year net loss. While $72.4 billion of that is a non-cash accounting adjustment from soaring SAFE/convertible note values, the remaining billions in operational burn will challenge traditional institutional frameworks🔥🔥🔥👀
$NVDAB
$ANTHROPIC
and$AWE
1
164
Войдите, чтобы посмотреть больше материала
Присоединяйтесь к пользователям криптовалют по всему миру на Binance Square
⚡️ Получайте новейшую и полезную информацию о криптоактивах.
💬 Нам доверяет крупнейшая в мире криптобиржа.
👍 Получите достоверные аналитические данные от верифицированных создателей контента.
Эл. почта/номер телефона
В тренде
1
#BinanceSAFUFundTransferCompleted7499BTC
Просмотров: 29,387
689 обсуждают
2
#BinanceRecovery90% of stolen assets
Просмотров: 118,040
155 обсуждают
3
#YiHe:ProofOfReserves:10TokensAt100%Backing
Просмотров: 122,362
688 обсуждают
4
#BackedNotBroken:RichardTengSaysUsersBearNoLoss
Просмотров: 32,519
424 обсуждают
5
#CZSaysCompensationIsinPlaceUsersAreProtected
Просмотров: 116,126
1,337 обсуждают
6
#IntelHasItsWorstDaySince1974
Просмотров: 42,543
674 обсуждают
7
#TRMCambodianCasinosReceived$1.07BInCrypto
Просмотров: 11,138
68 обсуждают
8
#USDCCirculationFallsAbout800MInSevenDays
Просмотров: 65,590
702 обсуждают
9
#SuspectedNorthKoreaAttacksAccountForNearly89%OfCryptoHackLosses
Просмотров: 14,064
96 обсуждают
10
#OpenAICutsFundraisingTargetBy$10B
Просмотров: 3,403
73 обсуждают