

In the ten days following bitcoin's move from the low $60,000s to above $80,000, something instructive happened in the crypto-adjacent equity space.
MicroStrategy gained 29%. Marathon Digital gained 40%. Coinbase gained 25%.
bitcoin gained roughly 25–30% over the same period. The equities — companies whose businesses are directly tied to the crypto market — outperformed the underlying asset itself.
This is not a coincidence. It is a structural feature of how crypto-equities behave relative to spot crypto, and it has significant implications for how investors construct positions when they have a directional view on the crypto market.
The Beta Difference
The concept of beta in finance describes how much an asset moves relative to a reference asset. A stock with a beta of 2 relative to the broader market tends to move twice as much — up and down — as the market does. A stock with a beta of 0.5 moves half as much.
Crypto-equities — companies like MicroStrategy, which holds bitcoin on its balance sheet as a primary treasury asset; Marathon Digital, which mines bitcoin; and Coinbase, which generates revenue from crypto trading volume — carry elevated beta relative to spot crypto. This is because their value is not just the current price of bitcoin. It is the leveraged exposure to bitcoin through a business structure.
MicroStrategy does not just hold bitcoin. It holds bitcoin purchased partly with debt, amplifying both gains and losses relative to the underlying. When bitcoin rises 25%, a levered bitcoin holding company can rise more than that — because the leverage amplifies the gain on the underlying position relative to the company's equity value.
Marathon Digital's business economics are similarly amplified. When bitcoin prices rise, the value of each bitcoin mined increases. But the company's cost structure — mining infrastructure, energy contracts, operational overhead — is relatively fixed in dollar terms. A 25% rise in bitcoin revenue against a fixed cost base produces an earnings amplification that can drive the stock significantly above the underlying asset's return.
Coinbase benefits from trading volume, which typically surges during price rallies. More volume means more fee revenue. The Q3 earnings cycle confirmed this pattern: crypto trading volumes surged during the bitcoin rally, and Coinbase's revenue reflected it.
One View, Multiple Instruments
The practical implication of the beta differential is significant for investors who have a directional view on the crypto market.
Suppose an investor believes bitcoin is in the early stages of a sustained move higher. The simplest expression of that view is spot bitcoin — buy bitcoin and hold it. But spot bitcoin delivers exactly 1x exposure to bitcoin's price movement. Nothing more, nothing less.
The same directional view can be expressed through multiple instruments, each with different beta and different risk characteristics:
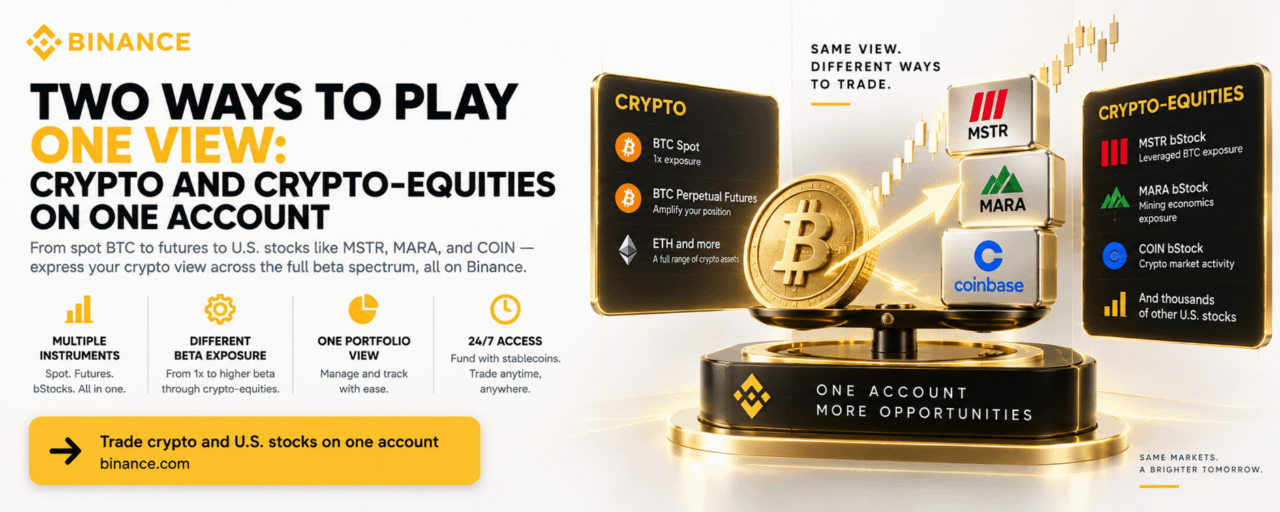
Spot BTC: The purest expression. 1x exposure to bitcoin's price. No additional operational risk, no management of equity-specific factors. The floor of the beta range.
BTC perpetual futures: Provides leverage on the same underlying price, allowing higher notional exposure with a smaller capital commitment. Risk is amplified in both directions, and funding rates apply.
MSTR bStock: Exposure to a company whose primary asset is a leveraged bitcoin treasury. Historical beta to bitcoin has exceeded 2 during sustained rallies — meaning a 25% bitcoin move can drive MSTR 40–50%+. The tradeoff is equity-specific risk: management decisions, balance sheet structure, and potential share dilution.
MARA bStock: Exposure to bitcoin mining economics. Beta is elevated because of operational leverage — fixed mining costs against variable bitcoin revenue. Also carries sector-specific risks including energy costs and hash rate competition.
COIN bStock: Exposure to crypto market activity broadly. Elevated beta during volume surges, more diversified crypto exposure than a single-asset holding, but also subject to regulatory and competitive dynamics specific to the exchange industry.
The investor with a bullish crypto view can allocate across this beta spectrum rather than concentrating in a single instrument — taking spot BTC as the core position, adding perpetual futures for amplified directional exposure, and selectively adding crypto-equity bStocks for the highest-beta expression of the same thesis.
What Binance Makes Possible
The reason this multi-instrument strategy has historically been difficult for most investors is infrastructure fragmentation. Spot BTC trades on one exchange. Futures trade on the same or a different exchange. Equity exposure to MSTR, MARA, or COIN requires a brokerage account — often a separate application, separate KYC, separate funding, and a different interface entirely.
Most investors who want to express a cross-instrument crypto view have had to manage multiple accounts, transfer funds between platforms, and keep track of exposures across disconnected systems. The operational friction is significant enough that most retail investors simply pick one instrument rather than optimizing across the beta spectrum.
Binance has changed this. A single Binance account now provides access to:
Spot BTC, ETH, and the full range of crypto assets
BTC perpetual futures and the full derivatives suite
Binance Stocks and bStocks for MSTR, MARA, COIN, and thousands of other U.S.-listed equities
All of the above in a single portfolio view, funded with stablecoins, available 24/7
The investor who wanted to put on a cross-instrument bullish crypto trade during the recent rally — long spot BTC as the core, long MSTR bStock for the leveraged equity beta, long MARA bStock for mining economics exposure — could do all of it from one account, manage the positions in one interface, and track the combined P&L in one view.
That operational integration is not a minor convenience. It is the difference between a strategy that is theoretically sound but practically difficult to execute, and one that is executable in minutes from a single platform.
The Risk Framing
It is worth being explicit about what the beta differential means in the downside scenario, not just the upside.
The same leverage that drove MARA +40% during a 25% bitcoin rally would drive MARA significantly harder in the opposite direction during a bitcoin decline. Mining companies with high fixed costs and volatile revenue are among the most volatile instruments in the crypto ecosystem. MicroStrategy's leveraged bitcoin position amplifies losses exactly as much as it amplifies gains.
A multi-instrument position that captures the upside beta of crypto-equities is also a position that is more exposed to the downside than spot bitcoin alone. This is a deliberate risk-return tradeoff, not an unintended consequence. The investor who constructs it is exchanging some protection for higher beta in the upside scenario.
Understanding the beta of each instrument in the portfolio — not just the directional view on bitcoin — is the analytical work that multi-instrument crypto allocation requires.
Disclaimer: This article is for educational purposes only and does not constitute financial advice. All trading and investment activities involve risk. Perpetual futures involve leverage. bStocks do not confer shareholder voting rights. Please conduct your own research before making any decisions.