


Throughout the long history of financial development, the fixed income market has played a crucial role. As bond king Bill Gross stated: "Bonds as an asset class will always be needed, not just by insurance companies and pension funds, but also by the aging baby boomer generation." This statement profoundly reveals the irreplaceable position of fixed income in the modern financial system.
The birth of the fixed income market stems from humanity's fundamental need for credit as an economic activity. Whether we believe that money originated from the inefficiencies of barter or that credit is the main catalyst for money creation, the economic behavior of credit or future returns marks a pivotal moment in human history. Through credit mechanisms, individuals, businesses, and governments can engage in lending activities, promoting increased consumer spending, while lenders can earn returns from idle assets. This simple yet effective dynamic mechanism makes fixed income the cornerstone of today's financial markets, surpassing the real estate market and far exceeding equity and commodity markets, becoming the largest investable asset class in traditional finance.
From a historical perspective, evidence of fixed income in early records is relatively scarce, suggesting that it may be a relatively new phenomenon. However, lending activities likely existed from the earliest times of civilization, operating through reputational considerations and simple social consequences within communities. Just as cultural anthropologists face confusion when encountering non-literate tribes deep in the Amazon, the behavior patterns of bond market participants are similarly filled with complexity and mystery.
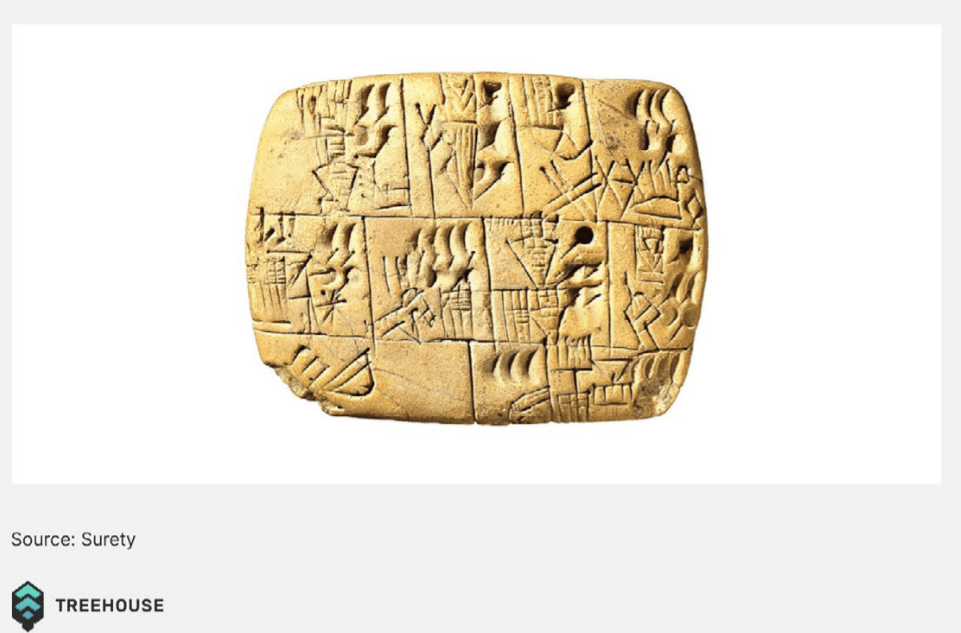
The earliest known bonds can be traced back to 2400 BC in Nippur, Iraq, where corn was used as currency. In ancient times, grains were a common medium for loans, allowing borrowers to use the borrowed items to cultivate crops as repayment. By 1700 BC, silver had replaced grains as the preferred medium of exchange in Mesopotamia. However, due to its inherent characteristics, silver loans posed problems for early borrowers. Unlike grains, silver metal cannot directly produce more silver. To maintain the normal functioning of the credit market and adequately meet the complex needs of the economy, the sixth king of Babylon intervened and issued decrees to unify the price of silver and lending rates, establishing the first known interest rate practice in society.
Since then, innovations in fixed income have gradually developed over centuries, with significant developments occurring around 300-400 BC. In India, innovations took the form of letters of credit, providing insurance for loans through third-party entities, facilitating maritime trade. Greece followed closely, pioneering mortgages, which are loans secured by underlying assets that can be seized in case of default. Later, in the 12th century, the first government loan was issued, marking a significant turning point in financial history.
Once government debt is established, it becomes the largest driving force in the debt capital market, primarily due to the enormous costs of war—from the prestiti in Venice in the 11th century, to the first loan from the Bank of England in the 17th century, to the first issuance of U.S. Treasury bonds in 1917. Recently, from 2000 to 2007, the global fixed income market size doubled, with its growth again attributed to government printing money to fund various projects. Today, nearly 60% of the global bond market consists of government debt.
In this era where tradition and innovation intertwine, the field of cryptocurrency is redefining the concept of fixed income. The emergence of blockchain technology and smart contracts has brought unprecedented transparency, programmability, and global accessibility to fixed income products. Decentralized financial protocols are creating new lending mechanisms, breaking down the barriers of traditional financial intermediaries, reducing transaction costs, and improving capital allocation efficiency.
The development of the digital asset fixed income market not only provides investors with new sources of income but also opens new pathways for global financial inclusivity. Through lending agreements that are automatically executed via smart contracts, efficient allocation of funds can be achieved without the need for traditional bank approval processes. This innovative model is reshaping our understanding of risk management, income generation, and capital flow.
With the gradual improvement of the regulatory environment and the continuous maturation of technological infrastructure, the cryptocurrency fixed income market is ushering in a golden period of rapid development. The participation of institutional investors, the refinement of the stablecoin ecosystem, and the enhancement of cross-chain interoperability are all driving this market toward a more mature and professional direction.
In this era of digital finance full of opportunities, #Treehouse and $TREE are building a bridge to digital asset returns for investors with their innovative fixed income solutions, opening a new chapter in fixed income investment.