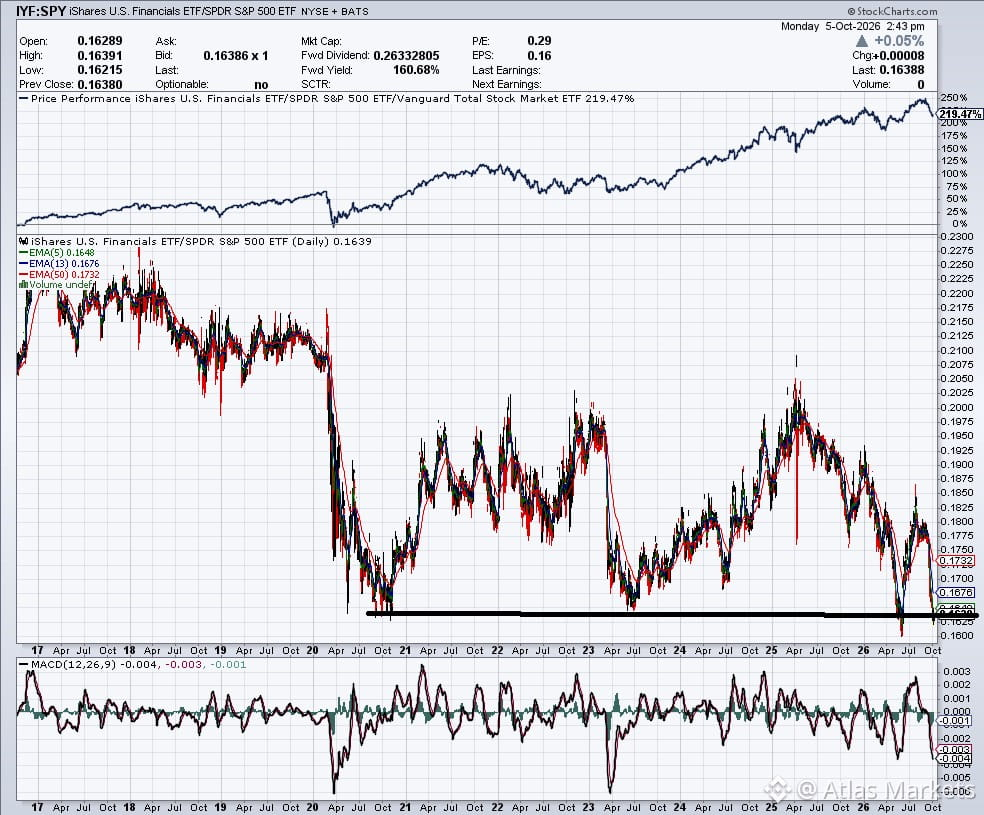
The $IYF to $SPY ratio just hit 0.1639—one of the lowest levels in the past decade. Historically, when it gets this stretched, a long $IYF / short $SPY pair trade has worked well.
I'm adding this to my existing long $XLP / short $SPY position. Both setups are betting on mean reversion: financials and staples have been left behind relative to the broader index, and that gap tends to close. This is a structural trade, not a short-term flip—looking for a multi-month unwind as rotation kicks in.
I'm adding this to my existing long $XLP / short $SPY position. Both setups are betting on mean reversion: financials and staples have been left behind relative to the broader index, and that gap tends to close. This is a structural trade, not a short-term flip—looking for a multi-month unwind as rotation kicks in.