Micron Q4 Earnings: Can the Memory Supercycle Last? $MU
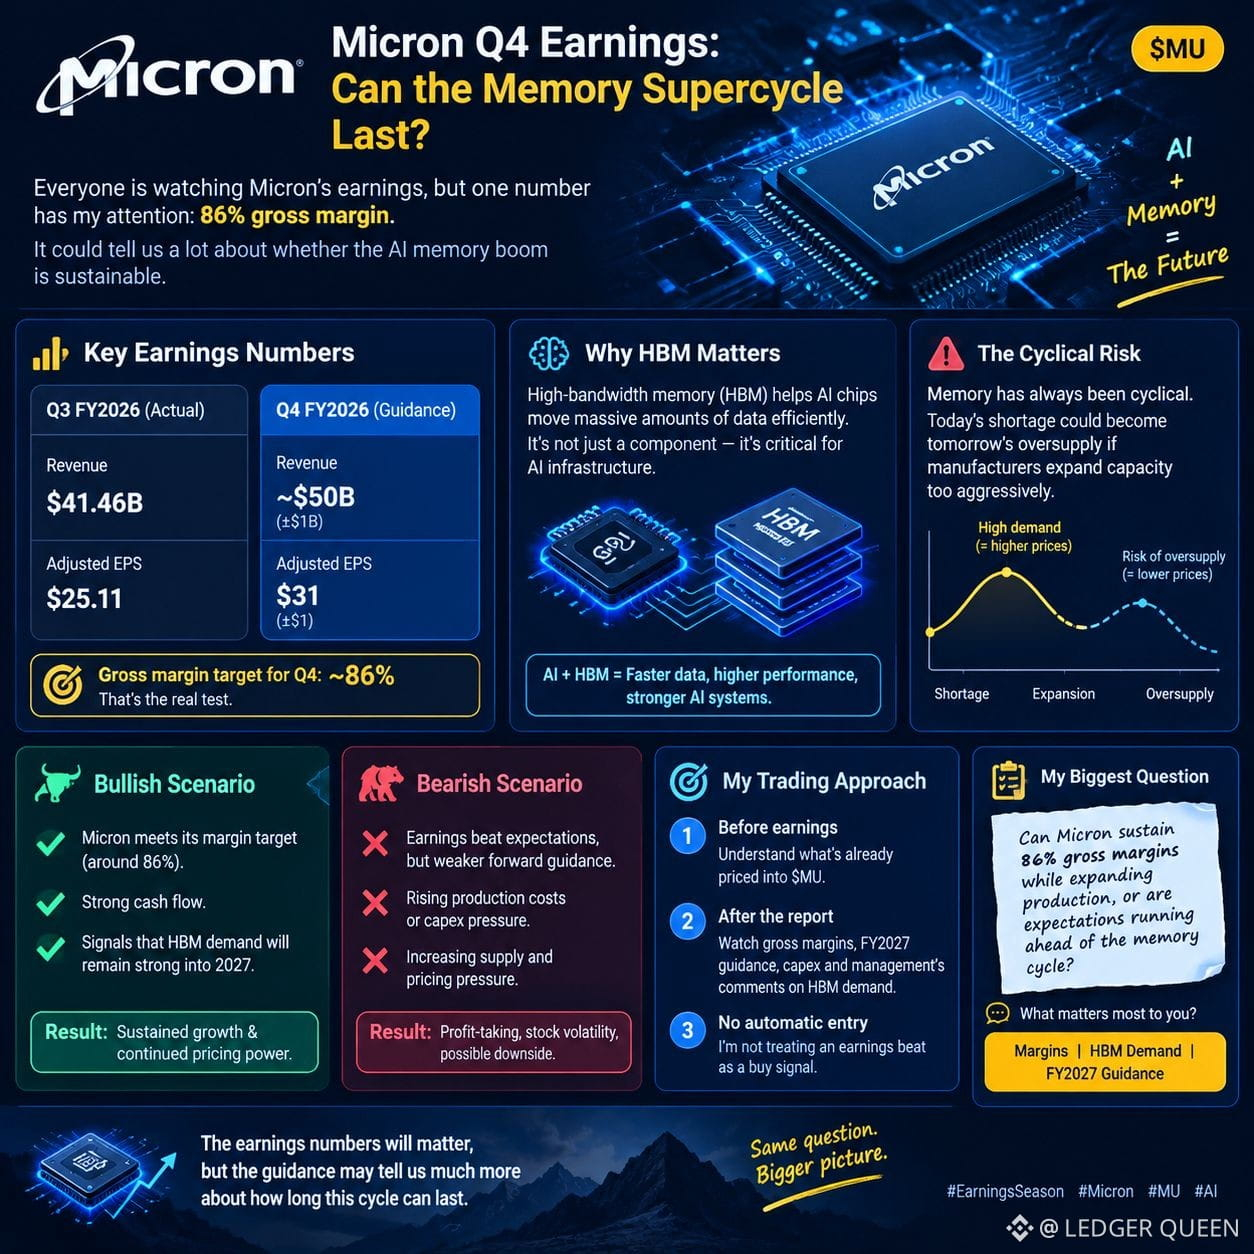
Everyone is watching Micron's earnings, but one number has my attention: 86% gross margin.
Micron's Q3 revenue reached $41.46 billion, with adjusted EPS of $25.11. For Q4 FY2026, management guided for approximately $50 billion in revenue and $31 adjusted EPS.
That's a huge expectation. But can Micron deliver?
🧠 Why HBM matters
AI chips need high-bandwidth memory (HBM) to process massive amounts of data efficiently. As AI infrastructure expands, memory is becoming a critical part of the entire industry.
However, memory has always been cyclical. Today's supply shortage could become tomorrow's oversupply if manufacturers expand capacity too aggressively.
📊 My bullish vs. bearish scenarios
Bullish: Micron meets its margin target, delivers strong cash flow, and signals that HBM demand will remain strong into 2027.
Bearish: Earnings beat expectations, but weaker forward guidance, rising production costs, or increasing supply pressure disappoint the market.
A great earnings report doesn't automatically mean a stock will rise. Expectations matter just as much as results.
🎯 My approach
Before earnings, I'm watching what's already priced into $MU . After the report, I'll focus on gross margins, FY2027 guidance, capital expenditure, and management's comments on HBM demand.
I'm not treating an earnings beat as an automatic entry signal.
My biggest question: Can Micron sustain 86% gross margins while expanding production, or are expectations running ahead of the memory cycle?
What matters most to you: margins, HBM demand, or FY2027 guidance?
#EarningsSeason
$OG
$CRV