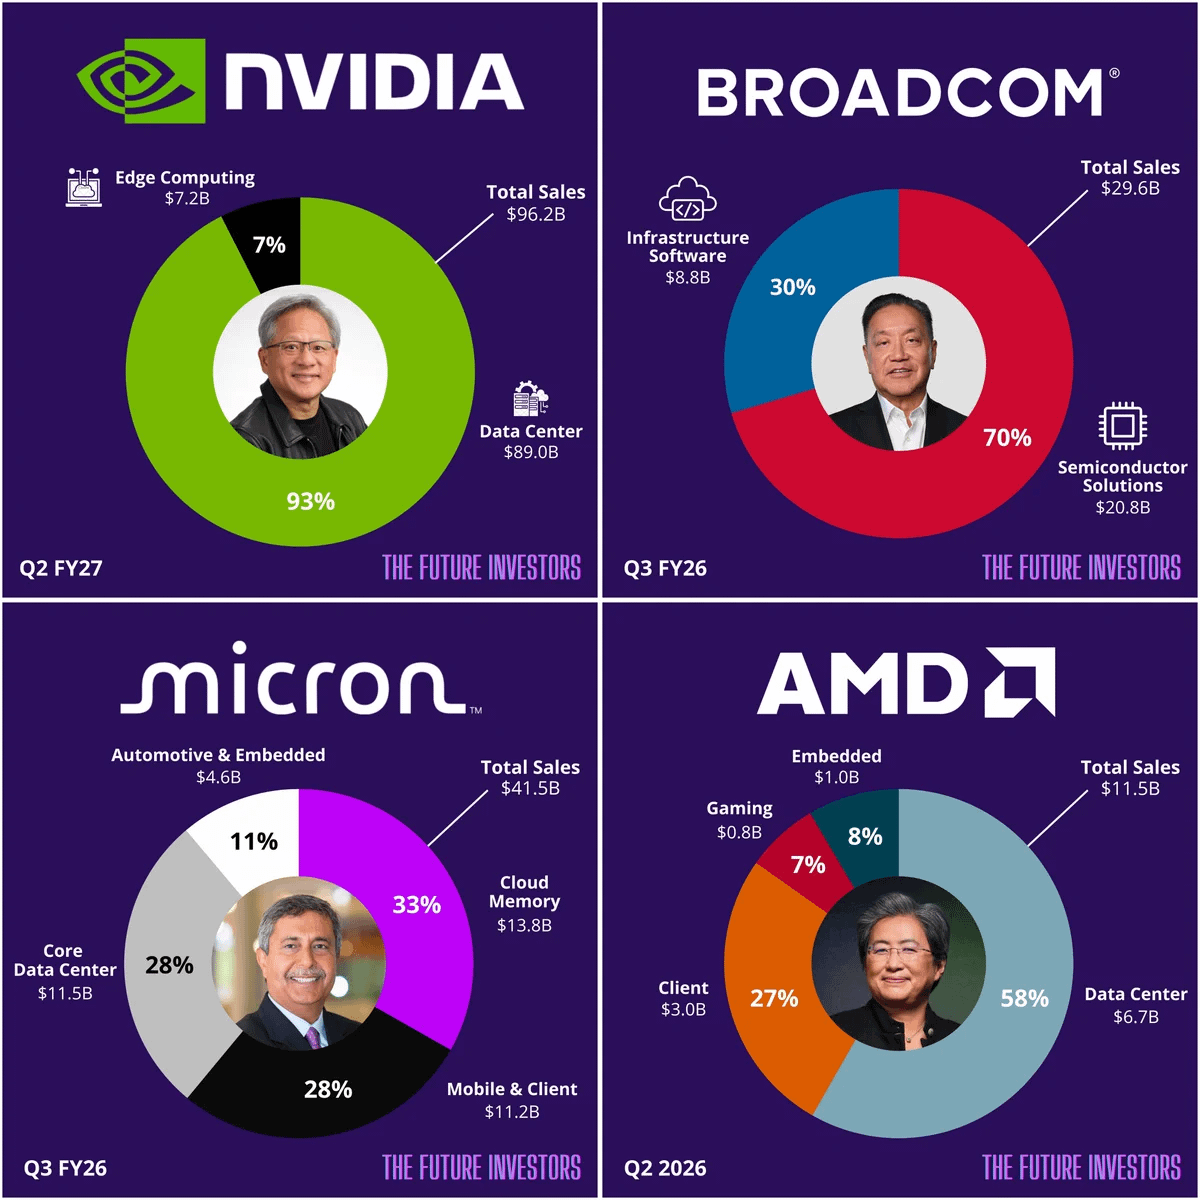
🚨 $NVDA — this chart shows exactly why Nvidia is still the purest AI infrastructure trade.
Look at the revenue mix.
Nvidia is generating roughly 93% of the sales shown here from Data Center, compared with:
Broadcom: ~70% from semiconductor solutions
$AMD : ~58% from Data Center
Micron ($MU ): ~33% from Cloud Memory
That concentration tells you one thing very clearly:
When AI infrastructure spending accelerates, NVDA feels it first — and usually the hardest.
This is the real trigger:
AI capex rises → hyperscalers buy more GPUs → data-center revenue expands → Nvidia earnings sensitivity increases.
That’s why NVDA keeps trading differently from the rest of semis.
Broadcom has diversification.
AMD has client + gaming exposure.
Micron has memory-cycle exposure.
But Nvidia is still the most direct bet on AI compute demand itself.
NVDA TRADE TRIGGER
Bullish trigger: hold major support + reclaim recent resistance with volume
Momentum confirmation: semiconductor sector strength + AI capex headlines + data-center guidance staying strong
Risk: any slowdown in hyperscaler spending or weaker-than-expected AI infrastructure demand
The chart is basically saying:
If the AI spending cycle keeps expanding, NVDA still has the cleanest revenue exposure to that theme.
And in a momentum market, the leader usually gets bought first.
Would you rather chase the diversified chip names… or trade the company with 93% of this revenue mix tied to Data Center? 👀
#XRPRises8% #AppleGoogleSeekStablecoinTokenizedDepositTalent #NvidiaToBuyAnother$1.5BSBEnergySharesPreIPO #NEARRisesNearly80%InAWeek #CircleLaunchesInstitutionalBTCBackedBorrowing
Look at the revenue mix.
Nvidia is generating roughly 93% of the sales shown here from Data Center, compared with:
Broadcom: ~70% from semiconductor solutions
$AMD : ~58% from Data Center
Micron ($MU ): ~33% from Cloud Memory
That concentration tells you one thing very clearly:
When AI infrastructure spending accelerates, NVDA feels it first — and usually the hardest.
This is the real trigger:
AI capex rises → hyperscalers buy more GPUs → data-center revenue expands → Nvidia earnings sensitivity increases.
That’s why NVDA keeps trading differently from the rest of semis.
Broadcom has diversification.
AMD has client + gaming exposure.
Micron has memory-cycle exposure.
But Nvidia is still the most direct bet on AI compute demand itself.
NVDA TRADE TRIGGER
Bullish trigger: hold major support + reclaim recent resistance with volume
Momentum confirmation: semiconductor sector strength + AI capex headlines + data-center guidance staying strong
Risk: any slowdown in hyperscaler spending or weaker-than-expected AI infrastructure demand
The chart is basically saying:
If the AI spending cycle keeps expanding, NVDA still has the cleanest revenue exposure to that theme.
And in a momentum market, the leader usually gets bought first.
Would you rather chase the diversified chip names… or trade the company with 93% of this revenue mix tied to Data Center? 👀
#XRPRises8% #AppleGoogleSeekStablecoinTokenizedDepositTalent #NvidiaToBuyAnother$1.5BSBEnergySharesPreIPO #NEARRisesNearly80%InAWeek #CircleLaunchesInstitutionalBTCBackedBorrowing