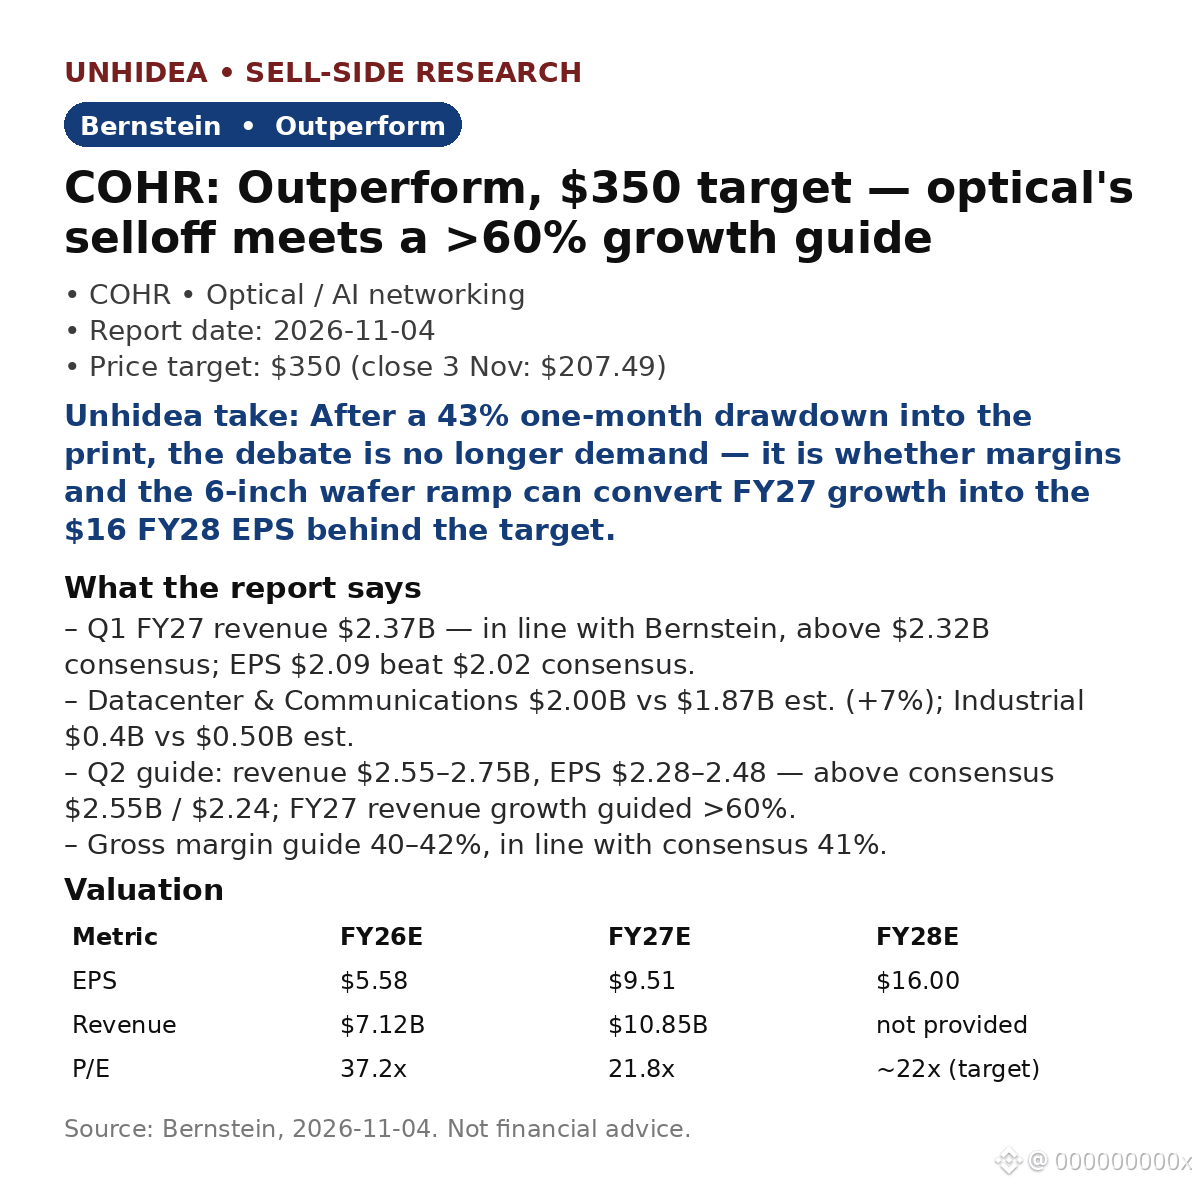
$COHR: Bernstein keeps Outperform, $350 target — ~69% above the $207.49 close on 3 Nov. Optical's selloff just met a >60% growth guide.
Q1 FY27: revenue $2.37B, in line with Bernstein's $2.37B estimate and above $2.32B consensus; EPS $2.09 beat $2.02 consensus. Datacenter did the work: $2.00B vs $1.87B expected (+7%).
- Q2 guide: revenue $2.55–2.75B and EPS $2.28–2.48, above consensus $2.55B/$2.24; FY27 revenue growth guided above 60%.
- Valuation: $350 = ~22x Bernstein's FY28E EPS of $16; FY27E EPS $9.51 on revenue of $10.85B; FY27E P/E 21.8x.
- Since the report: shares fell 6.75% on 16 Nov, then bounced ~11% premarket on 17 Nov as optical names recovered ahead of Nvidia earnings (market coverage, 17 Nov).
Unhidea take: after a 43% one-month drawdown, the repricing is about plumbing, not hype — the InP bottleneck is the moat, and the Marvell–Lumentum deal leaves Coherent the remaining independent optical pure-play.
Unhidea take: the open question is margins, not demand — Bernstein calls margins disappointing, and the 6-inch wafer ramp decides whether FY27 growth converts into that $16 FY28 EPS.
Risks: margin ramp slips; InP pricing fades; VCSEL scale-up unproven; the Lumentum deal reshapes competition.
Source: Bernstein, 4 Nov 2026. Not financial advice.
Q1 FY27: revenue $2.37B, in line with Bernstein's $2.37B estimate and above $2.32B consensus; EPS $2.09 beat $2.02 consensus. Datacenter did the work: $2.00B vs $1.87B expected (+7%).
- Q2 guide: revenue $2.55–2.75B and EPS $2.28–2.48, above consensus $2.55B/$2.24; FY27 revenue growth guided above 60%.
- Valuation: $350 = ~22x Bernstein's FY28E EPS of $16; FY27E EPS $9.51 on revenue of $10.85B; FY27E P/E 21.8x.
- Since the report: shares fell 6.75% on 16 Nov, then bounced ~11% premarket on 17 Nov as optical names recovered ahead of Nvidia earnings (market coverage, 17 Nov).
Unhidea take: after a 43% one-month drawdown, the repricing is about plumbing, not hype — the InP bottleneck is the moat, and the Marvell–Lumentum deal leaves Coherent the remaining independent optical pure-play.
Unhidea take: the open question is margins, not demand — Bernstein calls margins disappointing, and the 6-inch wafer ramp decides whether FY27 growth converts into that $16 FY28 EPS.
Risks: margin ramp slips; InP pricing fades; VCSEL scale-up unproven; the Lumentum deal reshapes competition.
Source: Bernstein, 4 Nov 2026. Not financial advice.