$WMT: Morgan Stanley stays Overweight into Thursday's print — the bet is bundling
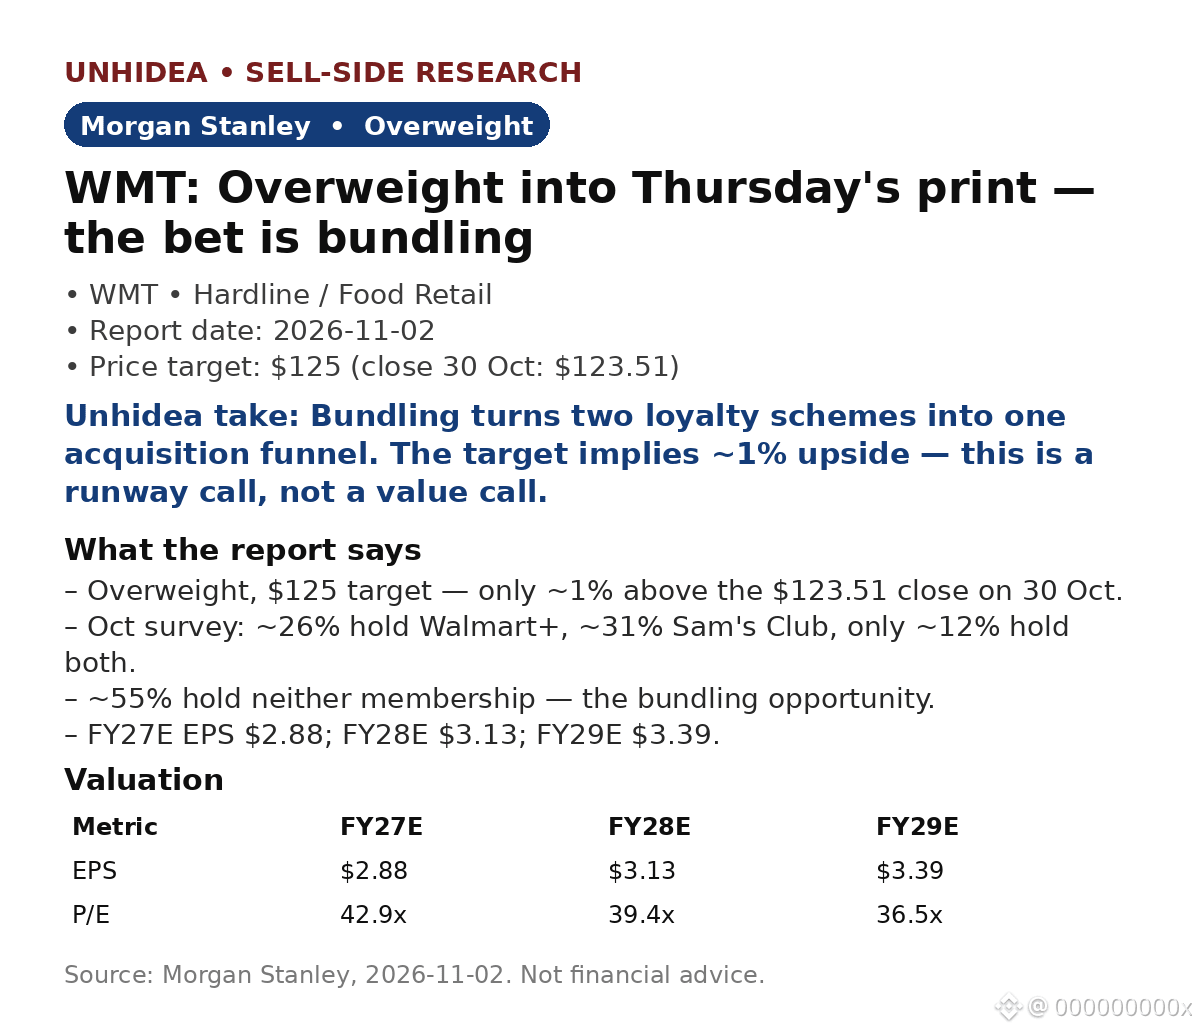
MS's 2 Nov note: Overweight, $125 target — just ~1% above the $123.51 close on 30 Oct. The call is about membership: its Oct survey finds ~26% hold Walmart+, ~31% Sam's Club, only ~12% both — while ~55% hold neither.
- The gap is the opportunity: ~14% hold only Walmart+ and ~19% only Sam's — natural cross-sell targets.
- Valuation: $125 = ~36.8x F'29E EPS of $3.39, vs a 10-year average P/E of ~21x — a premium MS says the e-commerce shift earns.
- Estimates: FY27E EPS $2.88, FY28E $3.13, FY29E $3.39; Q3 FY27E EPS $0.63, actual print due Thu 19 Nov.
Unhidea take: the 55% holding neither is the real prize — bundling turns two loyalty schemes into one acquisition funnel, closer to Costco's flywheel than a grocery card.
Unhidea take: with the target ~1% above the Oct close, this Overweight is a runway call, not a value call — Thursday's print must show it in comps, not just a survey.
Risks: e-commerce losses could widen; US e-comm growth below 15% undercuts the thesis; Flipkart losses. Survey is a first read.
Source: Morgan Stanley, 2 Nov 2026. Not financial advice.
MS's 2 Nov note: Overweight, $125 target — just ~1% above the $123.51 close on 30 Oct. The call is about membership: its Oct survey finds ~26% hold Walmart+, ~31% Sam's Club, only ~12% both — while ~55% hold neither.
- The gap is the opportunity: ~14% hold only Walmart+ and ~19% only Sam's — natural cross-sell targets.
- Valuation: $125 = ~36.8x F'29E EPS of $3.39, vs a 10-year average P/E of ~21x — a premium MS says the e-commerce shift earns.
- Estimates: FY27E EPS $2.88, FY28E $3.13, FY29E $3.39; Q3 FY27E EPS $0.63, actual print due Thu 19 Nov.
Unhidea take: the 55% holding neither is the real prize — bundling turns two loyalty schemes into one acquisition funnel, closer to Costco's flywheel than a grocery card.
Unhidea take: with the target ~1% above the Oct close, this Overweight is a runway call, not a value call — Thursday's print must show it in comps, not just a survey.
Risks: e-commerce losses could widen; US e-comm growth below 15% undercuts the thesis; Flipkart losses. Survey is a first read.
Source: Morgan Stanley, 2 Nov 2026. Not financial advice.