$LOW: Bernstein keeps Outperform, $270 target — guidance de-risked into today's Q3 print
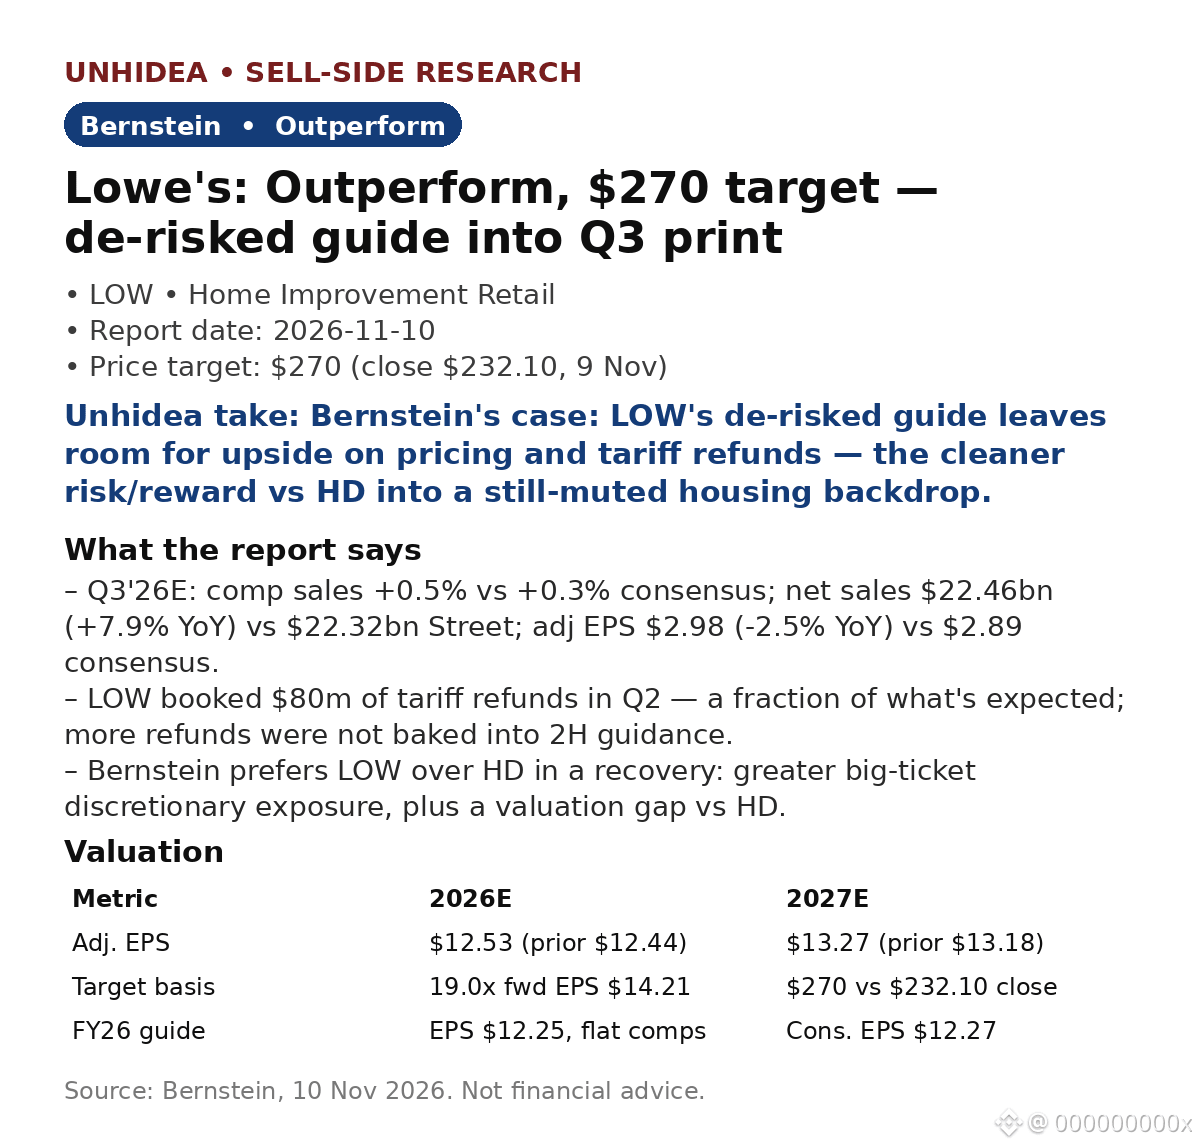
Bernstein's 10 Nov preview: Lowe's reports Q3'26 before the open today (18 Nov). Its FY26 guide of flat comps assumes no weather benefit and no further tariff refunds. Target raised to $270 from $254 — ~16% above the $232.10 close on 9 Nov.
- Q3 preview: comp sales +0.5% vs +0.3% consensus; net sales $22.46bn (+7.9% YoY) vs $22.32bn Street; adj EPS $2.98 (-2.5% YoY) vs $2.89 consensus.
- Tariff refunds: LOW booked $80m in Q2, a fraction of what's expected — extra refunds could offset fuel/freight inflation or fund promotions.
- Valuation: FY26E adj EPS $12.53 (prior $12.44) vs $12.25 guide; FY27E $13.27. Target = 19.0x forward EPS $14.21 (was 18.0x).
Unhidea take: with the bar at flat comps, modest pricing power shows up as a beat — and tariff refunds are a free option the guide ignores.
Unhidea take: LOW is Bernstein's preferred recovery play over HD — bigger big-ticket exposure means a sharper rebound if housing turns, a deeper wait if it doesn't.
Risks: muted housing demand, tariff/freight inflation, weak resi construction hitting Pro.
Context: HD reported 17 Nov — sales $43.4bn beat ~$42.8bn expected, shares -2% (CNBC).
Source: Bernstein, 10 Nov 2026. Not financial advice.
https://unhidea.com/en/articles/research-972aba8288b2492db4a299efd9035504-en
Bernstein's 10 Nov preview: Lowe's reports Q3'26 before the open today (18 Nov). Its FY26 guide of flat comps assumes no weather benefit and no further tariff refunds. Target raised to $270 from $254 — ~16% above the $232.10 close on 9 Nov.
- Q3 preview: comp sales +0.5% vs +0.3% consensus; net sales $22.46bn (+7.9% YoY) vs $22.32bn Street; adj EPS $2.98 (-2.5% YoY) vs $2.89 consensus.
- Tariff refunds: LOW booked $80m in Q2, a fraction of what's expected — extra refunds could offset fuel/freight inflation or fund promotions.
- Valuation: FY26E adj EPS $12.53 (prior $12.44) vs $12.25 guide; FY27E $13.27. Target = 19.0x forward EPS $14.21 (was 18.0x).
Unhidea take: with the bar at flat comps, modest pricing power shows up as a beat — and tariff refunds are a free option the guide ignores.
Unhidea take: LOW is Bernstein's preferred recovery play over HD — bigger big-ticket exposure means a sharper rebound if housing turns, a deeper wait if it doesn't.
Risks: muted housing demand, tariff/freight inflation, weak resi construction hitting Pro.
Context: HD reported 17 Nov — sales $43.4bn beat ~$42.8bn expected, shares -2% (CNBC).
Source: Bernstein, 10 Nov 2026. Not financial advice.
https://unhidea.com/en/articles/research-972aba8288b2492db4a299efd9035504-en