$AMD: Bernstein holds Outperform, $650 target — server revenues set to double in 2027 as the PC market cracks
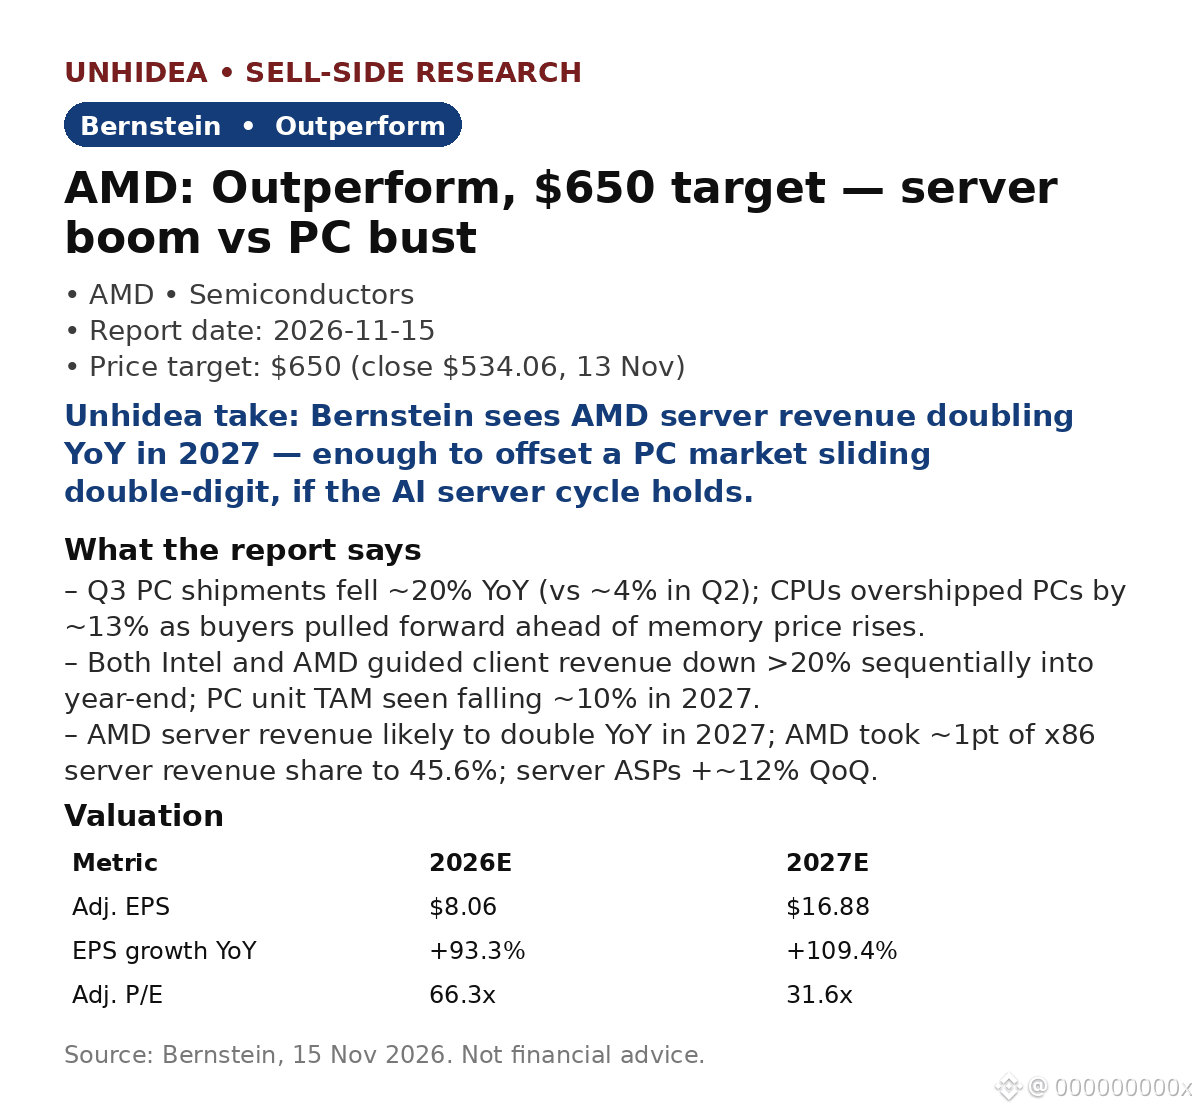
Bernstein's 15 Nov note splits AMD in two: a PC business heading into a bust, and a server business about to double. Q3 PC shipments fell ~20% YoY (vs ~4% in Q2) as CPUs overshipped PCs by ~13% on pull-forward ahead of memory price rises. Both Intel and AMD guided client revenue down >20% sequentially into year-end.
- Server offset: AMD server revenue is likely to double YoY in 2027; AMD took ~1pt of x86 server revenue share to 45.6% as server ASPs rose ~12% QoQ (+34% YoY).
- Estimates: 2027E adj. EPS $16.88 vs $8.06 in 2026E (+109% YoY); the $650 target is ~31x avg FY27/28 EPS ($20.83), ~22% above the $534.06 close on 13 Nov.
Unhidea take: the PC bust is real, but for AMD it is a mix-shift story, not a demand story — servers and AI accelerators are where the growth lives.
Unhidea take: memory is the swing factor: rising prices deepen the pull-forward hangover, but tight memory also caps rival supply, rewarding AMD's better-managed supply chain.
Risks: PC declines, GPU customer concentration, margins, AI spending sustainability.
Context: $NVDA reports after the close today (17 Nov).
Source: Bernstein, 15 Nov 2026. Not financial advice.
Bernstein's 15 Nov note splits AMD in two: a PC business heading into a bust, and a server business about to double. Q3 PC shipments fell ~20% YoY (vs ~4% in Q2) as CPUs overshipped PCs by ~13% on pull-forward ahead of memory price rises. Both Intel and AMD guided client revenue down >20% sequentially into year-end.
- Server offset: AMD server revenue is likely to double YoY in 2027; AMD took ~1pt of x86 server revenue share to 45.6% as server ASPs rose ~12% QoQ (+34% YoY).
- Estimates: 2027E adj. EPS $16.88 vs $8.06 in 2026E (+109% YoY); the $650 target is ~31x avg FY27/28 EPS ($20.83), ~22% above the $534.06 close on 13 Nov.
Unhidea take: the PC bust is real, but for AMD it is a mix-shift story, not a demand story — servers and AI accelerators are where the growth lives.
Unhidea take: memory is the swing factor: rising prices deepen the pull-forward hangover, but tight memory also caps rival supply, rewarding AMD's better-managed supply chain.
Risks: PC declines, GPU customer concentration, margins, AI spending sustainability.
Context: $NVDA reports after the close today (17 Nov).
Source: Bernstein, 15 Nov 2026. Not financial advice.