$DIS: Morgan Stanley raises PT to $133 from $125, reiterates Overweight — cruise is now the growth story
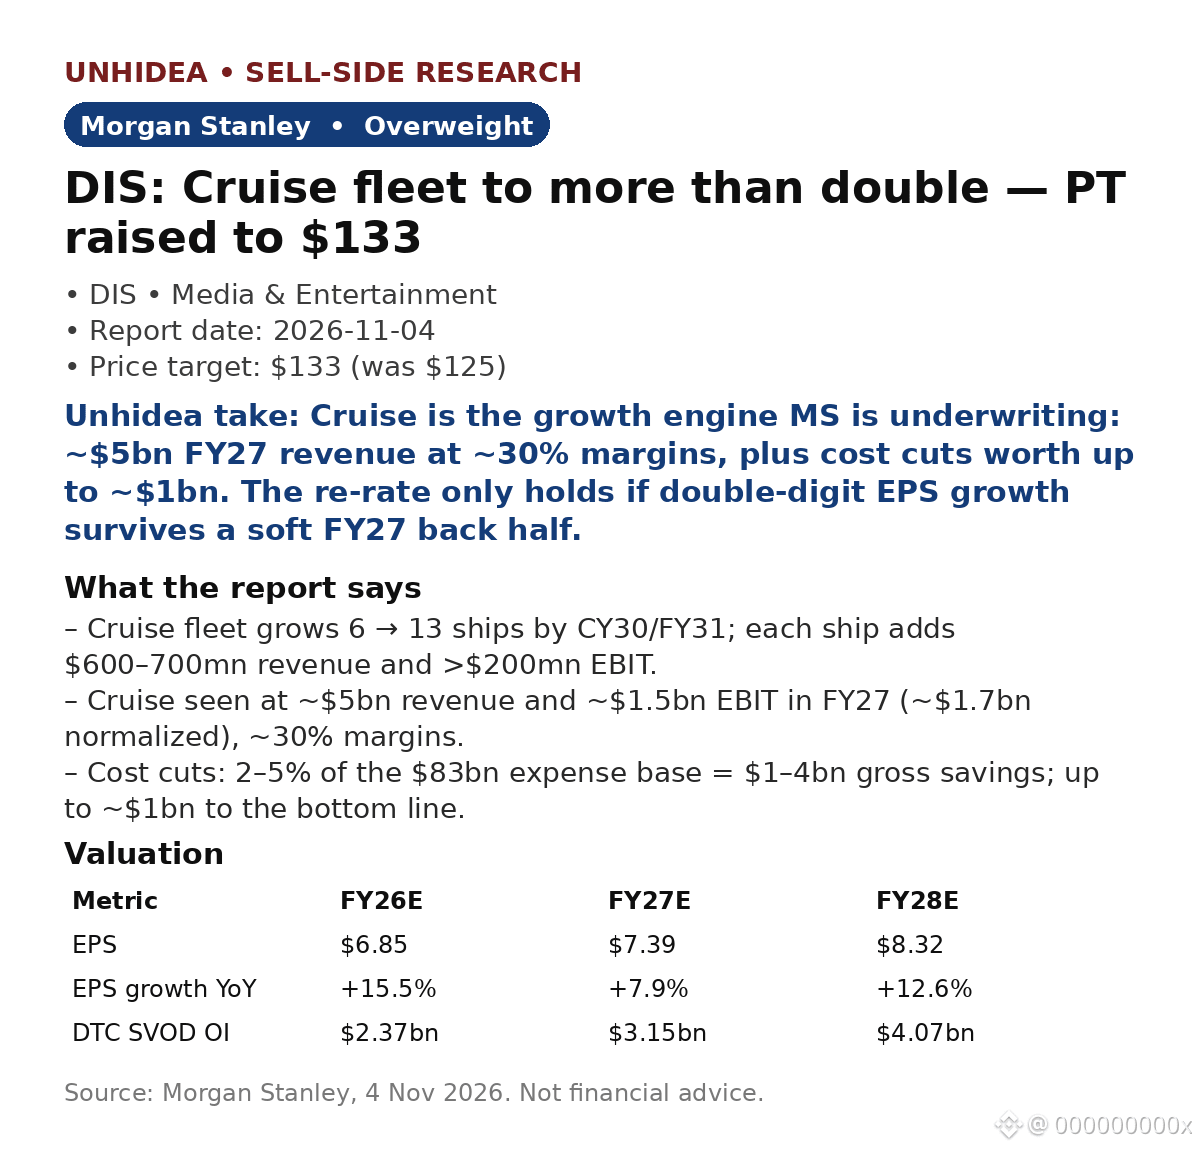
MS sees Disney "cruising to double-digit EPS growth": fleet 6 → 13 ships by CY30/FY31, each adding $600–700mn revenue and >$200mn EBIT. Cruise seen at ~$5bn revenue, ~$1.5bn EBIT in FY27 (~$1.7bn normalized), ~30% margins.
- Estimates: FY26E EPS $6.85 (+15.5% YoY) vs $7.19 consensus; FY27E $7.39 (+7.9%); FY28E $8.32 (+12.6%) — the base for the $133 PT at 16x (was 15x).
- Cost cuts are a new lever: 2–5% of the $83bn expense base = $1–4bn savings; up to ~$1bn to the bottom line.
- Streaming scales: DTC SVOD operating income $1.30bn in FY25 → $2.37bn FY26E → $4.07bn FY28E.
Unhidea take: MS is underwriting a cruise-led re-rate, not a parks recovery — the fleet is the cleanest incremental capex in the portfolio.
Unhidea take: watch the timing — FY27 is front-half weighted and F4Q faces a 53rd-week headwind.
Fresh print (17 Nov, after the report): Disney beat — revenue +16% to $25.95bn, adj EPS $1.77 vs ~$1.67 expected; parks, streaming, ESPN all grew.
Risks: macro weakness, pay-TV cord-cutting, franchise fatigue. Bull $152 / bear $97. Source: Morgan Stanley, 4 Nov 2026. Not financial advice.
MS sees Disney "cruising to double-digit EPS growth": fleet 6 → 13 ships by CY30/FY31, each adding $600–700mn revenue and >$200mn EBIT. Cruise seen at ~$5bn revenue, ~$1.5bn EBIT in FY27 (~$1.7bn normalized), ~30% margins.
- Estimates: FY26E EPS $6.85 (+15.5% YoY) vs $7.19 consensus; FY27E $7.39 (+7.9%); FY28E $8.32 (+12.6%) — the base for the $133 PT at 16x (was 15x).
- Cost cuts are a new lever: 2–5% of the $83bn expense base = $1–4bn savings; up to ~$1bn to the bottom line.
- Streaming scales: DTC SVOD operating income $1.30bn in FY25 → $2.37bn FY26E → $4.07bn FY28E.
Unhidea take: MS is underwriting a cruise-led re-rate, not a parks recovery — the fleet is the cleanest incremental capex in the portfolio.
Unhidea take: watch the timing — FY27 is front-half weighted and F4Q faces a 53rd-week headwind.
Fresh print (17 Nov, after the report): Disney beat — revenue +16% to $25.95bn, adj EPS $1.77 vs ~$1.67 expected; parks, streaming, ESPN all grew.
Risks: macro weakness, pay-TV cord-cutting, franchise fatigue. Bull $152 / bear $97. Source: Morgan Stanley, 4 Nov 2026. Not financial advice.