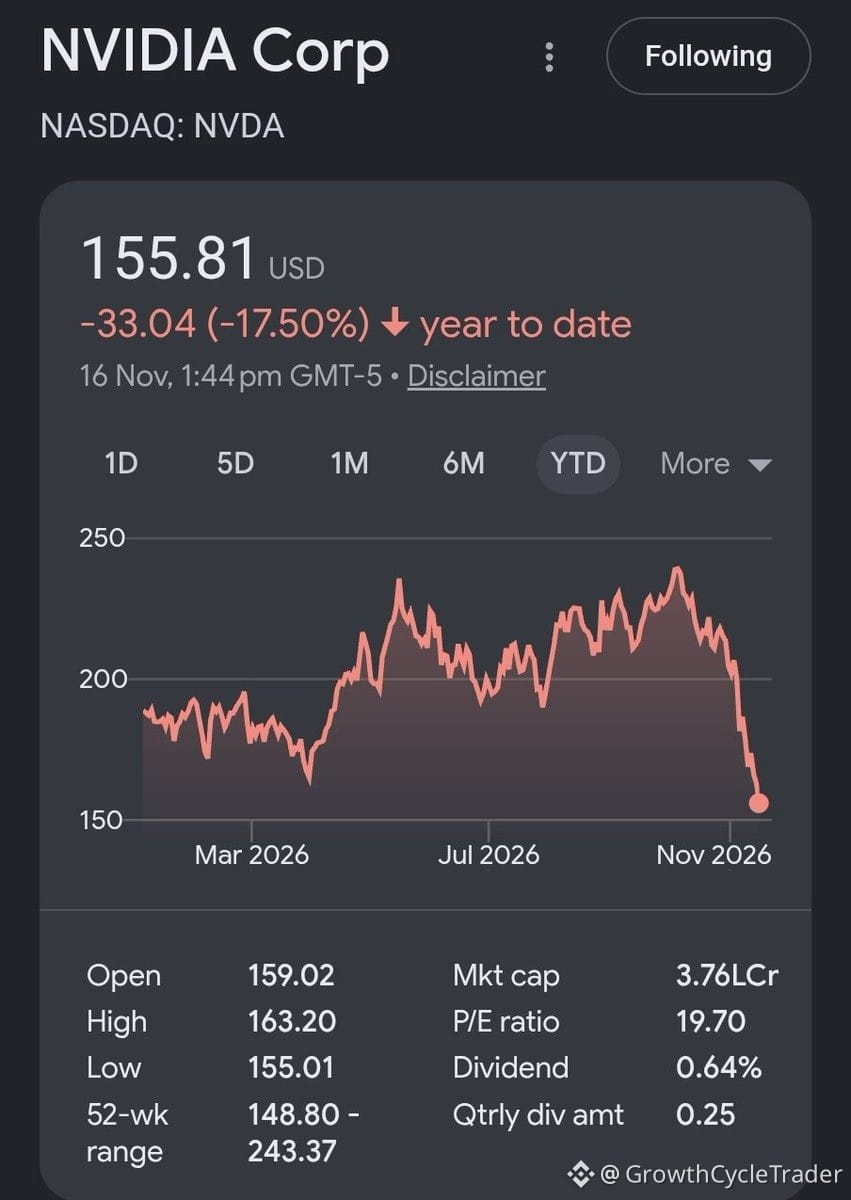
Nvidia's data center revenue hit $30.8B last quarter — up 17% QoQ and 112% YoY. That's the kind of growth that separates market leaders from the rest.
Here's what matters: Hopper demand is still strong, and Blackwell is ramping faster than expected. The supply chain is finally catching up, and hyperscalers are still in full build-out mode.
This isn't just about AI hype anymore. It's about infrastructure spend becoming structural. Cloud providers, enterprises, and sovereign AI projects are all competing for the same limited supply of GPUs.
Margin expansion continues. Gross margins held at 75%, even with the product mix shifting toward newer architectures. That's pricing power.
The Street is still underestimating the durability of this cycle. We're not in the late innings — we're in the middle of a multi-year infrastructure upgrade.
$NVDA remains the cleanest way to play AI capex. The numbers speak for themselves.
Here's what matters: Hopper demand is still strong, and Blackwell is ramping faster than expected. The supply chain is finally catching up, and hyperscalers are still in full build-out mode.
This isn't just about AI hype anymore. It's about infrastructure spend becoming structural. Cloud providers, enterprises, and sovereign AI projects are all competing for the same limited supply of GPUs.
Margin expansion continues. Gross margins held at 75%, even with the product mix shifting toward newer architectures. That's pricing power.
The Street is still underestimating the durability of this cycle. We're not in the late innings — we're in the middle of a multi-year infrastructure upgrade.
$NVDA remains the cleanest way to play AI capex. The numbers speak for themselves.