Anthropic pre-listing contracts: arbitrage isn't about price spread—it's about understanding conversion risk
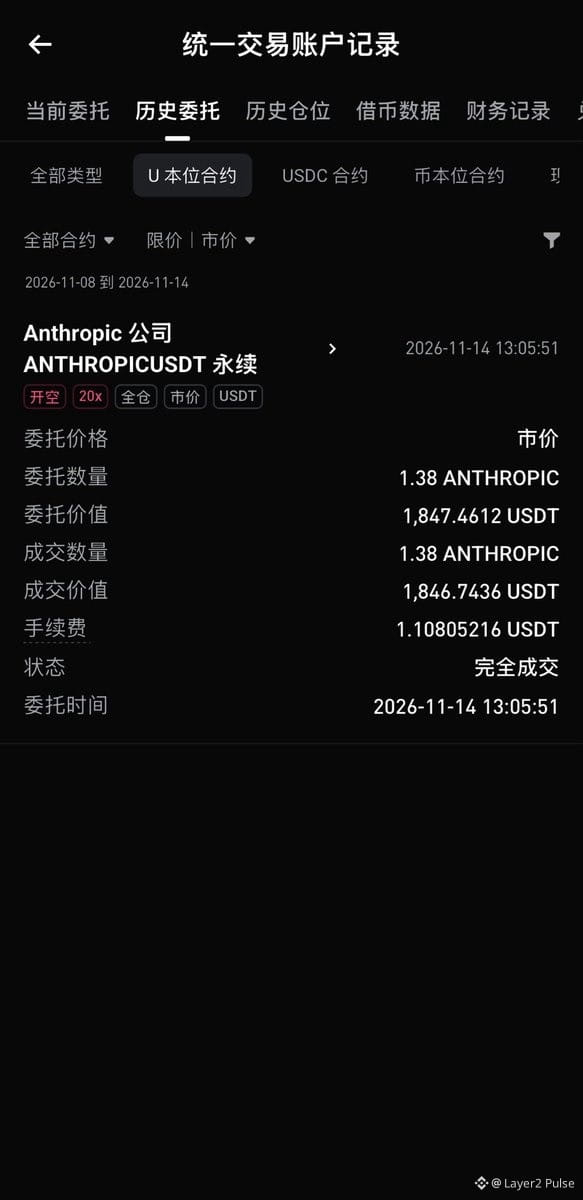
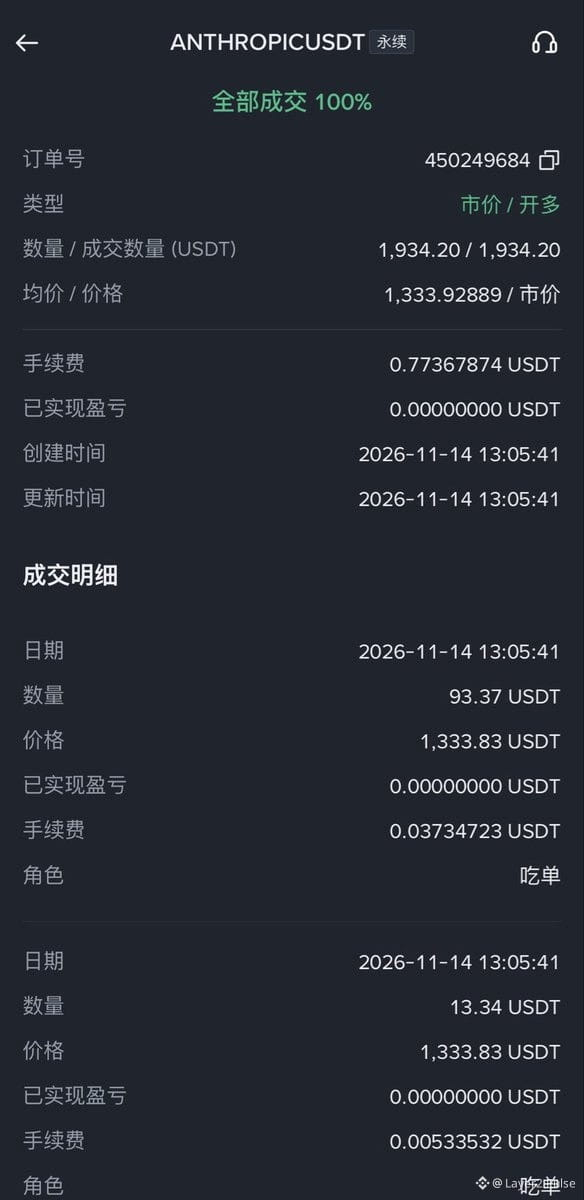
Just went live with cross-exchange arb on Anthropic. Long one side, short the other. Most degens only watch the spread, chasing arb profits, completely blind to the biggest trap: share conversion at listing.
Per latest SEC S-1/A: Anthropic lists at 130.87B total shares. Current pre-market contracts? Priced on 1B share assumption. When listing hits (Nov 18 expected, conversion kicks in 1-2 days prior), platforms recalculate: 1 old contract splits into ~13.09 new contracts. Per-contract price drops proportionally. Nominal position value stays same in theory.
Here's where people get liquidated:
During conversion, exchanges halt trading. ALL orders—limit orders, TP/SL, conditional orders—get cancelled. Zero auto-restoration.
I'm running dual-direction hedge right now. My protection orders? Gone when conversion hits. Traders set TP/SL once and forget, assuming system inherits settings. Conversion wipes everything clean. If margin buffer is tight, when trading resumes and price moves one direction hard, accidental liquidation. Has nothing to do with directional calls—pure process risk.
Three practical moves:
1. Mark these dates: conversion halt, trading resume, Nov 18 official listing. Don't miss them.
2. Keep fat margin cushion before conversion. Don't max out leverage. You need buffer for post-conversion volatility.
3. Manually reset TP/SL the second trading resumes. System memory = zero.
Extra note: actual conversion ratio across exchanges may differ from the 13.09x calculation. For cross-platform hedges like mine, verify nominal values match on both sides immediately after open. Alpha is visible, risk hides in rule gaps. Protect position first, chase profits second.
Just went live with cross-exchange arb on Anthropic. Long one side, short the other. Most degens only watch the spread, chasing arb profits, completely blind to the biggest trap: share conversion at listing.
Per latest SEC S-1/A: Anthropic lists at 130.87B total shares. Current pre-market contracts? Priced on 1B share assumption. When listing hits (Nov 18 expected, conversion kicks in 1-2 days prior), platforms recalculate: 1 old contract splits into ~13.09 new contracts. Per-contract price drops proportionally. Nominal position value stays same in theory.
Here's where people get liquidated:
During conversion, exchanges halt trading. ALL orders—limit orders, TP/SL, conditional orders—get cancelled. Zero auto-restoration.
I'm running dual-direction hedge right now. My protection orders? Gone when conversion hits. Traders set TP/SL once and forget, assuming system inherits settings. Conversion wipes everything clean. If margin buffer is tight, when trading resumes and price moves one direction hard, accidental liquidation. Has nothing to do with directional calls—pure process risk.
Three practical moves:
1. Mark these dates: conversion halt, trading resume, Nov 18 official listing. Don't miss them.
2. Keep fat margin cushion before conversion. Don't max out leverage. You need buffer for post-conversion volatility.
3. Manually reset TP/SL the second trading resumes. System memory = zero.
Extra note: actual conversion ratio across exchanges may differ from the 13.09x calculation. For cross-platform hedges like mine, verify nominal values match on both sides immediately after open. Alpha is visible, risk hides in rule gaps. Protect position first, chase profits second.